South African fintech startup Lumepay has disclosed a $6 million pre-seed funding round and launched its payments service in Kenya after receiving regulatory clearance from the Central Bank of Kenya, expanding its effort to simplify cross-border transactions for African businesses.
The funding round closed at the beginning of 2026 and was backed by founder-led angel investors and South African fintech investors, according to the company.
Lumepay also secured approximately $10 million in capital float to support liquidity for customers making international payments.
The company provides cross-border payment infrastructure for small and medium-sized enterprises, large corporations and financial institutions that need to pay overseas suppliers, manage foreign exchange and transfer money between African markets.
Its entry into Kenya gives local businesses another option for paying international suppliers in currencies including the Chinese yuan, US dollar and Indian rupee.
Lumepay Chief Executive Harry Huang said the company combines traditional financial infrastructure with digital asset-based settlement systems to address the challenges associated with international payments.
“The future of cross-border payments isn’t traditional finance or stablecoins; it’s a combination of both, backed by the FX depth to make them work for real businesses,” Huang said.
“That’s how we’ve built Lumepay: a rail-agnostic platform that works at the intersection between the two.” MyBroadband
The company’s strategy reflects growing interest in alternative payment infrastructure as African businesses seek more efficient ways to move money across borders.
Traditional international payments can involve multiple intermediary banks, currency conversions and settlement processes, increasing costs and the time required for suppliers to receive funds.
For a Kenyan importer paying a manufacturer in China, for example, the transaction may involve converting Kenyan shillings into US dollars before the funds are converted into yuan and transferred to the supplier.
Each stage can introduce additional foreign exchange costs and processing delays.
Lumepay aims to simplify this process by combining foreign exchange, liquidity management and payment execution through one platform.
The company launched Lumetrade, its digital asset and stablecoin trading platform, in April 2026. It followed this with the launch of its cross-border payments platform in June.
Lumepay says its services are live across the West African CFA franc and Central African CFA franc zones, Nigeria, Ghana, Tanzania, Malawi, Mozambique and Kenya, although the precise payment capabilities available differ by market and regulatory arrangement. MyBroadband
Chief Operating Officer Luc Varejes said the company had used the funding to build liquidity arrangements, payment infrastructure and partnerships across its target markets.
“In the months since the raise, we’ve turned plans into working products: diversified and reliable liquidity; a platform that handles cross-border payments end to end; a growing network of partners and payment rails; and regulatory clearance in South Africa and Kenya, together with licensed partners across Francophone West and Central Africa,” Varejes said. MyBroadband
Kenya is an important market for the expansion because of its established digital payments ecosystem and large community of importers and exporters.
Businesses importing electronics, machinery, industrial equipment, textiles and consumer products from Asia regularly need to settle supplier invoices in foreign currencies.
For these businesses, the ability to compare exchange rates, reduce intermediary charges and receive predictable settlement times can have a direct impact on working capital.
However, Lumepay’s competitive position will depend on the actual costs of its services rather than simply the number of currencies it supports.
Businesses will need to compare the total cost of transactions, including exchange-rate spreads, transfer charges and any intermediary fees.
The regulatory position is also important. Lumepay says it received clearance from the Central Bank of Kenya in October and launched its Kenyan payments service.
The company’s announcement identifies its wider regulatory structure, including its South African payment registration, Canadian registrations and use of licensed partners in certain African markets. The specific scope of the Kenyan authorisation and the regulated entities responsible for individual services should be confirmed independently before treating the approval as permission for all payment and digital asset activities.
This distinction matters because cross-border payments, foreign exchange and digital asset services can fall under different regulatory requirements.
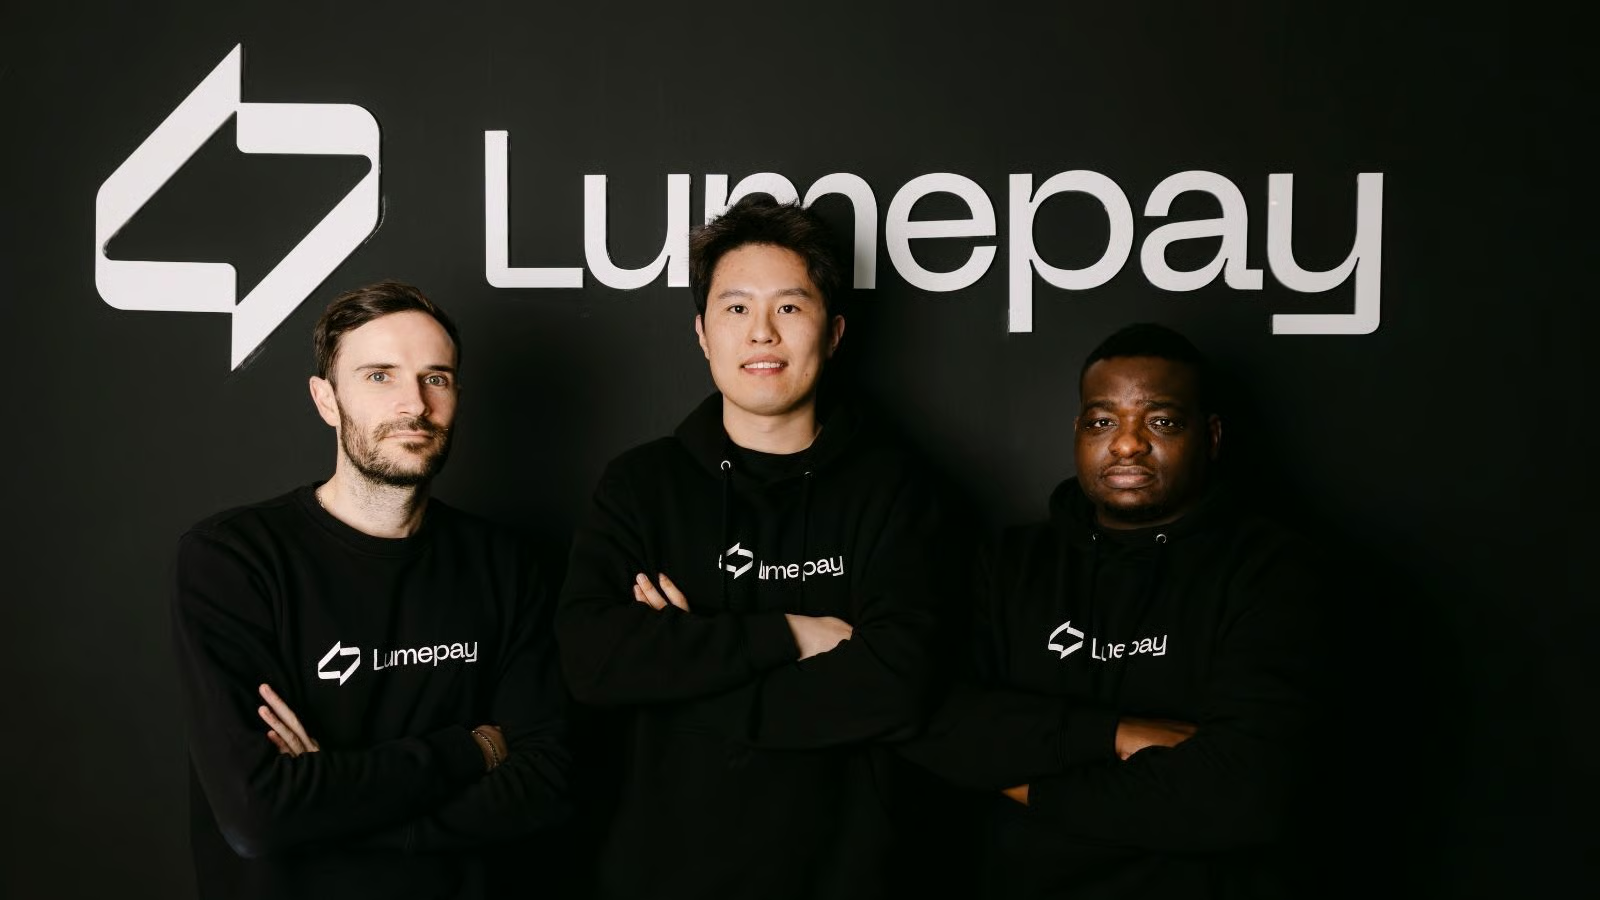
Lumepay is led by Huang, Varejes and Chief Legal and Compliance Officer Tatenda Nhemachena.
The $6 million pre-seed round gives the company resources to expand its infrastructure and develop liquidity relationships as it enters additional African markets.
The additional $10 million capital float is separate from the funding round and is intended to support the movement of customer payments. It should not be treated as additional equity raised by the company.
As more African businesses trade internationally, the market for efficient business-to-business payment infrastructure is likely to attract increased competition from banks, payment companies and stablecoin-based platforms.
Lumepay’s opportunity will be to demonstrate that its combination of traditional payment rails and digital asset infrastructure can deliver reliable settlement at competitive prices.
What comes next
The key test in Kenya will be the cost and reliability of actual supplier payments.
A comparison involving a KSh500,000 invoice to a Chinese supplier, for example, would establish how much a customer pays through Lumepay compared with a commercial bank and another fintech provider.
That comparison should include the final amount received by the supplier, the exchange-rate spread, fees and settlement time.
For Lumepay, Kenya provides an opportunity to demonstrate whether its cross-border payment model can solve a practical problem for African businesses rather than simply offer another digital payments platform.