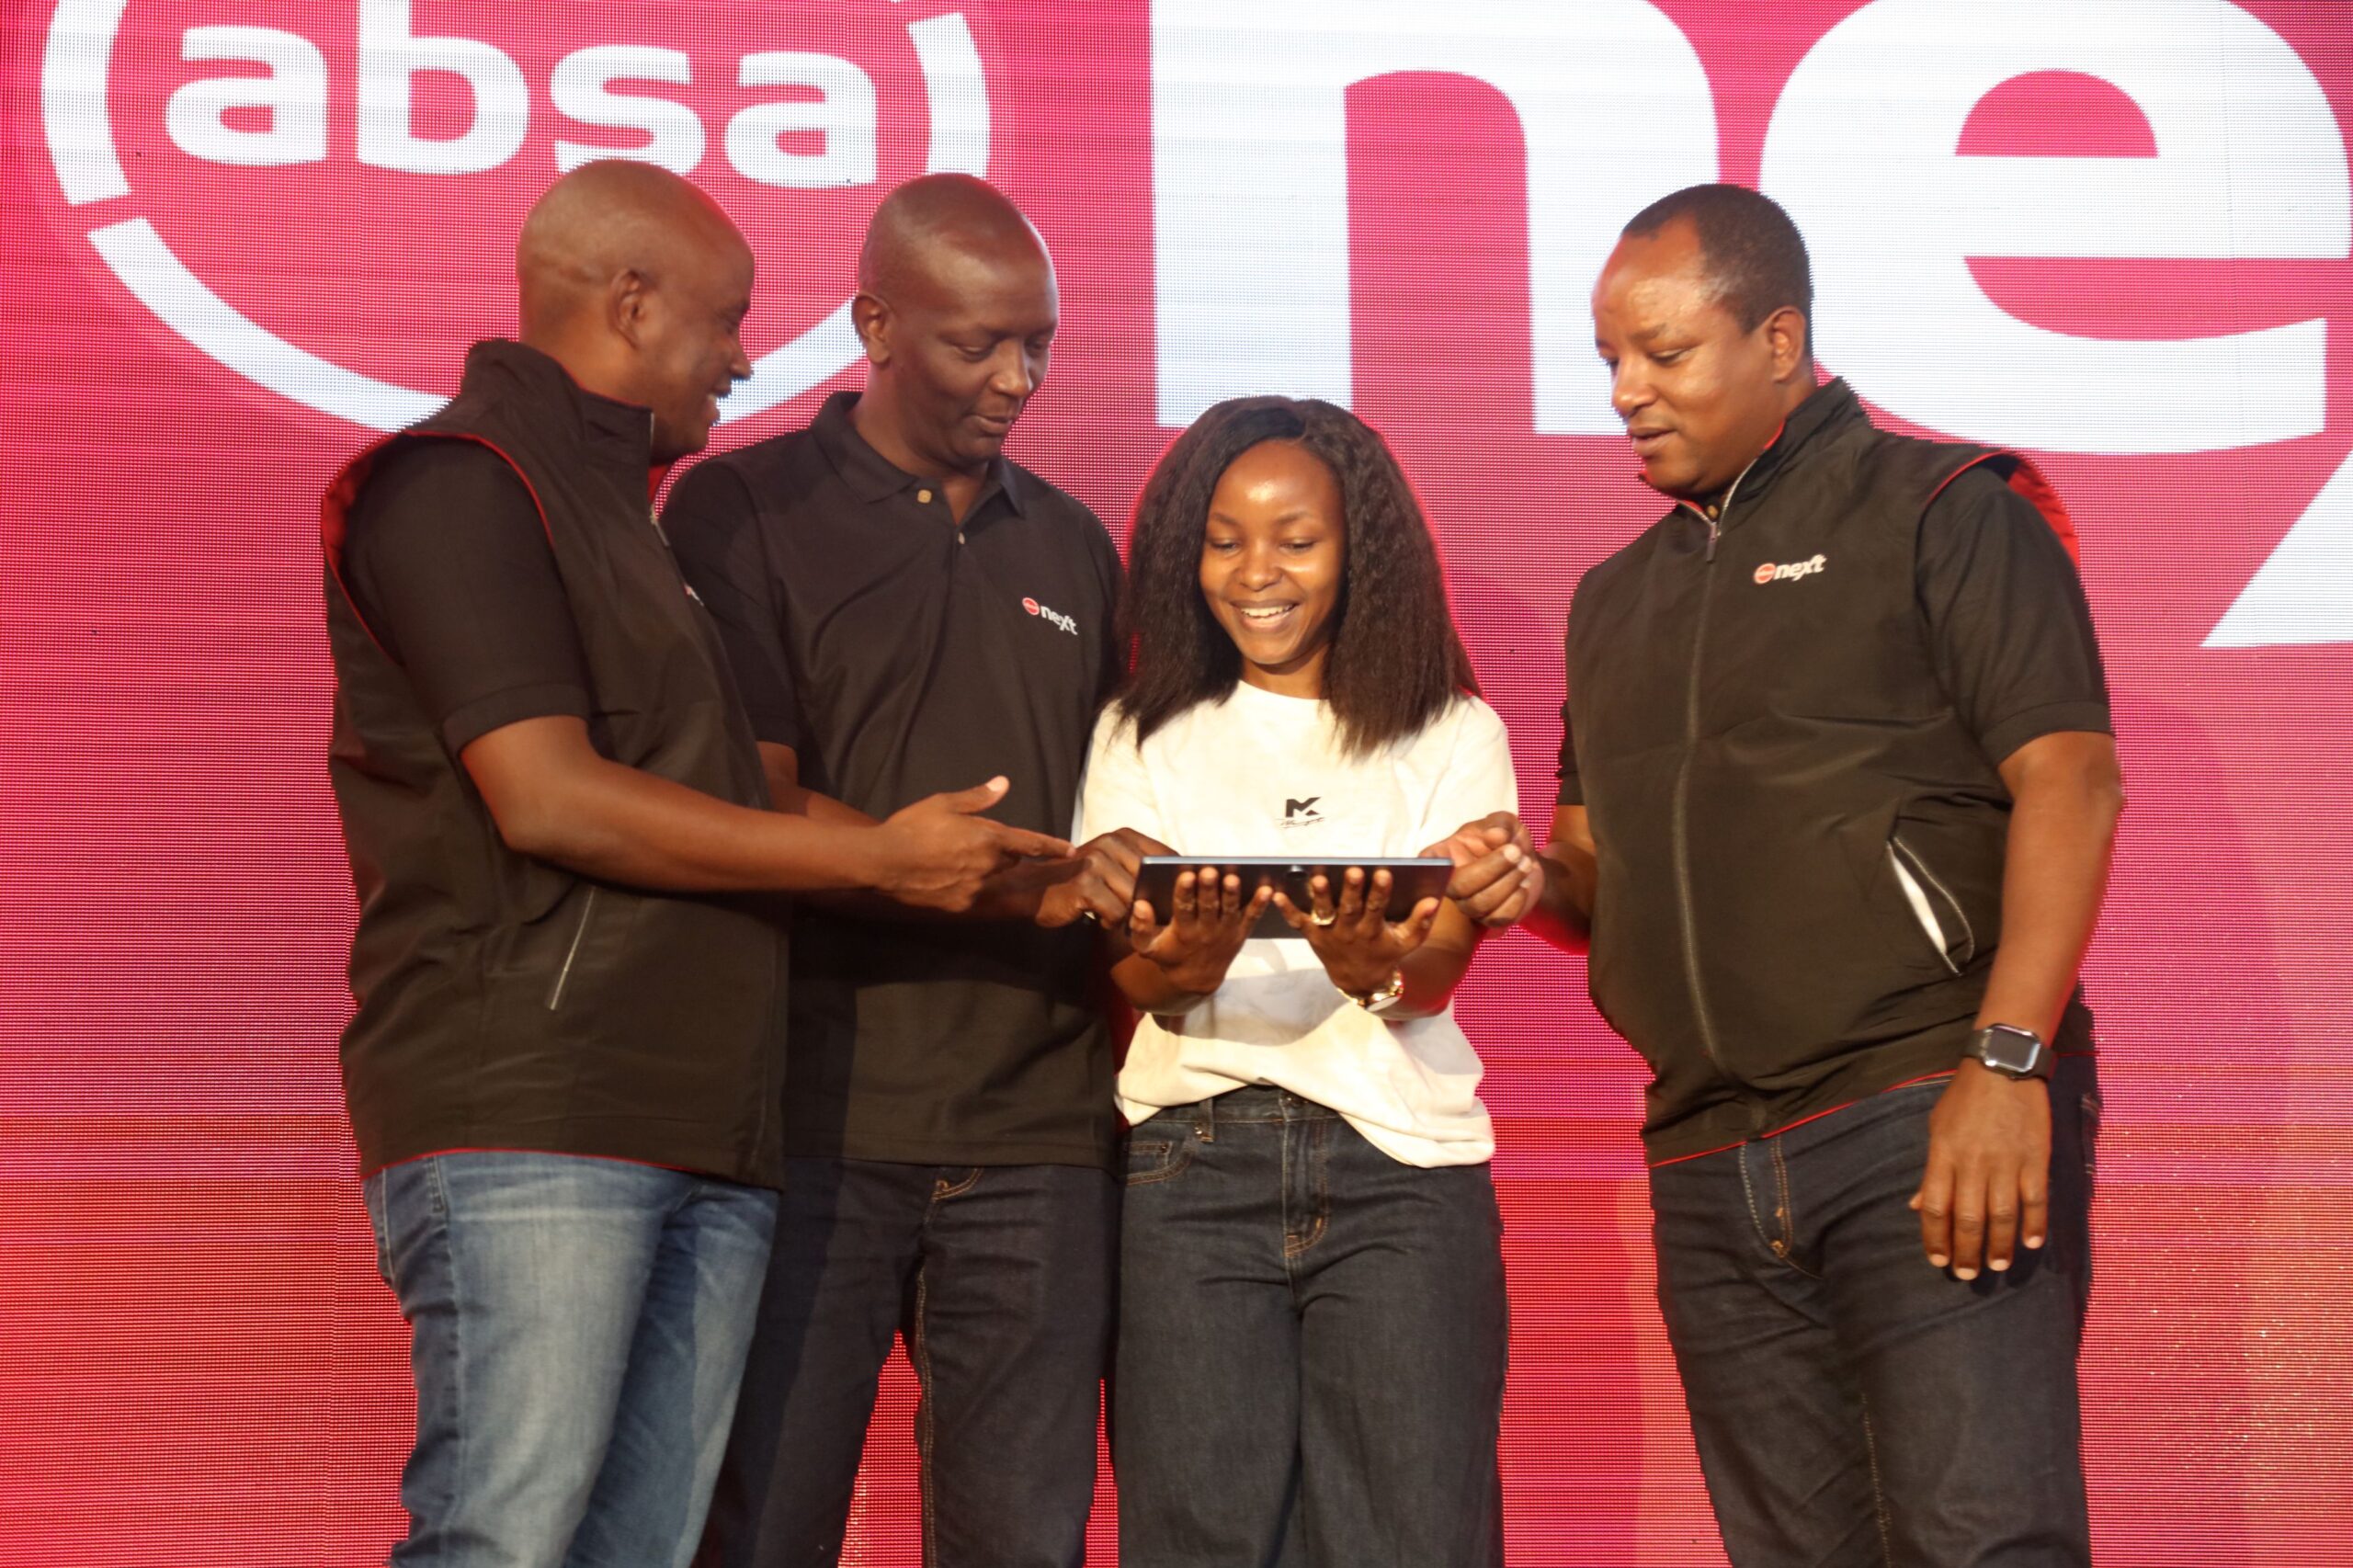
Absa is betting that Kenya’s next bank won’t look like a bank, and to confirm this, Absa Next, it’s neo-banking platform signed up more than 300,000 users in its first weeks of its launch and is letting Absa and non-Absa customers invest from as little as KES 1,000.
Absa Bank Kenya does not have a digital problem. In 2024, 93.6% of its transaction volumes already ran through digital channels, up from 86.5% three years earlier. By 2025, 94% of its transactions went through alternative channels, and its Timiza platform had disbursed KSh25.1 billion in loans in a single year.
So when the bank launched Absa Next in September, the interesting question was not whether customers could bank on their phones. It was why a lender that had already moved most of its business off the branch floor decided to build a second front door.
The answer is a bet about who owns a customer’s financial life. In Kenya, that life is already spread across institutions. Salaries are sent to the bank account, business payments arrive through mobile money, savings sit in a fund, loans come from a digital lender, and purchases go on whichever card is in the wallet. A bank can hold the account and still miss most of the activity around it.
Absa Next is open to people who don’t bank with Absa. It registers customers on a Kenyan national ID alone, links Visa cards from other banks, and says it uses open banking to show accounts held elsewhere. This month it added the last piece of the pitch: investing, from as little as KES 1,000. Saving, borrowing, paying and investing now live in one app, and the bank is wagering that the institution holding the most of someone’s day will matter more than the one holding their salary.
The next phase of the bank
Absa says the idea began about three years ago, when its digital banking team asked what the next phase of the bank should look like. The team concluded it could not answer internally, so it brought customers in. More than 50 customers, entrepreneurs and creators took part in the co-creation process the bank described at the launch.
The result is a separate, cloud-based platform built in Kenya. Absa’s chief operating and digital officer, Julius Camo, said security was built into development from the start. AWS provides the infrastructure and Happiest Minds worked on the application. The bank plans to use the Kenyan build as a template for other Absa Group markets, though it has not said which or when.
The people behind it signal the ambition. Sitoyo Lopokoiyit, who ran M-PESA Africa at Safaricom until February and now leads personal and private banking for Absa Group, said Kenya’s record in financial innovation made it the natural place to build. Yusuf Omari, Absa Bank Kenya’s CEO, called Next more than a digital banking platform when it launched.
The investment is not small, but it is shifting. Absa put KSh3 billion into technology in 2024 and KSh1.16 billion in 2025.
Built around daily use cases
The most distinctive parts of the app are the ones closest to local habits. Users can create chamas, track contributions and manage group goals, and harambee groups offer a looser structure for collective fundraising. Savings goals add game-style challenges. A bill-splitting tool lets friends and family share costs.
The payments menu mirrors the way Kenyans pay: Till Numbers, PayBill and Pochi la Biashara, plus PesaLink transfers to bank accounts and cash withdrawals at any Absa ATM. Person-to-person transfers inside the app are free. Next Coins, a rewards scheme, pay out as cash each month, though Absa has not published what a coin is worth.
Small-business owners get their own track. Renato Duza, Absa’s Business Banking Director, named onboarding, collections, payments and credit as the recurring problems facing small enterprises, and the business wallet is meant to address them. A single view of personal and business accounts reflects a simple reality: the person running the shop is usually also the person running the household.
Save, borrow or invest
Savings earn interest of up to 7%, individually or as a group. The words “up to” matter. Absa has not said what balance or lock-in earns the top rate. At the full 7%, KES 10,000 held for a year would earn KES 700, and after Kenya’s 15% withholding tax on bank interest the customer would keep KES 595.
Credit is the other draw. Personal loans run from KES 500 to KES 1 million, and business loans go up to KES 1 million for working capital. Absa says it uses alternative credit scoring to widen access, but the launch materials gave no interest rate, fee or repayment period. For a product that lends from a few hundred shillings upward, those terms are the number that matters most to customers.
Invest as little as KES 1,000
On November 6, Absa added investing to the app. Customers can open accounts digitally, link existing Absa Unit Trust holdings, create up to three accounts for different goals, top up, view statements and watch portfolios in real time. Five funds are on offer: the Balanced Fund, the Shilling and Dollar Money Market Funds, the Equity Fund and the Fixed Income Fund.
“With investments starting from as little as KES 1,000, we are making wealth creation more accessible and inclusive,” said Moses Muthui, Director, Personal and Private Banking at Absa Bank Kenya.
The bank led with the Equity Fund, which it says returned 15.95% for the year to date. Its own performance table adds context:
| Absa Equity Fund | Return |
| 1 month | -4.13% |
| 3 months | -0.80% |
| Year to date | 15.95% |
The fund started in February 2022. A strong year-to-date figure alongside a weak last month is normal for an equity fund, and it is a reminder that these funds suit people investing for the long term. Absa’s disclaimer says past performance is no guide to the future, unit prices can fall as well as rise, and the right to redeem may be suspended.
For scale, Kenya’s one-year Treasury bill paid 9.04% at the Central Bank’s 24 September auction, and a money market fund mostly holds short-term debt of that kind. Redemptions from the Shilling Money Market Fund that qualify can reach an Absa Wallet in real time; larger amounts go through the customer’s preferred channel.
One app to rule them all
Absa is not alone. KCB’s Vooma, Equity’s digital channels, I&M’s digital lending, Family Bank’s PesaPap, Stanbic’s investment services and the mobile-money platforms are all competing for the same everyday activity. NCBA has run its Loop app since 2017, so Absa’s description of Next as Kenya’s first integrated digital financial solution is the bank’s own claim.
There is also a question inside Absa. It now runs the main Absa app, Timiza and Next. Next and Timiza have separate balances, and Timiza’s goal savings account pays up to 6% a year against up to 7% on Next. Executives say the products will coexist for now while the bank watches how customers use them.
One million customers
Launch numbers are encouraging, but they measure sign-ups, not habits. Reports put Absa’s first-year target at one million customers. The better indicators will be how often people transact, how much money moves through the app, and whether small businesses and investors actually adopt the tools built for them.
TechMoran will test this app and will review loan pricing, group-saving rules, investment fees, among others. For Absa, this is “just the start.” and from the look of the numbers below, Absa Next is set to be a place customers start and spend their day as it has already drawn more than 300,000 users since its September 2026 launch.
The app is allowing customers to invest from as low as KES 1,000. Savings earn up to 7%, individually or in groups. Personal loans range from KES 500 to KES 1 million, and business loans go up to KES 1 million. Absa offers five Absa Unit Trust funds, with up to three investment accounts per customer. Its Equity Fund returned 15.95% for the year to date but fell 4.13% over one month. The app builds on a bank that was already largely digital, since 93.6% of Absa Bank Kenya’s 2024 transaction volumes ran through digital channels.
How to get started
- Download Absa Next from the Google Play Store or the Apple App Store.
- Register with a Kenyan national ID. Passports are not accepted yet.
- Read the loan terms the app shows before you borrow.
- Read each fund’s fact sheet before you invest.