ChamaBox, a Nairobi-based fintech startup founded by David Esabwa Makotsi, is building a digital platform to help Kenya’s savings groups, investment clubs and table-banking associations manage their money, loans and membership without relying on paper records and spreadsheets.
The platform brings together M-Pesa payments, automated financial reconciliation, loan administration, member accounts and group governance tools, targeting a segment of Kenya’s financial economy that continues to depend heavily on informal savings arrangements.
For decades, chamas have provided millions of people with an accessible way to save money, access credit, invest collectively and build financial security. From neighbourhood savings circles and women-led table-banking groups to investment clubs and welfare associations, these informal financial networks have helped members pool resources and pursue economic opportunities.
However, the systems used to manage many of these groups have not always kept pace with their financial activities. Paper ledgers, handwritten counter books, physical cash collections and WhatsApp spreadsheets remain common, creating room for bookkeeping errors, delayed reconciliations, financial disputes and, in some cases, the collapse of groups.
ChamaBox wants to address these challenges by bringing the administration of community financial groups onto a single digital platform.
Taking the Paperwork Out of Collective Finance
The central proposition behind ChamaBox is straightforward: savings groups should not have to depend on manual bookkeeping to manage increasingly sophisticated financial activities.
Many chamas operate revolving funds, collect regular contributions, issue loans to members and distribute dividends. These activities require accurate records, transparent reporting and reliable reconciliation. When information is scattered across notebooks, spreadsheets and mobile money messages, keeping track of a group’s financial position can become difficult.
ChamaBox brings these functions together through a mobile-first digital operating system that allows groups to manage their finances and administration from one platform.
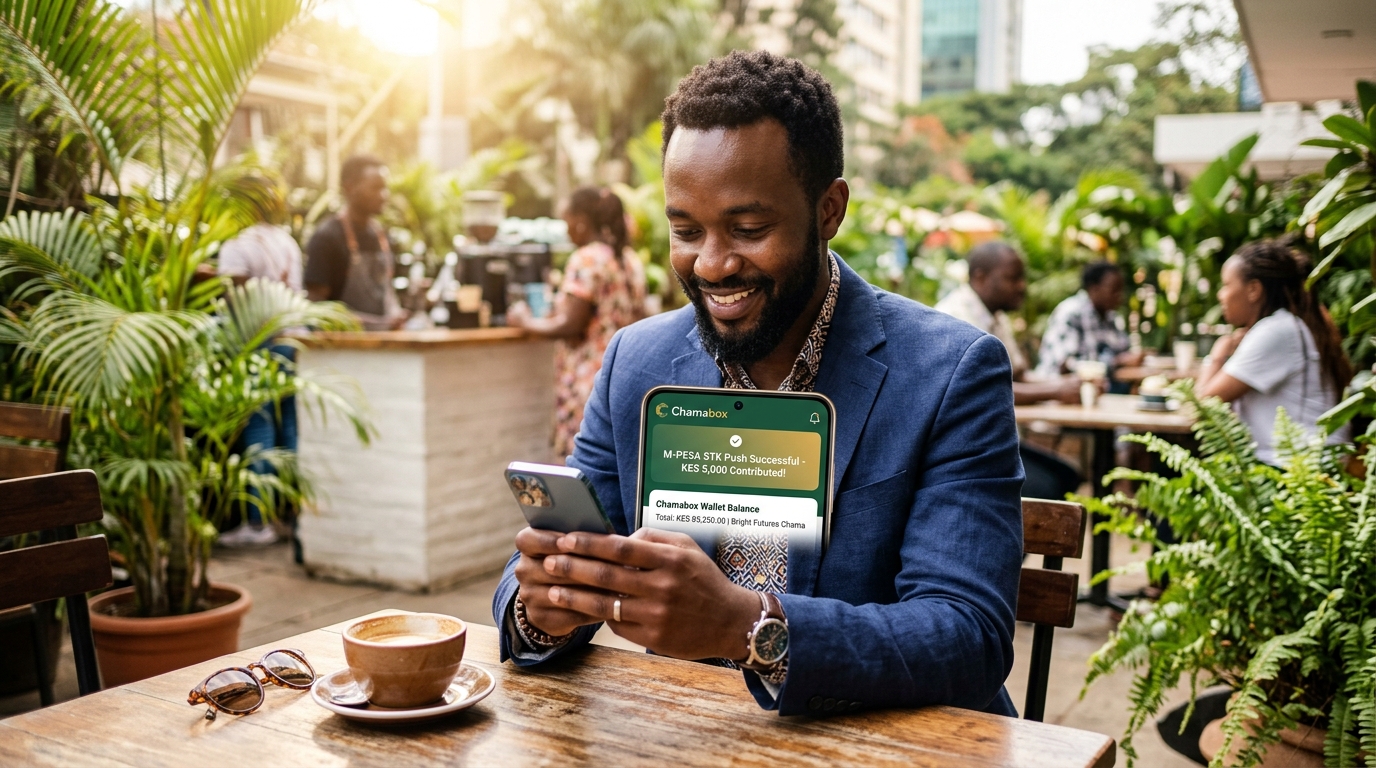
One of its key features is automated M-Pesa reconciliation. Members can make contributions through M-Pesa STK Push or Paybill, with transactions automatically reflected in the group’s digital ledger. This reduces the administrative burden associated with manually recording payments and matching transactions against individual member accounts.
For groups that collect contributions from dozens or hundreds of members, the ability to reconcile payments automatically can simplify financial administration.
The platform also provides loan management capabilities, allowing administrators to configure reducing-balance or flat-rate interest calculations, establish repayment schedules, apply penalties for overdue payments and send automated SMS reminders.
This gives groups a more structured way to administer internal lending while making repayment obligations clearer to members.
Bringing Transparency to Chama Finances
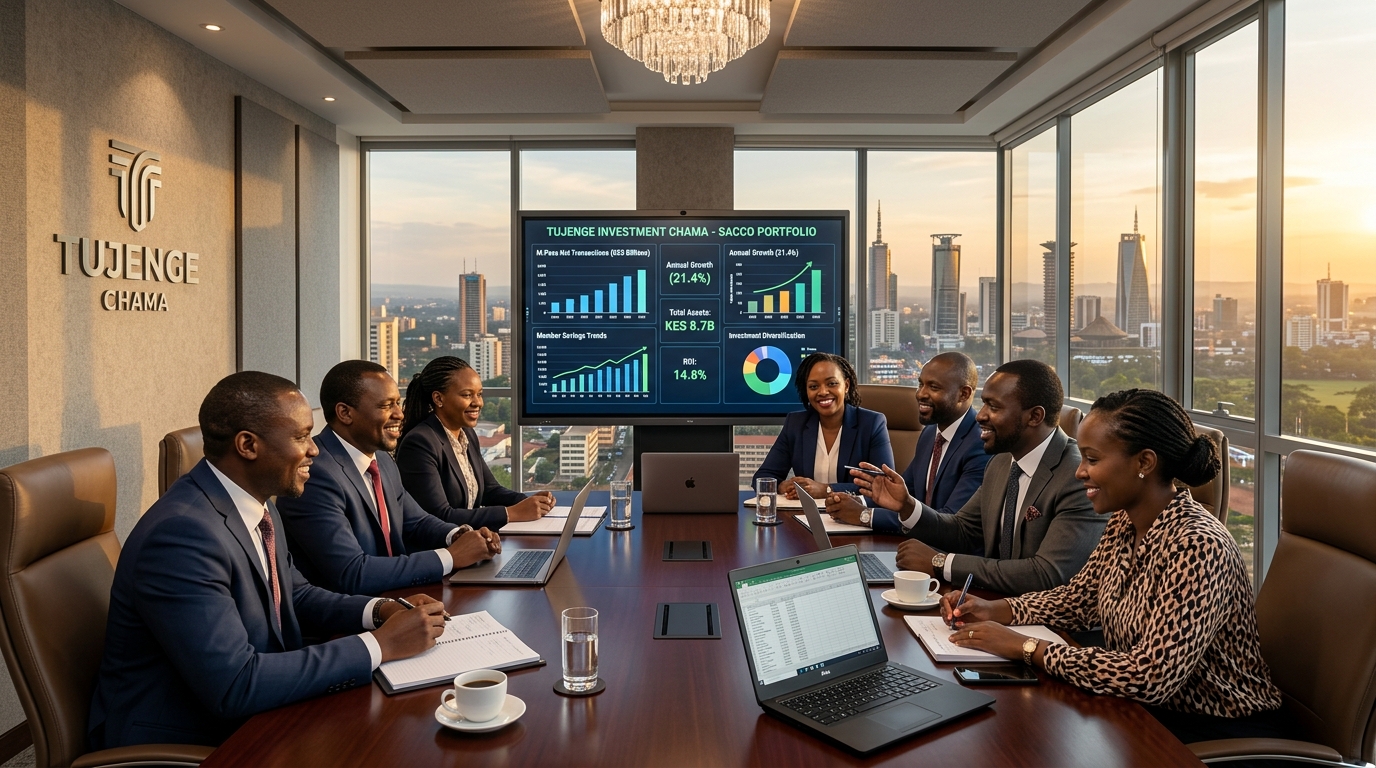
Financial transparency is particularly important in collective savings arrangements, where members entrust their money to elected officials, treasurers and group administrators.
Disagreements over contributions, outstanding loans, withdrawals and dividend calculations can undermine confidence and threaten the survival of otherwise successful groups.
ChamaBox addresses this through individual member portals that provide access to group cash balances, personal equity positions and loan repayment records.
Rather than depending entirely on periodic reports from group officials, members can inspect their financial positions through their mobile devices.
The platform also incorporates governance and welfare administration tools, including multi-signatory withdrawal approval workflows, dividend distribution calculations and archived meeting minutes.
These functions extend ChamaBox beyond a conventional bookkeeping application. The company is attempting to digitise the administrative structures that allow community financial organisations to operate, make decisions and maintain accountability.
A Growing Market With Established Competitors
ChamaBox is entering a Kenyan market where several technology companies have already recognised the opportunity to digitise savings groups and investment clubs. Its proposition is therefore not without competition, and the company will need to demonstrate why groups should choose its platform over existing alternatives.
One of the established names is Chamasoft, a cloud-based platform designed for investment groups. It provides contribution tracking, financial administration, investment management, group communications and reporting. Its pricing model includes free and paid subscription options, targeting groups that want to move away from manual financial administration.
Another competitor is ChamaPay, which offers automated savings and loan management, M-Pesa integration, member portals, dividend calculations, investment tracking and financial reporting. The company says it serves more than 500 savings groups, although its customer and transaction figures are company-reported.
Chama is another platform targeting East African savings groups. It supports pooled savings, merry-go-round arrangements, loan management, payouts and group decisions, positioning itself as a digital alternative to traditional savings group administration.
ChamaGRID is also developing digital infrastructure for Kenyan savings groups, covering contributions, merry-go-round payouts, welfare funds and governance. Its platform advertises M-Pesa integration and multi-signatory approval processes.
Other alternatives include eChama, which provides contribution tracking, loan management, meeting coordination, member administration and financial analytics.
Calpex ChamaManager, developed by Calpex Technologies, targets Kenyan savings groups with contribution tracking, loan administration, merry-go-round management, share registries, welfare funds and member statements.
Meanwhile, POSHUB Chama combines savings and loan administration with welfare management, expenses and accounting. Its offering also targets investment clubs, community organisations and groups with multiple chapters.
The growing number of platforms demonstrates that digitising chamas is becoming a recognised software opportunity in Kenya.
For ChamaBox, this presents both an opportunity and a challenge. Automated M-Pesa reconciliation, loan management and member portals are no longer unique selling points in this market. Several competitors already advertise similar capabilities.
Its competitive position will therefore depend on how well it integrates these functions, the reliability of its financial records, the simplicity of its user experience, customer support and its ability to accommodate different group structures.
The company could also distinguish itself through its approach to multi-signatory withdrawal approvals, transparent dividend distribution and the integration of financial management with group governance. However, these capabilities will need to translate into measurable advantages for customers.
Ultimately, the market will reward platforms that can win the trust of group officials and members, demonstrate consistent transaction accuracy and retain customers as their savings organisations grow.
Building From Nairobi
Headquartered in Nairobi, ChamaBox describes itself as a bootstrapped, revenue-generating startup with less than US$2 million in external capital raised and fewer than four years of operations.
The company says its live platform is already serving community groups and savings chapters across Nairobi, Western Kenya and the Coast region.
Its focus on active revolving funds suggests an ambition to serve groups with ongoing financial operations rather than simply provide digital membership registers or basic savings trackers.
For founder David Esabwa Makotsi, the opportunity lies in providing community-based financial organisations with the digital tools needed to manage money more transparently and efficiently.
The challenge ahead will be scaling adoption across a fragmented market with different group structures, contribution arrangements, governance practices and levels of digital literacy.
ChamaBox will also need to demonstrate that its platform can maintain reliability and trust as transaction volumes and the number of participating groups increase.
Its longer-term opportunity is to become an essential operating layer for community savings and investment organisations, potentially extending its reach across East Africa.
A Fintech Opportunity Beyond Conventional Banking
ChamaBox’s proposition speaks to a broader opportunity in African financial technology: building infrastructure around the financial practices that people already use.
Much of the continent’s fintech investment has focused on digital payments, mobile wallets, lending, remittances and merchant services. Yet informal savings groups remain important financial institutions for communities that may not always find conventional financial products suited to their needs.
Chamas provide a mechanism for disciplined savings, emergency borrowing, investment and social support. Their collective nature also creates an opportunity for technology companies to provide tools that improve financial visibility and operational efficiency.
By focusing on these groups, ChamaBox is targeting a market where digital adoption could address practical challenges without requiring members to abandon familiar savings arrangements.
Its M-Pesa integration is particularly relevant in Kenya, where mobile money has become central to everyday financial transactions. Connecting contributions directly to group records creates a bridge between established mobile payment infrastructure and the internal financial management of savings organisations.
The opportunity, however, extends beyond digitising contributions. A successful platform must also earn the confidence of group officials and members, demonstrate the accuracy of its financial records and provide reliable support as groups grow and their operations become more complex.
If it can continue to build trust, expand its group network and demonstrate sustainable growth, ChamaBox could help move an important part of East Africa’s informal financial economy from paper-based administration to digital financial management.