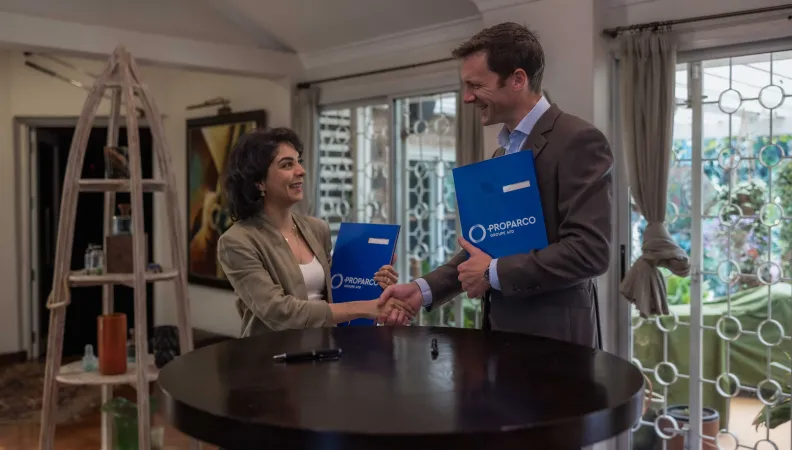
French development finance institution Proparco has invested €600,000 (approximately $690,000) in Sudanese fintech Cashi, marking its first investment in the war-torn country as demand for digital financial services grows amid widespread banking disruptions and economic instability.
The investment will support Cashi’s expansion of digital payments infrastructure in Sudan, where prolonged conflict has disrupted banking operations, restricted access to cash and damaged telecommunications networks, leaving millions of people struggling to conduct everyday financial transactions.
Founded in 2022, Cashi operates a digital payments ecosystem that allows consumers and businesses to deposit and withdraw money, transfer funds and settle bills through a network of local merchants. Its digital wallet, MyCashi, has attracted 2.2 million registered users, making the company an increasingly important player in Sudan’s financial technology market.
The funding represents a relatively small financial commitment for Proparco, the private-sector financing arm of the French Development Agency Group, but marks a significant expansion of its investment activities into one of Africa’s most challenging operating environments.
Sudan’s civil war, which erupted in April 2023, has devastated the country’s economy, displaced millions of people and severely weakened the infrastructure supporting commercial activity. Banks have faced closures and operational disruptions, while shortages of physical currency have complicated transactions for households and businesses.
Against that backdrop, fintech companies capable of operating outside conventional banking networks have become increasingly important to maintaining economic activity and facilitating humanitarian assistance.
Cashi has developed payment technologies designed to function in areas with unreliable internet connectivity, including USSD and SMS-based services, offline-use cards and devices that do not require smartphone applications.
The approach allows customers to conduct transactions even when access to mobile data or traditional banking services is limited, addressing one of the biggest obstacles to financial inclusion in conflict-affected markets.
The company’s origins are linked to alsoug.com, one of Sudan’s leading online commerce platforms. Cashi was established to address the payment infrastructure limitations encountered in the country’s digital commerce market, building a financial services network intended to serve consumers and merchants beyond the reach of traditional banks.
Its expansion also highlights the growing importance of alternative financial infrastructure in African markets where banking penetration remains limited and physical infrastructure is vulnerable to economic or political shocks.
“Today in Sudan, being able to send, receive, or withdraw money can determine how a family makes it to the end of the month, or whether a small business can stay open,” said Nina Saeed, General Manager of Cashi.
“When banks were inaccessible during the war, Cashi continued to operate and remain available. We designed it to continue working when cash runs out and the network is disrupted.”
Saeed said millions of Sudanese consumers and merchants already use the company’s services, while many others remain excluded from formal financial infrastructure.
“Where you live shouldn’t determine whether you can receive a payment, settle a bill, or send money to your family,” she said.
For Proparco, the investment underscores a willingness to finance private-sector businesses operating in fragile economies, where conventional commercial investors often face heightened security, regulatory and operational risks.
The institution has increasingly positioned financial inclusion and entrepreneurship as priorities in its African investment strategy, supporting businesses that provide essential services to underserved populations.
“In fragile contexts like Sudan, access to reliable financial services is not only a driver of economic development but also a crucial means of preserving livelihoods and building resilience,” said William Barbarossa, Director of Investments at Proparco.
“This first operation in Sudan demonstrates our commitment to supporting entrepreneurship and financial inclusion, even in the most challenging environments.”
Beyond consumer payments, Cashi’s infrastructure is designed to facilitate the distribution of humanitarian assistance, particularly to displaced populations and communities where banking facilities and telecommunications networks have been damaged or remain inaccessible.
Digital payment platforms can provide an alternative to physically distributing cash, although their effectiveness still depends on functioning merchant networks, liquidity and sufficient communications infrastructure.
The investment also reflects a broader shift in African fintech financing toward companies addressing infrastructure gaps rather than focusing exclusively on consumer convenience in established banking markets.
While much of the continent’s fintech investment has historically concentrated in larger economies such as Nigeria, Kenya, Egypt and South Africa, companies operating in smaller or conflict-affected markets are attracting development finance institutions seeking both financial sustainability and measurable social impact.
For Cashi, the immediate challenge will be expanding its services while navigating Sudan’s uncertain security environment, damaged infrastructure and persistent shortages of cash.
Proparco did not disclose the equity stake acquired, Cashi’s valuation or whether the investment formed part of a larger funding round.
The financing nevertheless gives Cashi additional backing to strengthen its payment infrastructure and extend financial services to communities that remain largely excluded from the formal banking system.
In a country where access to money has become increasingly intertwined with the ability to survive economic disruption, Cashi is betting that financial technology built for unreliable infrastructure can become an essential service rather than merely an alternative to conventional banking.
 in Sudanese fintech Cashi)