JentaHub is a verified talent marketplace that connects businesses around the world with verified African professionals. The firm’s mission is to give qualified African professionals greater access to international opportunities offered by global businesses, clients, and NGOs.
JentaHub says despite the existence of platforms like Upwork, Toptal, and Fiverr for many years, unemployment among qualified African professionals continues to rise, showing that the unique challenges Africans face in accessing global work opportunities still need better solutions and this is exactly where JentaHub comes in..
Apart from freelance services, JentaHub includes Jenta-Gigs, a dedicated microtask platform that provides professionals with additional earning opportunities through trusted global partners such as CPX Research, BitLabs, AdGate Media, and others.
TechMoran caught up with JentaHub founder and CEO Joseph Ongachi on how the verified talent marketplace aims give qualified African professionals greater access to international opportunities.
Why did you start Jentahub?
I founded JentaHub in 2026 after recognizing the challenges many qualified African professionals continue to face on existing freelancing platforms, particularly when it comes to accessing meaningful international work despite having valuable skills, qualifications, and experience.
As the founder and CEO, I oversee product development, technology, and the overall direction of the business while continuously improving the platform based on user feedback, industry research, and the evolving needs of both professionals and businesses.
What gap in the market did you spot?
We identified a clear gap between Africa’s growing pool of qualified professionals and the global demand for skilled talent. While many freelancing platforms provide access to online work, they have not adequately addressed the barriers that continue to limit African professionals from fully participating in the global digital economy. At the same time, businesses continue to face trust challenges when hiring remotely, making verification more important than ever.
Our competitors include Upwork, Fiverr, Freelancer.com, and Toptal. JentaHub differentiates itself by focusing specifically on verified African professionals through identity, academic qualification, and skills verification, while creating multiple earning opportunities through both freelancing and Jenta-Gigs. Our goal is not simply to compete with existing platforms, but to solve the specific challenges that continue to affect qualified African professionals.
You have investors or boostrapping?
JentaHub is currently bootstrapped and has been entirely self-funded from the beginning. This has allowed us to remain focused on building the platform around the real needs of professionals and businesses rather than external pressures.
Our biggest milestone so far has been successfully launching the platform, onboarding our first users, integrating leading global earning partners through Jenta-Gigs, and establishing the foundation for strategic partnerships that will accelerate future growth.
What has uptake been like?
JentaHub is in its early launch stage and has started onboarding its first users while actively gathering feedback to improve the platform. The growth rate has been encouraging and reinforces our belief that we are solving a genuine problem in the online hiring space, where many professionals remain underserved and businesses continue to struggle with trust when hiring remotely.
Our current focus is on growing our community of verified professionals, strengthening partnerships with international businesses and organizations, and continuously improving the platform to deliver a world-class hiring experience.
What markets are you operating in currently?
While we are based in Kenya, our primary focus is Africa, where we identify, verify, and onboard qualified professionals across multiple industries. Most of our professional community is African, the businesses, clients, and organizations we serve are global. Our objective is to bridge the gap between Africa’s highly skilled workforce and international opportunities that have traditionally been difficult for many professionals to access.
As we continue to grow, we plan to expand into more African countries while increasing our presence in international markets by attracting more global businesses and organizations to hire through JentaHub. Our long-term vision is to become the leading gateway connecting verified African professionals with opportunities around the world.
What is your business model?
JentaHub generates revenue through service fees charged as a percentage of professionals’ earnings on completed freelance projects, commissions generated through Jenta-Gigs, and premium tools and hiring features offered to businesses seeking a more advanced recruitment experience.
As an early-stage startup, our primary focus is building a sustainable platform, expanding our user base, and delivering long-term value. Revenue generation is growing alongside the platform as we continue to onboard both professionals and businesses.
Any chalenges so far?
One of the biggest challenges has been building trust as a new platform while competing against well-established global marketplaces that have operated for many years. Convincing both professionals and businesses to embrace a new platform requires consistently demonstrating credibility, security, and quality at every stage of the user experience.
Because of that we have put a strong emphasis on trust through identity verification, strict academic qualification verification, and skills verification, ensuring the professionals we connect to global opportunities are backed by verified credentials rather than just claims, while supporting every project with secure payments and built-in collaboration tools.
Another major challenge has been developing the infrastructure required to support international payments, strict verification processes, secure project collaboration, and global earning partnerships while remaining completely bootstrapped. Although these challenges have required significant investment of time and resources, they have also shaped the strong foundation on which JentaHub is being built.
TryMassive AI has launched in Kenya with a platform aimed at helping restaurants, salons, pharmacies, retailers and other small businesses gain visibility in Google Search and Maps as consumers increasingly turn to online and AI-powered tools to find local services.
Founded by software developer Segun Olaiya, TryMassive AI is targeting a problem faced by businesses that depend on customers within a relatively small geographic area: being open for business does not necessarily mean being visible when potential customers search nearby.
A consumer looking for a restaurant, pharmacy or salon may see only a small number of businesses prominently displayed on Google Maps. TryMassive AI is designed to help businesses improve their position in those results through profile optimization, local search tracking, review management and competitor analysis.
The company is also extending its focus beyond Google by building tools intended to make business information easier for artificial-intelligence systems and voice assistants to interpret when consumers ask for local recommendations which has become a new battleground for small businesses as AI assistants become increasingly popular intermediaries and search tools.
TryMassive AI’s software starts with a local visibility scan, mapping where a business appears for searches conducted across its surrounding area. It identifies competitors ranking higher and highlights gaps in the business’s online presence.
The company then works on the business’s Google Business Profile, including categories, operating hours, services, contact information and photographs. It also provides ongoing management, including posts, service updates and responses to customer reviews.
The platform tracks changes in local rankings over time and provides businesses with reports covering measures such as calls, direction requests and search visibility.
TryMassive AI says it is designed as a managed service, allowing business owners to use the platform without having to run their own search-engine-optimization campaigns.
“Your local reputation is your most valuable asset,” Olaiya said. “If you run a great business in Kenya, you deserve to be the first option people see when they search on their phones.”
The company’s initial focus is on sectors where proximity can directly influence purchasing decisions, including restaurants and cafes, beauty businesses, pharmacies, clinics, retail outlets and home-service providers.
For these businesses, the economics of local search can be significant. A customer searching for “restaurant near me” or “pharmacy open now” is typically closer to a purchasing decision than someone conducting a general search about a product or service.
TryMassive AI is entering a market that includes established search-marketing agencies and software providers, but is positioning itself around an automated, managed approach targeted at small and medium-sized businesses.
Olaiya has previously worked as a software developer for companies including MailerLite, Xtremepush and SOCi and his experience is key in helping businesses in Kenya to bolster their visitbilty through a free local-search visibility audit via TryMassive.AI. TryMassive aims to provide Google Business Profile optimization, map-rank tracking, review management, keyword research, competitor analysis and services aimed at improving visibility in AI-powered search. The company plans to expand its local-search offering across Africa.
Glovo, an on-demand delivery platform owned by Uber, has partnered with e-mobility company eBee to onboard more women on the platform on its platform in Kenya from 1% to 5% over the next year.
Glovo works with more than 2,500 active couriers daily in Kenya, the initiative dubbed ‘She Delivers’, will deliver practical rider training through eBee before participants join the Glovo platform, with the initial cohort bringing together 16 women.
According to Liz Wambua, Head of Operations, Glovo Kenya, “‘She Delivers’ is a core business strategy to build a more inclusive, resilient, and sustainable logistics ecosystem. By pairing eBee’s clean mobility technology with Glovo’s platform reach, we are creating a scalable model for women to build independent incomes while setting a new benchmark for gender parity in urban last-mile delivery across the region.”
While Kenya’s digital and gig economies have created new earning opportunities, participation has not been equal. For women considering delivery work, barriers range from limited riding experience and vehicle access costs to safety concerns and social bias surrounding traditionally male-dominated mobility jobs.
Through the partnership, eBee will provide structured training covering e-bike handling, defensive road safety, basic maintenance, navigation, and delivery-platform readiness, helping participants build the practical skills and confidence required to operate independently as couriers.
“Electric bicycles remove heavy physical exertion and lower operating expenses, making last-mile delivery a genuinely viable, high-earning opportunity for women,” said Maarten Fonteijn, Managing Director eBee Africa. “Partnering with Glovo allows us to advance gender equity while accelerating the shift toward clean, zero-emission urban transport.”
Participants will operate electric bicycles, adding a strong sustainability dimension to the programme as Kenya’s last-mile delivery sector transitions toward cleaner and more affordable forms of urban mobility.
“Access to e-bikes and structured safety training removes the biggest hurdle to joining this sector,” said Yvonne Muribi, a rider from the initial cohort. “It gives us the confidence to navigate traffic safely and build an independent income on our own terms.”
Glovo and eBee are establishing a blueprint for gender-inclusive, zero-emission last-mile logistics in East Africa. By turning real-world pilot insights into optimized asset financing, safety infrastructure, and targeted onboarding channels, the partnership lays a scalable foundation to reach the 5% female representation target, proving that sustainable mobility and economic equity go hand-in-hand.
Kenya’s WapiPay is expanding its network into the Caribbean through a partnership with Jamaica’s JN Money Services, opening a new payment corridor linking Jamaica with markets in Africa and Asia, months after it announced entry into the market.
The agreement, announced after WapiPay received regulatory approval from the Bank of Jamaica, will allow customers using WapiPay to send money to Jamaica for cash collection at JN Money locations or direct deposits into local bank accounts.
The move gives WapiPay access to JN Money’s established payout infrastructure while extending the Kenyan fintech’s reach beyond its core Africa-Asia business. JN Money operates an international remittance network spanning 18 countries, according to its parent company, Jamaica National Group.
For WapiPay, Jamaica represents an entry point into the Caribbean and another step in its effort to build payment infrastructure across emerging markets rather than operate individual remittance corridors in isolation.
WapiPay was founded in 2019 by brothers Edward and Paul Ndichu and initially focused on payments between Africa and Asia, particularly transactions involving African businesses paying suppliers in Asia. The company has since expanded its network across Africa, Asia, the UK, the US and the Caribbean.
The Jamaica partnership also broadens the potential use of the platform beyond consumer remittances. The companies said the arrangement will support both person-to-person transfers and business-to-business payments, including trade-related transactions.
That distinction is important for fintechs competing in the increasingly crowded cross-border payments market. Remittances provide a large and recurring transaction base, while business payments can generate larger transaction values and create deeper relationships with merchants and companies.
Under the arrangement, WapiPay customers will be able to send funds to Jamaica for cash pickup through JN Money or have money deposited into recipients’ local bank accounts. WapiPay said it is targeting completion of transfers in less than 30 seconds on supported transactions and will not charge a fee on its side for the service.
The partnership comes as remittance companies compete on speed, foreign-exchange transparency and distribution rather than simply the ability to move money between countries.
JN Money said the partnership will also expand the international corridors available to Jamaicans, particularly as digital-first providers seek to connect Caribbean consumers with newer sources of migration, trade and financial flows.
For WapiPay, the move fits into a broader expansion strategy. The company has recently added regulated markets and services to its network, including a Canadian Money Services Business license that allows it to provide foreign-exchange, money-transfer and payment services in Canada. The license also covers virtual-currency and digital-asset transactions.
The company has also been building products around remittance data. Earlier this year, it introduced a remittance-based credit-scoring tool designed to help financial institutions assess borrowers using patterns in their international money transfers.
Jamaica’s importance to the strategy comes from the scale of its remittance economy. The country is one of the Caribbean’s major recipients of money sent home by citizens living overseas, making access to reliable international payout infrastructure commercially significant for payment providers.
JN Money will serve as the local payout conduit under the new arrangement, allowing WapiPay to use an existing network rather than build a physical cash-distribution infrastructure in Jamaica from scratch.
The partnership effectively creates a three-region payment link: WapiPay brings its network across Africa and Asia, while JN Money provides the local Jamaican infrastructure. The companies say the arrangement could eventually connect Jamaican customers more efficiently with Africa, Asia, North America and Europe.
For African fintechs, such corridors are becoming increasingly important as companies look beyond domestic mobile-money markets and compete to capture a larger share of international payments.
WapiPay’s Jamaica expansion is therefore less about adding another destination to a remittance app than about building a broader network through which money can move between emerging-market economies with fewer intermediaries.
The company is positioning the network around consumer remittances, trade payments and business disbursements, giving it multiple potential sources of transaction volume as it expands into new regulated markets.
With Jamaica now added to its international footprint, WapiPay is betting that the next stage of African fintech growth will involve connecting the continent not only to traditional financial centers, but also directly to other high-volume emerging markets.
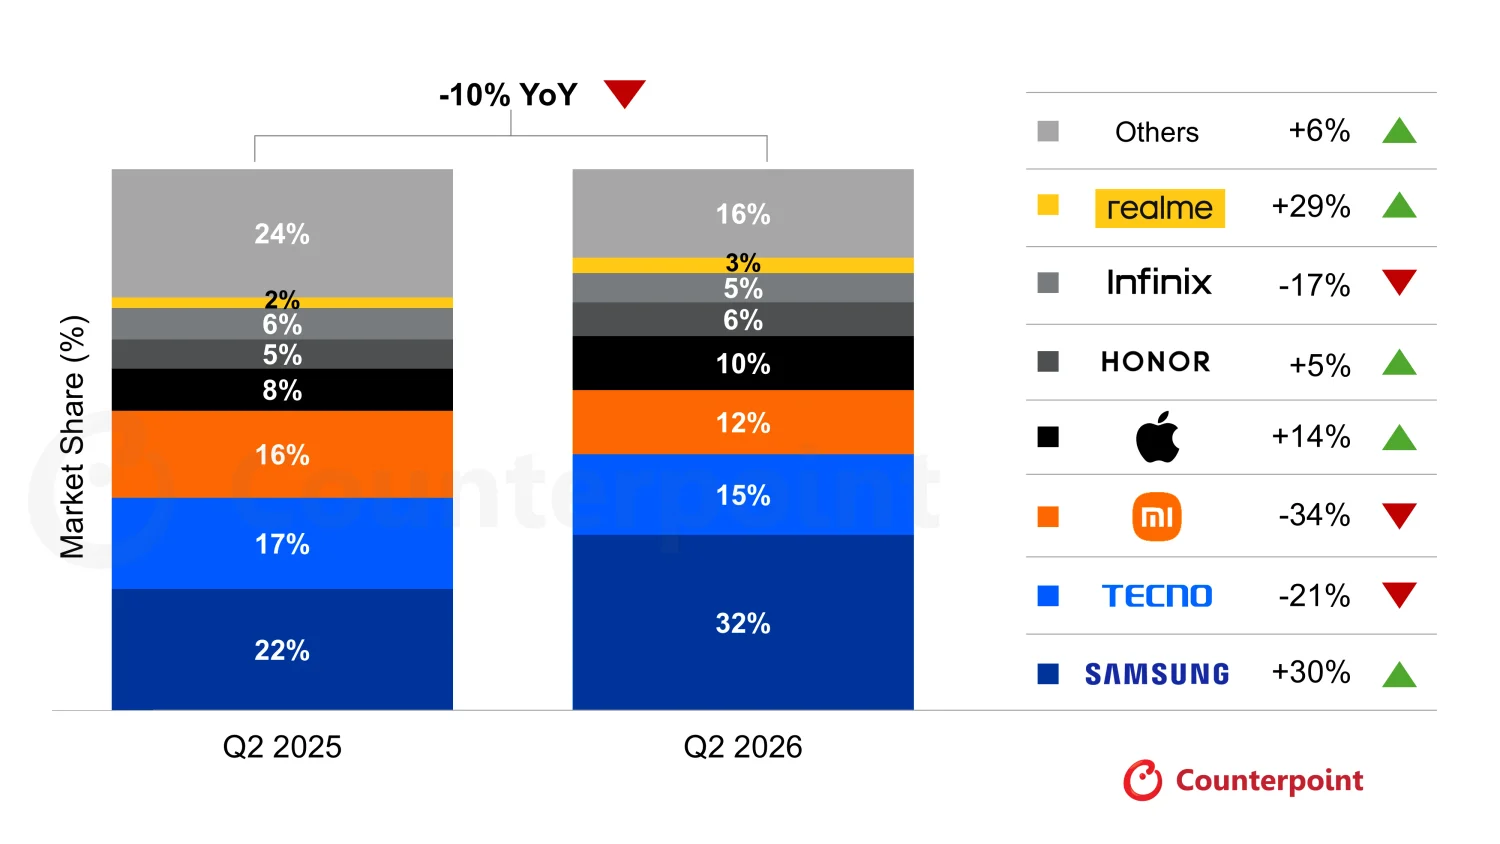
In addtion to the two Dangote group IPOs this year, two Chinese tech firms with predominantly African operating businesses are seeking to list on the Stock Exchange of Hong Kong (ESHK). Transsion, whose Tecno, Infinix, and itel phones are market leaders across Africa, has cleared the regulatory hurdle for an ESHK listing. Separately, its sister company, PalmPay, a fintech firm operating in Nigeria with backing from Transsion and China’s NetEase, is seeking about $200 million ahead of a potential listing on the ESHK, with a prospective valuation of one billion dollars. Hong Kong gives these companies access to international investors and deeper capital markets exposure whilst keeping them close to their Chinese ownership base.
PalmPay’s rival, Opay, another Nigerian payment service provider headquartered in Lagos and Singapore, with operations in Nigeria, Egypt, Pakistan and Indonesia, also plans to go public in the United States, targeting a $4 billion valuation. Airtel Money, another leading African fintech with operations in 14 African markets, had earlier announced plans for a London IPO, with a $10 billion valuation target. Finally, MNT-Halan, an Egyptian fintech, is also eyeing a listing on the Egyptian Stock Exchange at a billion dollar valuation. These African IPOs slated for 2026 are well ahead of their global compatriots, a significant development and a test of whether global investors see the continent as a source of scalable growth ventures.
Earlier in the year, OpenAI, SpaceX, Anthropic, Discord, Kraken and others were listed as potential IPO candidates for 2026. But so far, only SpaceX has gone public with Anthropic expected to close the year, whiles OpenAI is now aiming for 2027. According to Emily Zheng, Senior Research Analyst at PitchBook, “IPOs are generally suffering from continued uncertainty from multiple wars, rising energy prices, and AI’s draining of moats around business models across industries has made the market too volatile to instill confidence in the next cohort of VC-backed IPO candidates.” She argues that, “the IPO pipeline is expected to remain thin in the coming years with a more selective cohort of IPO candidates: companies that stayed private longer, are bigger at the time of listing, and go public for a specific reason tied to their growth story. This is the new normal.”
Continental Holdings PLC became the 17th company to list on the Malawi Stock Exchange (MSE) on August 10th. More than ten thousand investors subscribed to shares in the Initial Public Offering (IPO) which covered 753.3 million shares priced at 195 kwacha each. It was 93% subscribed raising approximately K135.4 billion, making it the largest IPO in Malawi’s capital market history. The stock went up more than 75% on its first day of trading, rising from 195 to 342 kwacha.
However, the African companies that are listing on the internantional exchanges have raised concerns in some African markets over why they are not listing on the local exchanges where they generated their value, or not considering a secondary listing so that locals can share in the wealth that is created. At a meeting with the President of Nigeria, the CEO of Nigeria Exchange Group (NGX Group), Temi Popoola, advocated for policy and legal measures that could encourage major companies with substantial Nigerian operations to pursue dual listings (local and international).
The Dangote Group is leading by example. The group’s cement business which is currently listed on the NGX announced plans for a secondary listing on the London Stock Exchange. The group’s subsidiary Dangote Refinery also seeks to list a 5% to 10% minority stake on the Nigeria Stock Exchange (NGX) with a dual listing on other African exchanges. The company initiated talks in 2nd quarter 2026 with African stock market leaders on building a pan-African listing framework, potentially using depositary receipts rather than direct dual listings with six African exchanges, including those in Ghana, Kenya, South Africa and the regional BRVM.
Dangote Refinery’s pursuit of an IPO comes amid the expansion of its 650,000-barrel per day plant, which has become the main domestic supplier of refined fuels to the Nigerian market, as well as exporting jet fuel to Europe. The company has secured $1 billion in an underwriting program from two firms. The amount consists of a $600 million participation in the refinery’s $2.5 billion private placement and a new $400 million commitment that will go into effect when the IPO launches in October 2026. The refinery’s CEO, David Bird said “an international listing possibly in London is at least three years away, pending a longer track record of financial performance”.
Hopefully Dangote’s example of dual listing that allows both local and international investors to participate in the wealth created is pursued by the new entrants into the market.
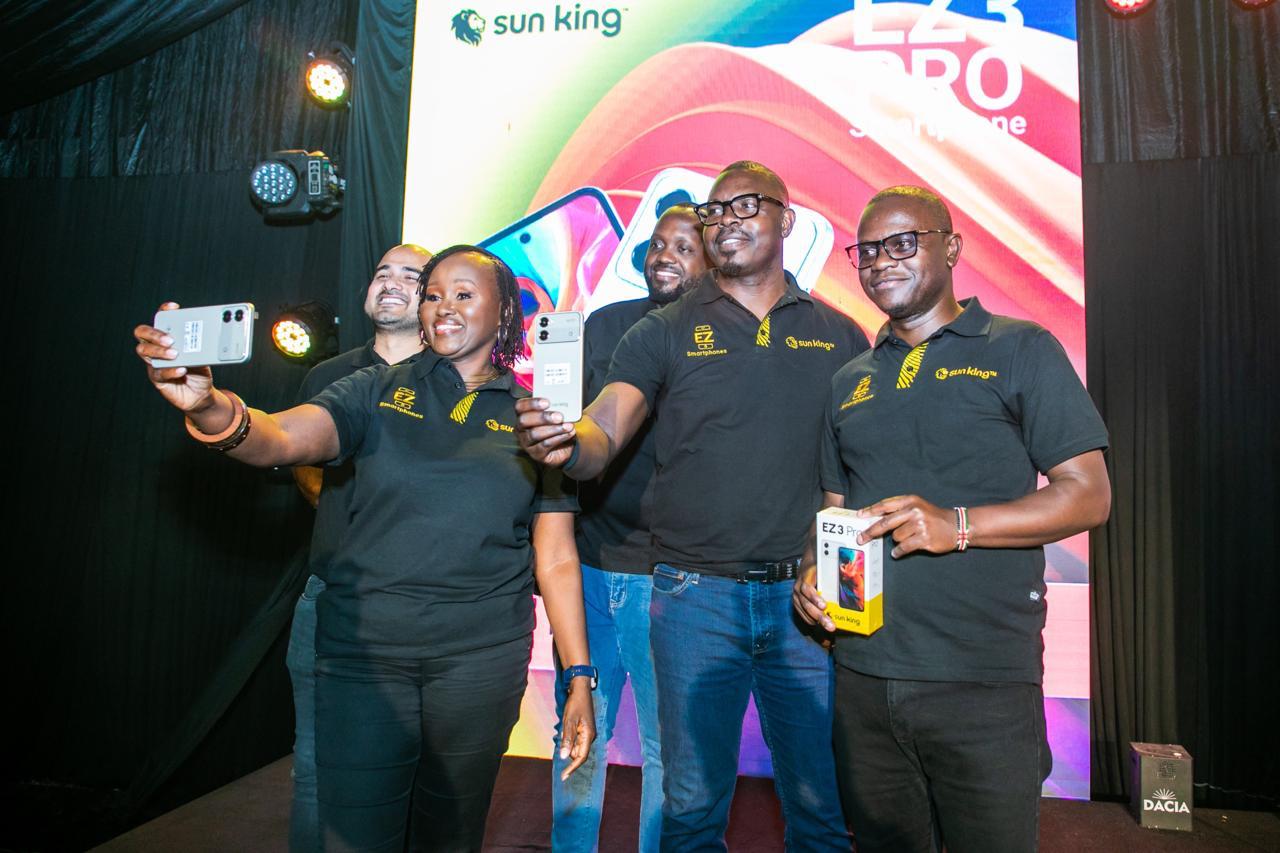
Sun King is expanding its smartphone business in Kenya, launching the EZ 3 and EZ 3 Pro less than a year after entering the market as the solar company looks to turn its distribution and financing infrastructure into a broader consumer technology business.
The company introduced the two devices Thursday, expanding its smartphone portfolio from one model to two. The EZ 3 starts at KES 55 a day with a KES 2,299 deposit, down from KES 60 a day and a KES 2,999 deposit for the EZ 1.
The EZ 3 Pro starts at KES 65 a day with a KES 3,099 deposit.
The launch marks a more deliberate phase of Sun King’s smartphone strategy. Rather than testing the market with a single device, the company is building a broader range while lowering the financial barrier to its mainstream model. Sun King has spent years building a distribution and financing network around affordable solar products in Kenya. Smartphones give the company another category in which to deploy that infrastructure.
Catherine Mudachi, Sun King’s global vice president for marketing, said at the launch that one in five Kenyan households has access to a Sun King product. She also said the company installs more than 330,000 solar kits every month across Africa. That scale gives Sun King a potential advantage in smartphones. The company already has agents, customers and experience managing recurring payments, allowing it to enter the device market without having to build an entirely new distribution model.
The challenge is converting that reach into smartphone sales in a market where established brands already compete aggressively on price, specifications and retail availability.
The EZ 3 is aimed at the mainstream market, with a 6.75-inch HD+ display, a 120Hz refresh rate, 4GB of RAM plus 4GB of virtual RAM, 64GB of storage expandable to 1TB, a 13-megapixel rear camera and a 5,000mAh battery. The EZ 3 Pro moves further up the range with a 50-megapixel camera, 6GB of RAM, 128GB of storage and a 6,000mAh battery supporting 18W fast charging.
The bigger strategic change, however, is the move from one device to a two-phone portfolio. Sun King launched the EZ 1 in February as its first Sun King-branded smartphone in Kenya. The company is now giving customers a choice between a mainstream model and a higher-specification Pro version.
That progression suggests Sun King is moving beyond an initial smartphone experiment and beginning to establish a dedicated device business.
Pay-as-you-go financing is not new to Sun King’s smartphone strategy. It was part of the EZ 1 proposition from the start.
What has changed is the combination of financing, product range and hardware.
The EZ 3 requires a lower deposit and daily payment than its predecessor while offering a larger display, faster refresh rate and expandable storage. The Pro model gives customers the option of paying more for higher specifications.
The approach builds on a model Sun King has used in its solar business: spread payments over time and use a network of local agents to reach consumers who may find conventional upfront purchases difficult.
For smartphones, however, the economics are more competitive. Sun King is competing against brands with established consumer recognition, extensive retail networks and increasingly capable devices at similar price points such as M-KOPA and mainstream phone manufacturers which also offer pay-as-you-go. Banking on affordability with the reach of its existing customer network is a plus.
Its solar products address access to electricity. Smartphones provide access to digital services, mobile money, e-commerce, online work and communication. For traders, smartphones can be used to market products and communicate with customers. For boda-boda riders, they provide navigation and access to digital payments. For creators, they are production and distribution tools.
That makes smartphones a logical adjacent category for a company that already has relationships with millions of consumers across its markets.
But the EZ 3 launch is not about introducing pay-as-you-go smartphones to Kenya. Sun King has already established that model with the EZ 1. Sun King is moving from a single smartphone to a two-device portfolio while lowering the entry payment for its mainstream model.
Sun King’s core business remains solar, but the scale of its distribution network gives the company an opportunity to build additional consumer businesses around the same infrastructure. The company says it has sold more than 31 million solar products globally, while Mudachi said it now installs more than 330,000 solar kits every month across Africa.
In Kenya, Sun King says one in five households has access to one of its products. The smartphone opportunity is to turn that existing reach into a broader consumer technology channel.
The EZ 3 series will test whether the company can do that in a market where smartphone adoption is growing but competition is intense. For Sun King, the significance of the launch is therefore bigger than the specifications of two new phones but a bet on its financing capabilities, distribution network and customer relationships that helped build its solar business.
Safaricom Ethiopia has surpassed 15 million active subscribers, a milestone that underscores the rapid growth of Ethiopia’s second telecom operator as it edges closer to profitability less than four years after launching commercial services.
The company reached the milestone as it marked five years since receiving a nationwide telecommunications license from the Ethiopian government in July 2021. Commercial operations began in October 2022 after more than a year of building network infrastructure and distribution channels.
The operator said it has built more than 3,500 mobile sites covering about 60% of Ethiopia’s population, with every site supporting 4G services and ready for 5G deployment. The rollout ranks among the fastest by a greenfield telecom operator in Africa, Chief Executive Officer Wim Vanhelleputte said.
“Since receiving our license, we have built more than 3,500 network sites, with our network now reaching around 60% of the country’s population. All our sites are 4G-enabled and 5G-ready, making our network state-of-the-art,” Vanhelleputte said.
Safaricom Ethiopia entered one of Africa’s last liberalised telecom markets to compete with state-owned Ethio Telecom, investing heavily in infrastructure, technology and distribution to establish a nationwide network from scratch.
Its rapid subscriber growth is helping narrow losses after years of investment. The company said it is approaching financial break-even as customer numbers and revenues continue to rise.
The expansion has also contributed to Ethiopia’s broader digital transformation, accelerating internet access, mobile data usage and digital payments while extending connectivity to previously underserved communities.
Beyond its commercial operations, Safaricom Ethiopia said it has invested ETB139 million in community projects, while shareholders and development partners have contributed a further ETB545 million, bringing total community investment to ETB684 million.
“We have also witnessed the emergence of world-class talent in information technology in Ethiopia, and we have played our part in supporting that journey,” Vanhelleputte said.
Backed by a consortium led by Safaricom Plc, Vodafone, Vodacom, Sumitomo Corporation and British International Investment, Safaricom Ethiopia has become one of Africa’s largest greenfield telecom investments and is positioning itself as a key driver of connectivity and digital financial inclusion in the country’s 130 million-strong market.
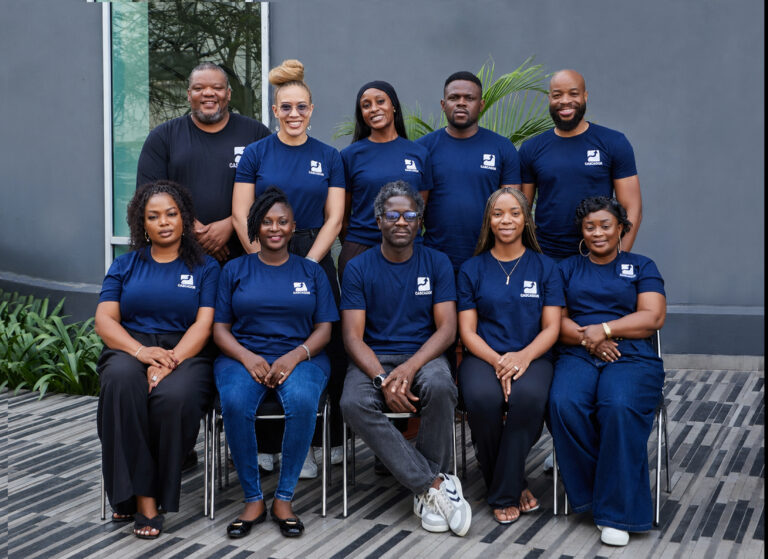
Nigerian entrepreneurship platform Cascador has selected 10 growth-stage companies for its 2026 ScaleUp Program, backing businesses in healthcare, renewable energy, agriculture, property technology and consumer sectors as it shifts its focus toward companies with proven commercial traction.
The companies were chosen from more than 1,000 applicants for the 12-week accelerator, which provides executive mentorship, investor access and eligibility for up to $5 million in follow-on financing through Cascador’s Catalytic Fund, managed in partnership with Sterling Bank.
The 2026 cohort includes property management platform Venco, solar financing startup SunFi, cold-chain logistics provider ColdHubs, healthcare company EHA Clinics, beauty retailer Beauty Hut Africa, wellness chain BEYOND Fitness, hospitality operator Ziba Beach Resort, mineral export marketplace Tulay Africa, agritech firm Maanj Agric, and commercial bakery Finger Chops.
The latest intake marks a strategic change for Cascador, which has increasingly targeted businesses that have moved beyond the startup phase and are positioned for regional expansion.
“Our focus now is helping them scale further and unlock their full potential, giving them the training, mentorship, networks and leadership skills needed to power their next phase of growth,” Chief Executive Officer Trish Thomas said in a statement.
The accelerator combines two weeks of in-person executive sessions with 10 weeks of virtual coaching for founders and their leadership teams. Participants also compete for $50,000 in cash prizes during a live pitch event at the end of the program.
Among this year’s participants is Venco, whose software enables payments, utility billing, resident communication and estate operations for multi-tenanted residential and commercial developments.
“We’re incredibly proud to be part of Cascador’s 2026 ScaleUp Program,” said Venco Chief Executive Chude Osiegbu. “The mentorship, resources and networks the program provides will accelerate our growth as we expand our technology platform to more communities across Africa.”
Women lead 60% of this year’s cohort, while founders come from five of Nigeria’s six geopolitical zones, highlighting the program’s emphasis on building a geographically diverse pipeline of entrepreneurs.
Since its launch in 2019, Cascador has supported 70 ventures that have collectively raised $125 million in external capital. Its alumni served more than 1.7 million customers in 2025, according to the organization.
“The next chapter of Nigeria’s entrepreneurial story will be about what happens when proven businesses get the support they need to scale,” said Cascador co-founder David DeLucia. “That is where sustainable economic value will be created.”
Cascador was founded to strengthen leadership capacity among Nigerian entrepreneurs and has increasingly positioned itself as a bridge between founders, investors and business mentors as startups face a tougher funding environment and growing pressure to achieve profitability.
You can register to be notified when applications open for Cascador’s next cohort here.
Buying Airtel airtime from your M-Pesa account is one of the fastest ways to top up your line without visiting a shop or purchasing a scratch card. Using Pesapal Paybill 220220, Airtel customers can buy airtime directly from the M-Pesa menu in just a few simple steps.
Whether you’re topping up your own phone or sending airtime to someone else, the process takes only a few minutes.
How to Buy Airtel Airtime from M-Pesa
Follow these steps:
Open the M-Pesa menu on your phone.
Select Lipa na M-Pesa.
Choose Pay Bill.
Enter the Business Number: 220220.
In the Account Number field, enter the Airtel phone number you want to top up (for example, 073XXXXXXXX).
Enter the amount of airtime you want to purchase.
Enter your M-Pesa PIN.
Review the transaction details and confirm the payment.
Once the payment is successful, you will receive an M-Pesa confirmation message, and the airtime will be credited to the Airtel number provided.
Why Use Pesapal Paybill 220220?
Pesapal Paybill 220220 offers a convenient way to purchase Airtel airtime directly from M-Pesa without switching between apps or searching for an airtime vendor. The service is designed to provide a quick and seamless top-up experience from anywhere in Kenya.
About Pesapal
Pesapal is a Central Bank of Kenya-licensed financial technology company that provides digital payment solutions for businesses and consumers. In addition to airtime purchases, the platform supports payments for utility bills, television subscriptions and other digital services.
Customers who require assistance can contact Pesapal’s support team on +254 709 219 000 or through the company’s official social media channels.
Benefits of Buying Airtel Airtime via M-Pesa
Using M-Pesa to buy Airtel airtime offers several advantages:
Fast and convenient transactions.
Secure payments through M-Pesa.
Available 24 hours a day from anywhere in Kenya.
Ability to top up your own Airtel line or another person’s number.
No need to buy physical airtime vouchers or visit a retail outlet.
The Bottom Line
If you regularly buy Airtel airtime using M-Pesa, Pesapal Paybill 220220 provides a simple and reliable way to complete your top-ups. Enter 220220 as the Paybill number, use the Airtel phone number as the account number, confirm the payment, and your airtime should be credited within moments.
Kenya’s economy has become deeply dependent on digital systems, from mobile money and digital banking to e-commerce, cloud services, online government platforms and connected workplaces.
Digital transformation has created enormous opportunities for businesses, but it has also created a much larger attack surface for criminals. The scale of Africa’s digital transformation is strikingly high. According to INTERPOL’s African Cyberthreat Assessment Report 2026, the continent recorded more than 1.1 billion mobile subscriptions and more than $1.1 trillion in digital transactions in 2025, while more than 570 million people were using the internet.
The security challenge is growing alongside that digital economy. Kenya is now operating in an environment where criminals can continuously probe networks, devices, accounts and applications for weaknesses. Businesses therefore need to respond quickly enough to prevent compromises into their financial or operational systems.
Artificial intelligence (AI) is making that challenge harder. INTERPOL says AI is enabling 55% of reported cybercrimes across Africa, making attacks faster, more scalable and increasingly difficult for victims and platforms to detect. The agency’s 2026 assessment also describes cybercrime as having evolved from isolated incidents into an industrialized, borderless ecosystem. For Kenya, where mobile money, fintech, digital banking and online commerce are deeply embedded in the economy, the implications are particularly significant.
Kenya’s digital success has created a bigger target
Kenya has spent more than a decade building one of Africa’s most advanced digital economies making mobile money an essential part of everyday commerce. Fintech has transformed financial services and businesses of all sizes leading to increased uptake of cloud applications, digital payments, online customer service and connected workplace systems.
This has also led to the need for protection of these digital environments, identities and organizational pathways. Cybercriminals do not necessarily need to defeat the most sophisticated corporate firewall if they can compromise an employee, steal a credential, manipulate a payment or exploit a supplier with weaker security controls.
The result is that cybersecurity has moved beyond protecting computers. It now involves protecting identities, payments, data, communications, cloud infrastructure and the trust on which digital commerce depends.
INTERPOL’s latest assessment puts this into a broader African context. Financial services, telecommunications and government institutions remain among the sectors most exposed because they sit at the center of the continent’s digital economy. The report also warns that widespread use of mobile money has created new attack surfaces, particularly where customer-verification controls are weak or inconsistently enforced.
AI is changing the economics of cybercrime
The biggest change brought by AI may not be that cybercriminals have discovered an entirely new type of attack. It is that existing attacks can now be conducted faster, more cheaply and at a much greater scale.
A criminal who once needed time and technical expertise to create convincing phishing messages can increasingly use AI to generate them. A fraudster can produce communications tailored to different audiences, imitate corporate communication styles and automate parts of the process of identifying and approaching potential victims. INTERPOL says criminals are using AI for automated phishing, deepfakes for identity fraud and social engineering, synthetic identities for financial crime and techniques designed to evade traditional security systems.
That matters in Kenya because social engineering is particularly powerful in a highly connected economy where businesses communicate constantly through email, messaging platforms and mobile phones. An attacker does not always need to exploit a sophisticated software vulnerability if they can persuade an employee to disclose credentials, approve a transaction or open a malicious file.
The attack may begin with technology, but it ultimately exploits human trust.
The financial stakes are rising
Cybersecurity has also become a financial issue for Kenyan businesses. When an attacker compromises an employee’s email account, the objective may not be to steal information; it may be to redirect a payment. When cybercriminals obtain credentials, they may be trying to gain access to financial platforms. When ransomware enters a business network, the objective may be to interrupt operations and force the organization to pay for recovery.
Local research shows why businesses should take that risk seriously. Serianu’s Africa Cybersecurity Report – Kenya 2025 estimates that Kenyan organizations suffered substantial financial losses from cybercrime, while payment fraud emerged as one of the country’s most significant cybercrime concerns. The report also highlights the widening gap between the speed of digital adoption and the maturity of cybersecurity defenses.
This makes cybersecurity spending not simply an IT expense but necessary to protect revenue, cash flow, customer relationships and business continuity.
East Africa is facing a particularly difficult threat environment
Kenya’s position within East Africa makes the regional dimension particularly important. INTERPOL identifies East Africa as a hub for mobile-money fraud and infrastructure-targeted ransomware. Kenya recorded more than 46,786 DDoS attacks targeting telecommunications companies in the first half of 2025, according to data included in the agency’s latest assessment.
The threat to mobile money is especially significant. INTERPOL says SIM-swap fraud in Kenya surged by 327% in 2025, with more than 123,000 fraudulent SIM cards detected and an estimated $3.8 million drained from mobile wallets. The figures demonstrate why cybersecurity in Kenya cannot be reduced to protecting laptops and corporate networks. The threat increasingly extends across identities, telecommunications infrastructure, financial accounts, mobile applications and the systems that connect them.
The same digital infrastructure that allows a Kenyan entrepreneur to receive a customer payment in seconds can also allow a fraudulent transaction to move just as quickly. Speed therefore becomes a critical part of defense.
By the time a business discovers that a fraudulent payment has been made, the money may already have moved through several accounts or wallets. Similarly, by the time ransomware has encrypted critical files, prevention has already failed and the organization is dealing with recovery. The goal has to be earlier detection.
Kenya is already seeing massive volumes of cyber threats
The scale of activity detected by Kenya’s cybersecurity authorities demonstrates why manual defense alone is becoming increasingly difficult. Kenya’s threat environment is characterized by persistent probing, exploitation attempts, malware, phishing, DDoS activity and credential attacks, creating an enormous volume of information for security teams to process.
The challenge is not that every alert represents a successful breach. It is that a security team can quickly be overwhelmed when thousands or millions of signals have to be examined to determine which ones represent a serious threat.
That creates an information problem.
The more alerts an organization receives, the more difficult it becomes for human analysts to determine which ones deserve immediate attention. A security team that spends its time investigating low-risk activity can miss the behavior that signals a serious compromise.
This is where AI can change the defensive equation.
The defender needs AI too
If cybercriminals are using AI to increase the speed and scale of attacks, businesses need technology that can help security teams process information at a similar scale.
AI-assisted cybersecurity can analyze large volumes of security data, identify unusual behavior, correlate related events and help prioritize incidents. Instead of forcing analysts to investigate every alert individually, intelligent systems can help identify patterns that deserve closer examination.
Consider a Kenyan company where an employee’s laptop suddenly behaves unusually. At roughly the same time, the employee’s credentials are used to access a corporate system from an unfamiliar location, while a suspicious file appears on the endpoint.
Three separate alerts might not mean much on their own. Together, however, they could indicate the early stages of an attack. The ability to correlate those signals quickly can make the difference between containing an incident and dealing with a much larger breach.
From protection to detection and response
Traditional endpoint protection remains essential. Businesses need technology capable of blocking malware, suspicious files and other known threats before they can cause damage.
But today’s threat environment requires more than prevention.
Security teams need to know what happens when something gets through, what systems are affected, how the attack developed, and what needs to happen next. That is the broader shift toward detection and response.
Kaspersky Next brings together endpoint protection with capabilities designed to help organizations detect, investigate and respond to threats. For businesses that do not have large security operations teams, this kind of integrated visibility can be particularly important because it can help reduce the amount of manual work required to understand an incident.
The objective is not to replace cybersecurity professionals with AI. It is to give those professionals better tools for making decisions.
The human factor is becoming more important, not less
The growth of AI does not eliminate the human element of cybersecurity. In some respects, it makes it more important.
Employees remain targets for phishing, impersonation, fraudulent invoices, malicious attachments and social engineering. As AI makes fraudulent messages more convincing, employees may find it increasingly difficult to distinguish legitimate communication from a carefully constructed attack.
INTERPOL’s assessment highlights the growing use of deepfakes, synthetic identities and AI-enabled social engineering across Africa. The report also says AI-generated digital personas are being used to combine real personal information with fabricated elements to bypass identity-verification systems and facilitate fraud.
That means cybersecurity awareness cannot be treated as a once-a-year training exercise. Businesses need employees who understand that a convincing email, phone call or video is not necessarily proof of identity.
At the same time, organizations need technical controls that assume humans will eventually make mistakes. Strong authentication, least-privilege access, endpoint protection, patch management, network monitoring and tested incident-response procedures all need to work together.
SMEs cannot assume they are too small to be targeted
For Kenyan small and medium-sized businesses, the temptation can be to assume that cybercriminals are interested only in banks, telecommunications companies and government institutions. That assumption can be expensive.
Smaller organizations can hold valuable customer information, financial data and credentials while often having fewer resources dedicated to cybersecurity. They can also provide attackers with access to larger organizations through suppliers, contractors and business relationships.
This makes cybersecurity a business-growth issue and not an issue for larger corporations but a priority at every scale of growth. The most dangerous strategy is not having a limited cybersecurity budget but having no cybersecurity strategy at all.
Cybersecurity is now a business resilience issue
INTERPOL’s latest assessment makes cybercrime no longer simply a technical problem but an issue of economic security, public confidence and institutional resilience. The report says cybercrime-related losses across Africa more than doubled from $192 million in 2024 to $484 million in 2025, driven primarily by AI-facilitated scams, credential harvesting and automated social-engineering campaigns.
For Kenyan businesses, the consequences can extend far beyond the device where an attack begins. A compromised employee account can become a payment-fraud incident. A ransomware infection can become a business-continuity crisis. A stolen customer database can become a regulatory and reputational problem.
This is why businesses need to think beyond the question, “How do we stop malware?”
The better questions are: How quickly can we detect an attack? Can we identify what has been compromised? Can we contain it? Can we recover? And how much of the business can continue operating while the incident is being resolved?
Those are resilience questions.
The AI cybersecurity arms race has begun
The central question for Kenyan businesses is no longer whether AI will change cybersecurity because it already has. But the real question is whether defenders can adopt AI and automation quickly enough to keep pace with attackers.
INTERPOL’s latest assessment provides a clear warning: AI is enabling 55% of reported cybercrime across Africa, while criminals are using the technology to automate phishing, create deepfakes, develop synthetic identities and improve social engineering.
Kenya is particularly exposed because its digital economy is built around precisely the systems cybercriminals are increasingly targeting: mobile money, digital payments, telecommunications, financial services and online platforms. INTERPOL’s finding that East Africa has emerged as a hub for mobile-money fraud and infrastructure-targeted ransomware should therefore be viewed as a business warning, not simply a law-enforcement statistic.
The answer cannot be to replace people with AI. Rather, businesses need to use technology to make their security teams more effective. AI can process enormous volumes of information, recognize patterns and help prioritize threats, while security professionals provide context, investigate incidents and make decisions about how an organization should respond. Neither works as effectively alone.
Kenya’s next digital chapter needs stronger security
Kenya’s digital economy is not slowing down. Mobile money, fintech, cloud computing, AI, e-commerce and digital public services will continue to expand. Every new layer of digital adoption will create new opportunities for businesses and new opportunities for cybercriminals.
Securing an organization won’t just need teams to prevent attacks but be able to identify threats early, understand what is happening, contain incidents quickly and recover with minimal disruption. That requires a shift from cybersecurity as a defensive product to cybersecurity as an ongoing business capability.
Designed around that shift, Kaspersky Next is bringing together protection, detection, investigation and response capabilities to help organizations gain greater visibility into modern threats and respond more effectively.
For Kenyan businesses, the message is increasingly clear. The same technologies that are accelerating digital transformation are also changing the threat landscape. AI gives criminals new tools to attack faster and at greater scale, but it can also give defenders the ability to process more information, identify threats earlier and respond more intelligently.
The cybersecurity battle in Kenya is becoming an AI battle and organizations that recognize that shift early and build their defenses accordingly will be better positioned to protect not only their systems, but their customers, their money and their ability to keep doing business.
Ready to strengthen your organization’s cybersecurity?
Learn more about Kaspersky Next and how AI-powered protection, detection and response can help your business prepare for the next generation of cyber threats.
Two directors of Kenya-based buy-now-pay-later firm Flexitech Group Limited have been arrested in connection with the alleged misappropriation of Sh31.2 million ($242,000) belonging to a leading retail chain.
The Directorate of Criminal Investigations (DCI) said Martin Kariuki Maina and Johnson Gituma Mwangi were arrested in Roysambu following investigations into a complaint filed by the retailer.
Flexitech had been acting as an agent for the retailer, collecting payments from customers who had purchased and collected goods from various branches.
According to the DCI, the company received Sh31,213,700.95 from customers for onward remittance to the retailer. Investigators allege that the funds were instead diverted for the personal use of the two directors, working with other suspects who remain at large.
The arrests were made by detectives from the DCI Nairobi Regional Office as they traced the funds and investigated the alleged involvement of other individuals.
Maina and Mwangi are being held ahead of their arraignment at the Milimani Law Courts, where they are expected to face charges of stealing by agent under Section 283(b) of the Penal Code.
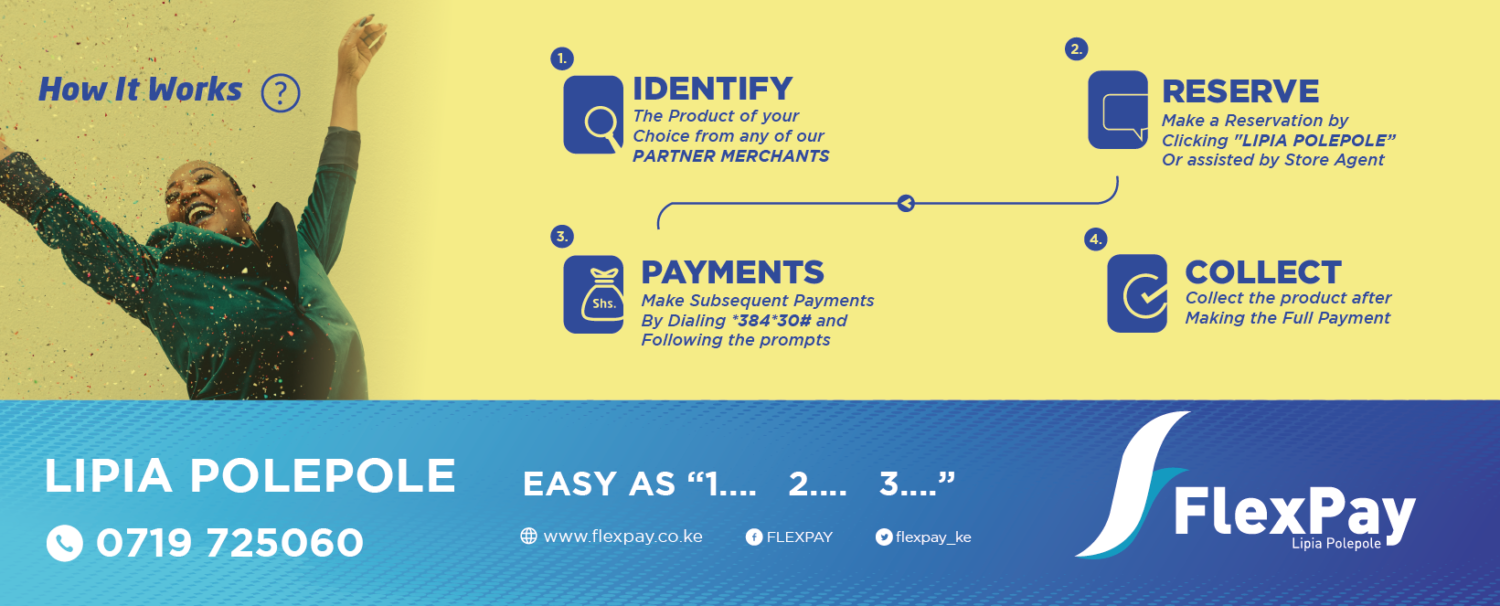
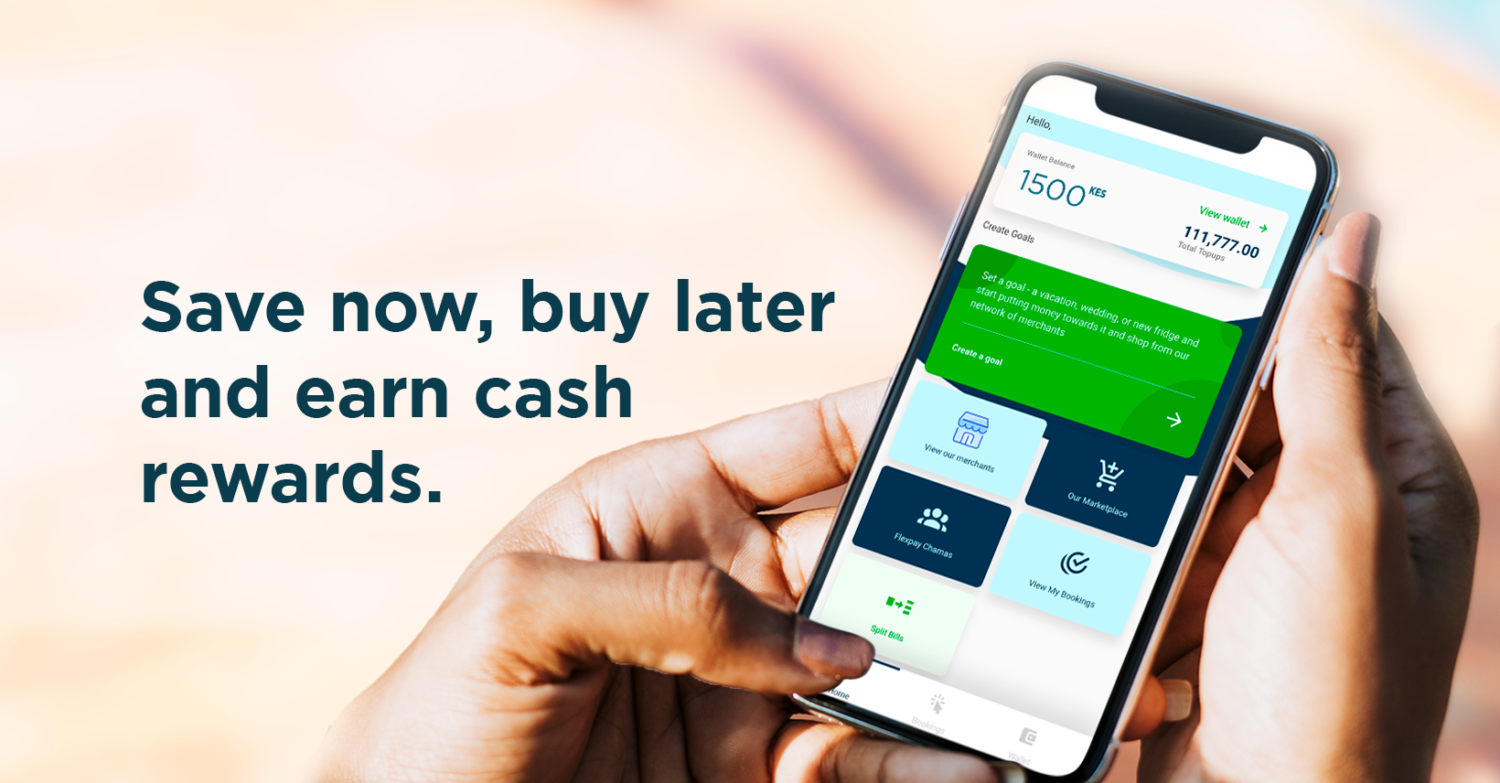
Flexitech operates in Kenya’s consumer-financing market, providing buy-now-pay-later services that allow customers to acquire goods and pay for them over time. The sector includes other consumer-financing players such as Lipa Later, which shut down and Aspira. FlexPay is one of the innovative financial service products that has emerged from Kenya, the home of Africa’s first mobile money service, MPESA. FlexPay aims to bridge the affordability gap with practical and affordable financial services thus protecting customers from the dangers of debt.
The case puts a spotlight on the risks involved when consumer-financing companies and their agents handle large volumes of customer payments on behalf of merchants.
The DCI said investigations remain ongoing and detectives are pursuing other people believed to have been involved in the alleged diversion of the funds. The allegations have not been tested in court, and Maina and Mwangi are presumed innocent unless proven guilty.
French health insurer Alan is buying Senegalese healthtech startup Tanel, taking its first step into Africa through a company backed by investors including football star Kylian Mbappé.
The acquisition gives Alan a foothold in two of West Africa’s fastest-growing healthcare markets and turns Tanel into the launchpad for an expansion that the companies expect will reach more than 1 million members across Africa by 2030.
Tanel, founded in 2021 by Mouhamed Ndoye and Makhtar Diop, has built a digital platform for managing employee health coverage in markets where healthcare administration remains heavily fragmented. The company operates in Senegal and Côte d’Ivoire, serving about 70,000 members at more than 400 companies and linking them to more than 1,200 pharmacies and healthcare providers.
Alan first backed Tanel in its 2024 seed round. The relationship has since evolved into an acquisition, giving the French company local infrastructure, healthcare partnerships and regulatory knowledge as it enters a continent where it previously had no operating presence.
The companies plan to strengthen their businesses in Senegal and Côte d’Ivoire before targeting Anglophone markets in West and East Africa. The first phase will focus on integrating their platforms, improving the digital patient experience and bringing Alan’s preventive healthcare and telehealth services to Tanel customers.
The deal is also an exit for Tanel’s founders and early investors, including Ventures Platform and AAIC Investment, as well as angel investors such as Dr. Mussaad M. Al-Razouki, Alyune-Blondin Diop and Charles “Chuck” Slaughter.
For Ventures Platform, which backed Tanel early, the transaction highlights the growing potential for African startups to attract strategic buyers despite a still-thin market for technology exits.
“African tech still sees too few exits, particularly in Francophone Africa,” Dotun Olowoporoku, Managing Partner at Ventures Platform, said. “Alan’s acquisition validates their vision and demonstrates the potential for ambitious, locally built companies to create lasting value.”
Alan has more than 1.2 million members across France, Spain, Belgium and Canada. Its entry into Senegal and Côte d’Ivoire gives it access to a regional health-insurance market estimated at almost €600 million, growing at about 10% annually.
For Alan co-founder and CEO Jean-Charles Samuelian-Werve, Tanel offers something difficult to build from scratch: an established network across local healthcare systems.
“Tanel has done the hard work of building relationships with users, companies, healthcare providers and regulators in Senegal and Côte d’Ivoire,” Samuelian-Werve said. “Combining that knowledge with Alan’s platform gives us a strong base from which to build in Africa.”
Ndoye and Diop will remain in charge of Tanel’s operations and Alan’s African expansion, with the startup’s full team staying in place.
Tanel began by building infrastructure for pharmacies before expanding into tools covering the broader healthcare journey, as the founders sought to replace paper-heavy processes with digital services.
The acquisition gives Alan a ready-made African operation while giving Tanel access to the technology, capital and product expertise of a European healthtech company. It also marks another major liquidity event for Africa’s startup ecosystem, where large strategic acquisitions remain relatively rare.
Uber Technologies Inc. is shutting down its operations in Nigeria and Uganda, ending more than a decade in both markets as the ride-hailing company cuts about 3,300 jobs and shifts investment toward autonomous mobility.
The exits take effect Wednesday, September 2. Uber launched in Nigeria in 2014 and Uganda in 2016, meaning the withdrawals end 12 years of operations in Nigeria and 10 years in Uganda.
Uber said the decisions reflect changing business priorities and investment focus, rather than a broader retreat from Sub-Saharan Africa. Uber’s exit in Nigeria could be due to a weaker currency, high inflation, rising fuel and vehicle costs, expensive maintenance, pressure for higher driver earnings, and increasingly complex regulatory and operating requirements, while passengers have limited room to absorb higher fares. Those pressures squeeze margins from both sides and make continued investment harder to justify.
Uber stated clearly the exits from the Nigerian and Uganda markets are due to the changing business priorities and investment focus. The company will continue operating in Kenya, South Africa and Ghana. Uber launched in Egypt in 2014, initially in Cairo, and has expanded its services there and it has no signs of shutting down in these remaining markets.
The moves further reduce Uber’s African footprint after it suspended operations in Tanzania in 2022, following regulatory changes that affected fares and commissions. The company has therefore exited or suspended operations in three African markets while maintaining operations in three others.
Globally, Uber is eliminating about 3,300 positions, or roughly 10% of its workforce, in its biggest job reduction since the pandemic. Chief Executive Officer Dara Khosrowshahi said the company’s rapid expansion had created layers of management and organisational complexity that slowed decision-making.
The restructuring will flatten the company’s corporate structure and reduce fully remote roles, with savings redirected toward growth and innovation. Autonomous transportation is a major focus. Uber plans to invest more than $10 billion in robotaxis over the coming years through partnerships with companies developing self-driving technology.
The strategy positions Uber for a transportation market in which human drivers could increasingly compete with autonomous fleets. Rather than owning most of those vehicles, Uber wants its platform to connect riders with robotaxi operators.
In Nigeria, the departure is particularly significant. Uber has operated in the country since 2014 and its exit opens more room for competitors and local mobility companies to capture riders and drivers. The company has not identified regulatory disputes as the reason for leaving Nigeria, despite recent disagreements with the Federal Airports Authority of Nigeria over airport pick-up operations.
Uber’s latest restructuring signals a shift away from the rapid geographic expansion that defined much of its first decade toward a more concentrated strategy focused on efficiency, profitability and the emerging autonomous mobility market.
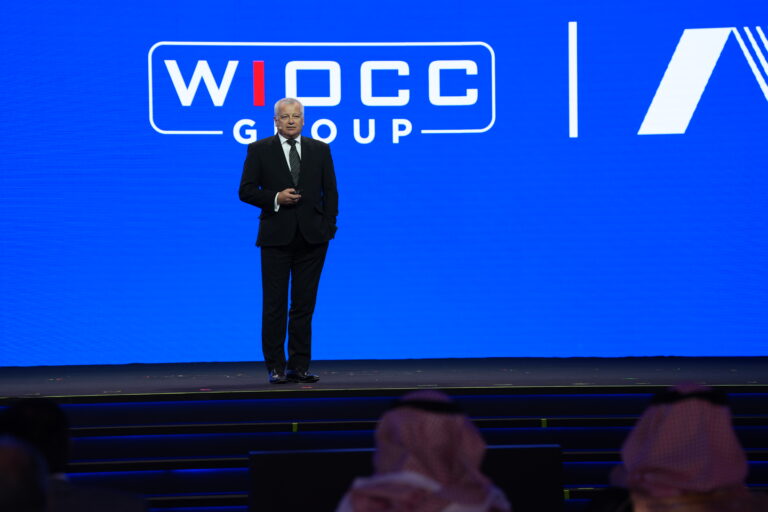
WIOCC Group, Africa’s top carrier-neutral digital infrastructure firm, has secured $300 million investment to expand its open-access, critical infrastructure across Africa at a pivotal moment when Africa’s demand for data, cloud services and artificial intelligence continues to grow.
The investment via a Shareholder Subscription Agreement (SSA) with Africa Finance Corporation (AFC) and Vision International Investment Company (Vision Invest) was signed at the LEAP 2026 Global Technology exhibition in Riyadh.
In a press statement seen by TechMoran, Chris Wood, Group Chief Executive Officer of WIOCC Group, said, “Africa is uniquely positioned to capitalise on the next phase of global digital growth. As demand for cloud, AI and digital services accelerates, robust and scalable infrastructure will be essential to unlocking the continent’s potential.”
Wood added that this investment will enable WIOCC to accelerate data centre deployment and consolidation, expanding open-access terrestrial fibre footprint and invest in new subsea assets to strengthen Africa’s digital infrastructure platform and enhance connectivity between the continent and key international markets.
According to the International Telecommunication Union (ITU), only 35.7% of Africa’s population was using the internet in 2025, compared with a global average of 73.6%, highlighting the scale of the continent’s digital infrastructure needs and growth potential. Meanwhile, the United Nations Conference on Trade and Development (UNCTAD) projects the global AI market will reach US $4.8 trillion by 2033, while warning that access to AI capabilities and digital infrastructure remains concentrated in a limited number of countries and companies. These trends underscore the importance of investing in resilient, high-capacity infrastructure that can expand digital access, support cross-border data flows and help narrow the digital divide.
WIOCC Group operates in more than 30 African countries with support from top firms such as International Finance Corporation (IFC) and African Capital Alliance (ACA) and various telcos across Africa. This new investment will helpit expand and serve more customers in these markets.
In December 2025, WIOCC raised $65 million in debt financing to expand its network and data centre footprint across the continent. The facility, structured as sustainability-linked debt, was arranged by the International Finance Corporation (IFC), Proparco, Emerging Africa Infrastructure and Asia Infrastructure Fund (EAAIF), and asset manager Ninety-One.
In March the same year, WIOCC signed a colocation agreement with iColo, a carrier-neutral data centre provider to accelerate the growth of Internet Service Providers (ISPs) in Mombasa and across Kenya. The collaboration was expected to enhance digital infrastructure, improve interconnectivity and unlock new market opportunities for ISPs, ultimately contributing to Kenya’s rapidly expanding digital economy.
“The Africa we build must be connected, competitive and equipped to create value from the digital economy, not only consume it,” said Samaila Zubairu, President & Chief Executive Officer of AFC, “Just as transport corridors enable trade and energy networks power industry, fibre, data centres and subsea cables are now essential infrastructure for growth, innovation and AI. Our investment in WIOCC will expand the open-access digital backbone African businesses and communities need to integrate, innovate and compete globally.”
Together, AFC, Vision Invest and WIOCC aim to contribute to accelerating the development of Africa’s digital ecosystem and supporting the continent’s growing role in the rapidly evolving global digital economy.
‘WIOCC Group has built one of Africa’s leading digital infrastructure platforms, and we are proud to partner together with AFC and WIOCC’s existing shareholders as the company enters its next phase of growth. Home to the world’s youngest population and expected to account for more than one-quarter of the global population by 2050, demand for digital services in Africa will continue to rise, necessitating impactful investments in connectivity and digital ecosystems to unlock new opportunities for innovation, economic diversification and sustainable growth as well as opportunities for businesses, innovators and communities across Africa,” concluded President & Chief Executive Officer of Vision Invest, Omar N. Al-Midani.
For decades, Kenyan banks competed on branch networks, lending products, interest rates and the strength of their customer service. However, things are a bit different today as customer loyalty is no longer shaped by customer service and branch networks but the cost and convenience of moving money.
This is partly due to the digital transformation amongst the banking sector Kenya and a digital payments revolution that has fundamentally changed how people interact with financial institutions from the banking hall to their mobile phones. Banking is no longer an occasional activity confined to branches as the mobile phone allows customers to transfer money, pay suppliers, settle school fees, receive salaries, shop online and move funds between accounts from almost anywhere in the world.
With the convenience of the mobile phone, the major issue has been the cumulative impact of transaction fees and not access to funds like it was a decade ago.
According to the World Bank’s Global Findex 2025, “Across low- and middle-income economies, 61 percent of adults, or 82 percent of account owners, made or received a digital payment in 2024, a 27 percentage point increase from 2014. Digital payments are the most popular formal financial service, used by twice as many adults as saved formally and by three times as many as borrowed formally.
Use of digital merchant payments to businesses in stores or online grew to 42 percent of all adults in 2024, up from 35 percent in 2021, with variations by region. The share of adults making such payments more than doubled in some economies, including Cameroon, the Kyrgyz Republic, Paraguay, and Viet Nam, and showed widespread adoption in Kazakhstan, Kenya, and Mongolia.
The numbers illustrate just how deeply digital finance has become embedded in everyday life. The report adds that mobile phones and the internet have revolutionized financial inclusion, enabling more people to access and use digital financial services to manage their financial lives. From mobile money accounts on basic phones to bank-account-linked wallets on smartphones, digital services are fulfilling their promise of being more accessible and affordable than alternatives that are not digitally accessible, bringing daily utility payments, savings, deposits, withdrawals, loan disbursements and repayments to them via apps.
The World Bank’s latest Global Findex data shows 94% of Kenyan adults own a financial account, while 89% made or received a digital payment during the previous year. Digital transactions are no longer simply an alternative to cash; for millions of consumers, they are the default way of managing money.
That shift has changed what customers expect from their banks and increasingly, people are not choosing a financial institution based solely on its loan products, branch footprint or savings rates but the cost of access to these funds.
Every Transaction Shapes Loyalty
Because of the need for instant access powered by technology, a successful transaction builds confidence while a delayed payment creates frustration. Also a recurring fee may appear insignificant, but when it is attached to dozens of transactional costs over a month, customers begin to notice.
This is where the cost of transaction becomes important and not just access to the funds. Consumers tend to notice frequent costs that recur on their deposits, withdrawals, utility payments, transfers, or remittance and start questioning access vs affordability on the cost of banking. Over time, those charges have influenced the loyalty of customers and how customers perceive the value they receive from their financial institution.
Recent PesaLink research highlights the changing priorities of Kenyan consumers. 64% of account-to-account payment users surveyed said affordability influences their choice of payment service, while more than 60% identified speed and convenience as important factors. The study also found that 57% of users maintain relationships with multiple financial institutions.
That last figure is particularly important for banks. Customers are increasingly comfortable maintaining several banking relationships. A salary may be paid into one bank, savings held elsewhere and everyday transactions handled through another institution or digital wallet. This gives consumers more choice and makes loyalty harder for banks to take for granted.
If another institution can provide the same service faster and at a lower cost, switching becomes increasingly easy.
The Digital-First Customer
Kenya’s financial ecosystem has produced a customer who is comfortable with digital financial services and increasingly unwilling to tolerate unnecessary friction. The modern customer may never visit a branch. Instead, their relationship with a bank is built through an app, a payment notification, an ATM or an account-to-account transfer.
They expect to pay a supplier while sitting in a café, send money to a family member from work, settle a bill from home or transfer funds between accounts late at night. The technology itself is becoming less important to the customer. What matters is the outcome like did the money arrive, how quickly did it arrive, was the transaction secure and most importantly how much did it cost?
These questions are becoming more important than the number of features a bank has added to its mobile application.
SMEs Feel the Difference
The impact is particularly significant for small and medium-sized enterprises. Speaking to TechMoran, Mbugua Njihia, a Kenyan technologist said cost is more important than access especially for SMEs which form the bulk of the Kenyan economy.
‘’An SME may make multiple payments to suppliers, employees, distributors and service providers every day,’’ he said. ‘’It may also receive hundreds of customer payments over the course of a week and for a business operating on tight margins, transaction fees can quickly become a recurring operating expense and it will soon be an issue of moving banks or payment service providers.”
To him, the banks of the future, therefore, need to remove those costs as they can have a major effect beyond customer convenience. The cost of access can keep a client as those little recurring transactions can help a business retain more working capital, simplify reconciliation and make digital payments more attractive. “Cashflow is key to SMEs,’’ he adds.’
The same principle applies to freelancers and independent professionals. A freelancer may receive payments from several clients, move income into savings, pay subscriptions and transfer money to suppliers or family members. Each transaction represents another point at which a bank can either create friction or remove it.
Families Are Changing Too
For households, digital payments have become equally important as most parents are using digital channels to pay school fees and household bills. Families send money to relatives in different towns. Young professionals move funds between savings, investment and spending accounts. In Kenya, these are not occasional banking activities but part of everyday financial life.
When a customer repeatedly pays for routine transactions, the cumulative cost becomes part of their perception of the bank. This is why zero-fee payments can have an impact beyond the immediate amount saved. They create a sense that the bank is working with the customer rather than charging them for every movement of their own money.
Real-Time Payments Raise the Bar
Kenya’s expanding instant-payment infrastructure is reinforcing these expectations. PesaLink, the country’s real-time account-to-account payment network, now connects more than 80 banks, SACCOs and financial institutions, serves more than three million users and has processed over KES 1 trillion in transactions.
That scale matters because it demonstrates how quickly consumers and businesses have become accustomed to moving money electronically. Once customers experience instant transfers, waiting for funds to clear becomes increasingly difficult to justify. Similarly, once consumers become accustomed to lower-cost transactions, recurring charges can start to feel outdated. The result is a new baseline for banking. Speed is expected. Security is expected. Convenience is expected. Increasingly, affordability is expected too.
How SBM Bank Kenya Is Responding
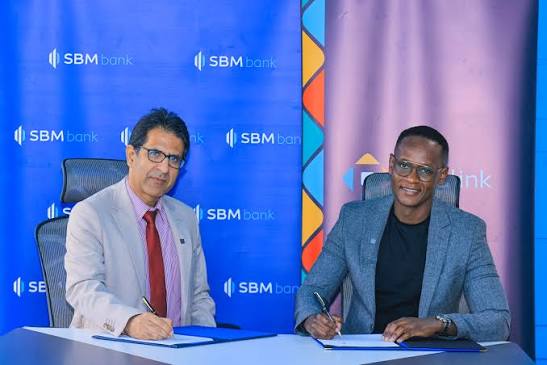
This changing behaviour is reflected in SBM Bank Kenya‘s approach to digital payments. Through its Mfukoni App and #TumaForFree campaign, the bank is offering customers free PesaLink and interbank transfers, removing transaction charges on eligible transfers and reducing the cost of moving money between financial institutions.
The significance is less about a single fee and more about the changing economics of customer engagement. Customers frequently need to move money between different banks, whether paying suppliers, sending money to family, settling bills or managing funds across accounts. Removing the transfer charge can make these everyday transactions more affordable while reducing friction.
For SMEs in particular, the savings can accumulate over time. A business making multiple payments to suppliers, employees and service providers can turn transaction charges into a recurring operating expense. A zero-fee transfer proposition can therefore help businesses retain more working capital while making digital payments more attractive.
For individual customers, the proposition is similarly straightforward: where a transfer qualifies under the offer, customers can move money without paying an additional transfer fee. The benefit is not that all banking services at SBM Bank are free, but that eligible PesaLink and interbank transfers can be made at zero transaction cost.
SBM’s broader performance also provides context for its digital strategy. In the first half of 2026, the bank reported profit before tax of KES 547 million, up 171% from KES 202 million a year earlier. Customer deposits reached approximately KES 94 billion, while total assets stood at about KES 126 billion.
The figures do not prove that zero-fee transactions alone drove the growth. Rather, they show the broader environment in which the bank is expanding its digital and customer-focused strategy.
The Global Shift
Kenya’s experience is part of a much larger transformation. Worldwide, consumers are moving rapidly towards digital and real-time payments. McKinsey has identified payments as one of the most important areas of financial services transformation, with customers increasingly demanding instant and seamless experiences.
PwC has projected strong growth in global non-cash payment volumes, driven by the adoption of digital wallets, account-to-account payments and real-time payment systems. Meanwhile, estimates from Africa’s payments industry suggest that the continent’s digital payments ecosystem could reach US$1.5 trillion by 2030.
For banks, this represents both an opportunity and a challenge. As payment infrastructure becomes more interoperable, customers gain more freedom to move money between institutions. The bank that retains the customer will increasingly be the one that provides the best overall experience rather than simply the institution where the customer first opened an account.
Loyalty Through Less Friction
For years, banks invested heavily in acquiring customers by having more branches, launching mobile applications, introducing loyalty programmes and expanded product portfolios but the next challenge is keeping those customers.
Zero-fee transactions are one way of doing that because they address something customers experience repeatedly. Every time a customer transfers money without an additional charge, the bank removes a small point of friction. Repeated hundreds of times, those experiences can shape perception.
That is why the economics of banking loyalty are changing. Customers may appreciate a sophisticated app, but they are likely to remember whether the bank made everyday financial tasks easier and more affordable. The competitive advantage may therefore shift from having more features to creating fewer obstacles.
For SBM Bank Kenya, the proposition is ultimately about reducing the cost of everyday money movement. The bank is positioning zero-fee eligible transfers not as a claim that banking itself is free, but as a way of removing one of the most frequent costs customers encounter when moving money between financial institutions.
As digital payments become the infrastructure of modern commerce, every transfer becomes an opportunity to reinforce or weaken the relationship between a bank and its customers. Making eligible transfers free can turn a routine transaction into a point of customer value.
The future of banking will not necessarily belong to the institution with the most products or the most elaborate app. It may belong to the bank that makes thousands of everyday financial decisions feel effortless, affordable and secure. For customers, zero-fee transfers are increasingly becoming part of that expectation.
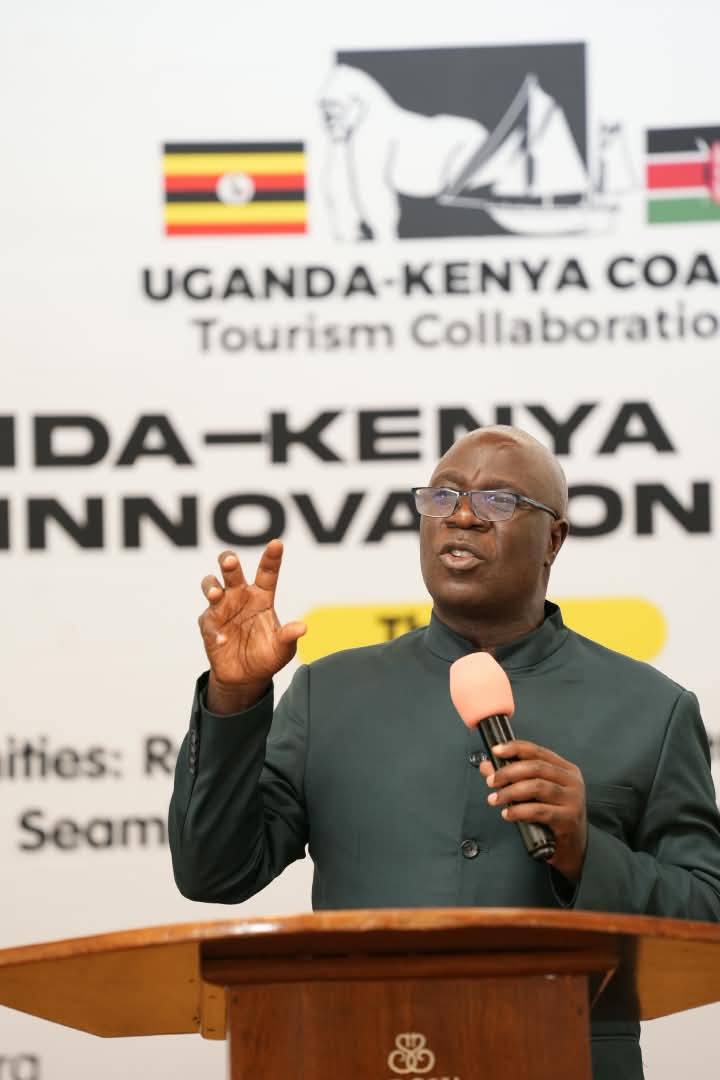
Uganda and Kenya are seeking to unlock investment and business opportunities in tourism, technology and innovation while addressing barriers to seamless movement across East Africa.
The agenda will feature at the fifth Uganda–Kenya Coast Tourism and Innovation Summit, scheduled for Oct. 26–27 at Sarova Whitesands Beach Resort & Spa in Mombasa. The summit will bring together government, tourism, technology, investment and private-sector representatives from the two countries.
Held under the theme, “Unlocking Tourism Opportunities: Resolving Policy Bottlenecks through Technology, Youth and Seamless Mobility across East Africa,” the summit will focus on practical solutions to policy and operational challenges affecting tourism and cross-border business.
Technology and youth innovation will be central to the discussions, with digital solutions expected to be showcased alongside opportunities in tourism investment, smart destinations and connectivity.
“This Summit reflects the strength of the partnership Uganda has built with our friends on the Kenya Coast over the past five years. As we mark ten years of the Consulate’s presence in Mombasa, we are moving beyond dialogue to concrete, action-oriented cooperation, particularly in harnessing technology and youth innovation to unlock the full potential of tourism between our two countries,” said Amb. Herbert Kiguli, Consul General of the Republic of Uganda in Mombasa.
Since 2022, more than 450 stakeholders have participated in the Uganda–Kenya Coast familiarisation programme, helping tourism operators build relationships and promote complementary destinations across the two markets.
Regional mobility will also be a key focus, with participants examining challenges affecting tourism and business travel under Article 104 of the East African Community Treaty, which provides for the progressive removal of restrictions on the movement of persons, labour and services.
Key tourism stakeholders came together for the launch of the 5th Uganda-Kenya Tourism & Innovation Summit 2026 which took place in Mombasa, Kenya. The Summit, convened by the Consulate General of Uganda in Mombasa will bring together stakeholders on the 26th to the 27th of October 2026 under the theme “ Unlocking Tourism Opportunities: Resolving Policy Bottlenecks through Technology, Youth and Seamless Mobility across East Africa
Easing such barriers could support cross-border tourism, investment and commercial activity by making it easier for tourists, businesses and service providers to operate across the region.
“Mombasa County is proud to welcome this Summit as a platform that puts our tourism offering firmly on the regional stage. We see real value in deepening ties with Uganda, particularly in opening up smart, tech-enabled and youth-driven approaches to tourism that benefit both our destinations,” said Hon. Mohammed Osman, County Executive Committee Member for Tourism, Mombasa County.
The summit will feature policy discussions, innovation showcases and business-to-business engagements and is expected to produce a Summit Communiqué outlining priorities and timelines for follow-up.
The event also marks the fifth annual engagement between the Ugandan Consulate and Kenya Coast stakeholders and coincides with the 10th anniversary of the Consulate’s active presence in Mombasa.
The organizers say the summit will contribute to East African integration by positioning tourism, innovation, technology and seamless mobility as drivers of investment and regional economic growth.
Doage, a new insurance technology advisory and commercialisation platform founded by insurance executive Dominic Agesa Kavugwi, has launched with a focus on helping African InsurTech startups convert innovation and investment into sustainable commercial growth.
The launch comes as Africa’s InsurTech industry continues to attract record investment while founders face increasing pressure to demonstrate revenue growth and long-term viability. AfricInvest’s 2026 African InsurTech Landscape report estimates that more than US$300 million has been invested in African InsurTech startups over the past five years, with annual funding reaching a record US$80.6 million in 2025. The report forecasts Africa’s insurance market will expand from US$92.9 billion in 2024 to US$160.9 billion by 2033.
The broader African startup ecosystem has also become more selective. Only 178 African technology startups secured funding in 2025, although total investment recovered to more than US$1.6 billion, underscoring investors’ growing focus on businesses capable of delivering commercial returns.
Kavugwi said the challenge facing many startups is no longer developing innovative products or raising capital, but successfully taking those products to market.
“Africa does not have a shortage of innovation. What we still have is a commercialisation gap,” he said.
Doage will advise InsurTech startups, insurers, investors and international technology companies on commercial strategy across African markets. Its services include go-to-market planning, enterprise distribution, strategic partnerships, market entry, expansion, investor readiness and revenue growth.
The company said it is positioning itself as a commercialisation partner rather than another accelerator, working with businesses after product development and fundraising to help secure customers, distribution partnerships and sustainable revenue.
It also plans to work with venture capital firms and accelerator programmes to support portfolio companies after investment, helping translate funding into measurable commercial outcomes.
“Investors are very good at allocating capital. Accelerators are very good at identifying and preparing entrepreneurs. Insurers understand risk. Founders understand the problems they are solving. But there is still a question between all of them: who owns commercialisation?” Kavugwi said.
Doage is also developing what it describes as an Africa–Global InsurTech Corridor to connect African startups with international insurers, investors and technology companies, while supporting overseas insurance technology firms seeking to enter African markets through local partnerships instead of building operations from scratch.
According to AfricInvest, 86% of African InsurTech venture funding remains concentrated in South Africa, Kenya, Nigeria and Egypt, highlighting opportunities to expand insurance innovation into other markets across the continent.
Kavugwi, whose career spans insurance, bancassurance, embedded insurance, digital distribution and strategic partnerships, said the industry’s next phase should be measured by sustainable businesses rather than funding alone.
“The next phase of African InsurTech cannot only be about how many startups we accelerate or how much money we raise,” he said. “We also have to ask how many sustainable insurance businesses we build, how much revenue they generate, how many markets they enter and ultimately how much enterprise value they create.”
The Nairobi-based venture is betting that commercial execution, rather than access to capital alone, will determine the next generation of winners in Africa’s growing InsurTech market.
Google will begin withholding 5% from eligible YouTube earnings paid to Kenyan creators from September, with the company set to remit the deducted amount to the Kenya Revenue Authority (KRA) in line with the country’s tax requirements.
The withholding will apply to YouTube earnings processed through Google’s AdSense system for creators whose tax residence is Kenya. The deduction will be made before creators receive their payouts.
For a creator with KSh100,000 in eligible earnings, the 5% withholding would amount to KSh5,000, leaving KSh95,000 before any other applicable deductions.
Google has asked affected creators to provide a valid KRA Personal Identification Number through their AdSense accounts. The deadline for submitting a verified KRA PIN is Oct. 1, 2026.
Creators who fail to provide the required tax information could face restrictions affecting their payments.
The new withholding comes as Kenya increases its focus on income generated through the digital economy. YouTube has become an important revenue source for creators, with advertising, memberships and other monetisation tools supporting a growing ecosystem of online businesses.
The 5% withholding is not necessarily a creator’s final tax liability. Additional taxes may apply depending on a creator’s total income and individual circumstances.
For creators operating YouTube channels as businesses, the change could affect cash flow, revenue forecasts and production budgets. It also makes the distinction between gross YouTube revenue and actual take-home income increasingly important.
The move highlights the growing integration of global digital platforms into domestic tax systems, with Google effectively becoming part of the collection and remittance process for tax due on eligible creator earnings.
Tim Cook has finally stepped down as chief executive officer of Apple, bringing an end to nearly 15 years leading one of the world’s most valuable technology companies.
In a message to Apple employees on his final day as CEO, Cook reflected on his tenure, thanking the company’s employees and describing his time leading Apple as “the privilege of a lifetime.”
“Today is my last day as CEO of Apple,” Cook wrote. “I love this company and the team behind it, and I couldn’t let this day pass without sending a note to you, to tell you how grateful I am.”
Cook, who succeeded Apple co-founder Steve Jobs as CEO in August 2011, credited Apple’s employees for the company’s achievements during his tenure. He said whatever success was attributed to him was ultimately the result of the people he led.
“The truth is, whatever there is to say about my success, I know it is all because of you,” Cook said. “You have brought out the best in me.”
A leadership era comes to an end
Cook’s tenure has been defined by Apple’s expansion beyond the iPhone into a broader ecosystem of hardware, software and services. Under his leadership, the company launched products including the Apple Watch, AirPods and Vision Pro, while transitioning its Mac lineup to Apple-designed silicon.
The firm also significantly expanded its services business, with products including Apple Music, Apple TV+, Apple Pay, iCloud and other subscription offerings becoming increasingly important to the company’s growth. Cook also presided over the firm’s growing focus on privacy, environmental sustainability and artificial intelligence, including the company’s push into Apple Intelligence.
In his farewell message, however, Cook said the achievements that mattered most to him were not those captured in the firm’s financial reports.
“There is something truly special about Apple,” he wrote. “I am most proud of what an annual report could never capture. This place is proof that culture triumphs over everything.”
He said the firm’s culture is built around the belief that its products and work should make a meaningful difference in the world.
Cook will remain at Apple
Although Cook is leaving the CEO position, he emphasized that he is not leaving Apple.
“As you know, I am not leaving Apple. But I am stepping away from a role that I have loved deeply,” he wrote.
Cook said he would miss leading the company but remained at peace with the decision. He also expressed confidence in his successor John Ternus.
“I take enormous comfort in handing the helm to someone as brilliant and wonderful and capable as John,” Cook wrote. “Few people understand what it takes to build products that change the world the way John does and I could not be more excited for his leadership.”
The transition marks a significant moment for the firm as it enters a new phase of leadership while confronting intensifying competition in artificial intelligence, evolving consumer technology markets and continued regulatory pressure.
Cook is transitioning to executive chairman and will still be around the firm though not on a day-to-day basis. “With all I have and all I am, I am always yours,” he wrote. Cook became Apple’s CEO on August 24, 2011, succeeding Steve Jobs. His departure from the CEO role closes one of the longest and most consequential chapters in Apple’s modern history, while his continued presence at the company is expected to provide continuity as the new leadership team takes over.
Swedfund has provided a $20 million loan to the Africa Go Green Fund to invest in firms that reduce emissions and improve energy efficiency across Africa in areas such as green buildings, clean cooking, green transport and industrial energy efficiency.
According to Gunilla Nilsson, Investment Director and Head of Energy and Climate at Swedfund, “Energy efficiency is one of the most practical ways to reduce emissions while lowering costs. Through this investment, Swedfund will support companies providing solutions that people use in everyday life, from cleaner cooking to more energy efficient housing and transport.”
Energy demand in Africa continues to grow, while many companies in the energy efficiency space lack financing that matches their long-term investment needs. This limits the scale up of solutions that can reduce emissions, lower costs and improve the reliability of essential services.
The Africa Go Green Fund has already financed close to 30 projects across 17 countries in Africa and is expanding its lending activities to reach more companies providing energy efficiency solutions.
Swedfund’s investment will strengthen the fund’s capacity to provide financing to companies that can deliver significant climate benefits but often struggle to access debt on suitable terms. By investing alongside other public and private investors, Swedfund also helps mobilise additional capital for energy efficiency solutions across Africa.
Samsung has launched the Exynos 2600-powered Galaxy S26 FE in Kenya, bringing flagship AI features, upgraded cameras and seven years of software support to a more accessible price point.
Available from September 4, the smartphone is the first Fan Edition device to ship with One UI 9, offering AI-powered tools designed to boost productivity, photography and content creation.
“The Kenyan market represents one of the most vibrant mobile ecosystems on the continent, where technology serves as a vital engine for productivity, entrepreneurship and everyday communication,” said Manish Jangra, Head of Mobile Experience at Samsung Electronics East Africa.
Here’s the revised paragraph:
The Galaxy S26 FE is powered by Samsung’s next-generation Exynos 2600 processor, the processor on Galaxy S26 built on a 3nm architecture. It delivers improved AI performance, stronger graphics, enhanced camera processing and greater power efficiency, supporting smoother multitasking, gaming and everyday use.
The Galaxy S26 FE features a 6.7-inch Dynamic AMOLED 2X display with a 120Hz refresh rate, a 4,900mAh battery with 45W fast charging, and IP68 water and dust resistance. Samsung has also committed to providing seven Android OS upgrades and seven years of security updates, matching support offered on its flagship devices.
On the camera front, the phone includes a 50MP main sensor, 12MP ultra-wide camera and 8MP telephoto lens with 3x optical zoom. AI features such as Photo Assist, Gemini Omni, My FanCam and Super Steady with Horizontal Lock are designed to simplify editing and improve photo and video capture.
The 8GB RAM/256GB storage model will retail at KES 103,100 in Blueberry, Pistachio and Graphite. Kenyan buyers will also receive Samsung Care+, a six-month Google AI Pro subscription, and access to Smart Switch for easy data transfer from Android and iOS devices.
Terra Industries has appointed former WHOOP executive and Palantir alumnus Todd Stiefler as its Director of Commercial, strengthening its leadership team as the defense technology startup expands sales of its autonomous security systems across critical infrastructure markets in the Global South.
The appointment brings aboard an executive with experience scaling enterprise businesses and navigating government and regulated-sector customers. At Terra, Stiefler will help lead the company’s commercial division, focusing on customers that own and operate critical infrastructure.
Before joining Terra, Stiefler served as Vice President of Enterprise at wearable technology company WHOOP, where he oversaw business-to-business growth across government and defense, corporate wellness and other enterprise segments.
Earlier, he worked in business development at data analytics firm Palantir Technologies, helping build go-to-market teams for Apollo and FedStart, platforms aimed at accelerating adoption of software by defense technology companies and U.S. government customers.
Terra said Stiefler’s background in enterprise sales, commercial partnerships and regulated industries will support the deployment of its autonomous security systems in emerging markets.
The hire comes as Terra seeks to broaden its commercial footprint beyond product development, targeting operators of energy, transport and other critical infrastructure across Africa and the wider Global South.
The announcement also prompted questions from industry observers about whether Stiefler’s experience selling to U.S. government agencies would primarily help Terra pursue American customers or adapt those commercial strategies for sovereign buyers in emerging markets, where procurement processes differ significantly.
Terra has said its commercial strategy is centered on bringing autonomous security technologies to organizations responsible for safeguarding critical infrastructure in developing economies.
SBM Bank Kenya will provide $17 million in financing to Safer Power Group to expand local manufacturing of power infrastructure through the construction of a new factory and workshop, as the lender increases support for Kenya’s green industrial sector.
Safer Power, a licensed Schneider Electric panel builder, will use the funding to scale production of switchboards, control panels, distribution boards, synchronization panels and other electrical equipment used in commercial and renewable energy projects.
The investment comes as East Africa’s renewable energy market, valued at $4.3 billion in 2025 by IMARC Group, continues to grow on rising industrial demand. The International Renewable Energy Agency estimates that expanding clean energy and localized manufacturing could raise regional GDP by up to 6.4% while creating thousands of skilled jobs.
“Access to targeted capital is no longer just an ESG obligation. It is a necessary catalyst to unlock industrial resilience and energy sovereignty for our economy,” SBM Bank Kenya Chief Risk Officer Edgar Mwandawiro said.
Safer Power Chief Executive Officer Dalmus Mbai said the financing would help reduce dependence on imported equipment while supporting local engineering and manufacturing capacity.
The transaction aligns with SBM Bank’s strategy of increasing lending to businesses. The lender’s net loan book rose 18.3% year-on-year to KSh 54.09 billion at the end of June, surpassing KSh 50 billion for the first time as it expanded financing to micro, small and medium-sized enterprises.
East Africa has become one of the world’s most exciting frontiers for fintech innovation. From M-PESA’s invention in Kenya over fifteen years ago to the explosive growth of mobile wallets across Tanzania, Uganda, and beyond, the region has leapfrogged traditional banking infrastructure and built a digital payments ecosystem that now powers everything from remittances to retail commerce. One of the sectors feeling this shift most acutely is online sports betting — an industry that lives or dies by the speed, convenience, and trustworthiness of its payment rails.
For decades, the biggest barrier to online betting in East Africa wasn’t technology or appetite. It was friction. Players who wanted to place a bet had to navigate bank transfers, agent networks, or cash-handling systems that were slow, expensive, and often unreliable. A punter in Nairobi who wanted to back Gor Mahia on a Saturday afternoon might wait hours for a deposit to clear — if it cleared at all. That friction didn’t just frustrate users; it capped the entire market’s potential.
Mobile money changed everything. When M-PESA made it possible to move money with a few taps on a feature phone, it didn’t just create a new payment method — it created a new consumer behaviour. Kenyans learned to trust digital balances, instant transfers, and SMS confirmations. That trust became the foundation upon which entire digital industries could be built, including online betting.
Today, platforms like FungaBet are capitalising on that foundation by embedding mobile money directly into the betting experience. Instead of treating M-PESA as an add-on or a secondary option, modern betting platforms are building their entire deposit and withdrawal flows around it. A player can deposit via M-PESA in seconds, place a bet on the English Premier League or the FKF Premier League, and withdraw winnings back to their mobile wallet without ever touching a bank account. The entire cycle — deposit, bet, win, withdraw — happens within a closed loop of digital trust.
But the transformation goes beyond speed. Fintech has also made it possible to localise the betting experience in ways that were previously impossible. Platforms can now price in Kenyan shillings, offer Swahili-language interfaces, and tailor bonuses to local payment habits. A welcome bonus that requires a card deposit would exclude the vast majority of East African bettors. A bonus built around M-PESA —deposit via mobile money, get a 200% match — speaks directly to how people actually manage their money.
The rise of stablecoins and cryptocurrency is adding another layer. While mobile money dominates the mass market, a growing segment of tech-savvy East Africans are using USDT and other stablecoins for betting. This gives platforms a hedge against currency volatility, reduces transaction costs for high-volume players, and opens the door to cross-border betting without the friction of traditional foreign exchange. The most forward-thinking operators are now offering both M-PESA and USDT side by side, letting players choose the rail that suits them best.
Tanzania is the next frontier. While Kenya’s betting market is more mature, Tanzania’s mobile money ecosystem — driven by Vodacom’s M-PESA, Tigo Pesa, Airtel Money, and Halopesa — is equally robust. As platforms expand across borders, the ability to support multiple mobile money providers in multiple currencies becomes a competitive advantage. A betting platform that can accept Tigo Pesa in Dar es Salaam and M-PESA in Nairobi, settle in local currency, and manage liquidity across both markets is built for the reality of East African fintech.
Of course, growth brings responsibility. The same fintech rails that make betting accessible also make it easier to enforce responsible gambling measures. Digital-first platforms can set deposit limits, monitor patterns of problematic behaviour, and implement KYC (Know Your Customer) checks at registration — something that was nearly impossible in the cash-dominated era. The best operators are treating compliance not as a cost centre but as a trust signal. Players who know their platform is licensed, regulated, and actively monitoring for fraud are more likely to stay loyal.
The convergence of fintech and betting in East Africa is still in its early chapters. As smartphone penetration deepens, internet costs fall, and mobile money interoperability improves, the addressable market will only grow. The platforms that win will be those that treat payments not as plumbing but as product — designing every deposit, bet, and withdrawal around the real financial habits of East African users.
FungaBet is betting on exactly that vision: a platform built mobile-first, localised for East Africa, and powered by the payment rails that already move billions of shillings every day. The technology is ready. The market is ready. The only question is how fast the rest of the industry catches up.
Microsoft has appointed Angela Nganga as its Country Lead for East Africa, putting an experienced regional executive at the helm as the technology giant expands its focus on artificial intelligence, digital transformation and local innovation.
Nganga will lead Microsoft’s engagement with governments, businesses and technology stakeholders across Kenya and the broader East African region, with a mandate that includes expanding AI skills, supporting workforce readiness and strengthening partnerships across the region’s technology ecosystem.
“I am delighted to lead Microsoft’s work in East Africa as the region strengthens its position as an innovation and AI hub,” Nganga said. “I look forward to partnering with governments, enterprise and the local startup ecosystem to build AI skills and workforce readiness, and to help partners develop and scale locally relevant solutions to real-world challenges.”
She added that enabling East African companies to become producers as well as consumers of AI innovation will be critical to the region’s participation in the global digital economy.
Based in Nairobi, Nganga joined Microsoft in 2012 and has held several senior positions across the company’s Middle East and Africa business. Most recently, she served as Regional Director of Customer Success for East and West Africa.
Her previous roles include Director of Corporate Affairs for the Middle East and Africa and Education Industry Director for Africa, where she was involved in customer success, digital transformation and strategic engagements across the continent.
Nganga brings more than two decades of experience spanning technology, telecommunications, healthcare, public affairs and policy. Before joining Microsoft, she held senior corporate affairs and public policy positions at Telkom Kenya and AAR Health Services Ltd.
Her appointment comes as East Africa’s technology market enters a new phase of AI adoption, building on the region’s established strengths in mobile technology, fintech and digital services.
Microsoft said Nganga’s leadership will support its efforts to advance inclusive digital and AI transformation while deepening investment in local innovation, skills development and strategic partnerships.
The region’s young population and growing startup ecosystem have also created opportunities for technology companies to develop solutions tailored to local markets. For Microsoft, the focus increasingly extends beyond deploying technology to building the skills, partnerships and businesses needed to create it.
Nganga’s appointment therefore places regional leadership at the center of Microsoft’s broader AI strategy, as governments and businesses across East Africa look to use artificial intelligence to improve productivity, create new services and build globally competitive technology companies.
Microsoft said the appointment reinforces its commitment to East Africa’s role in the global digital economy.
Afrikrea is returning as the consumer-facing marketplace for African and diaspora fashion, art and crafts, while parent company ANKA focuses its other products on business-to-business commerce services.
The move marks the 10th anniversary of Afrikrea, which was founded in 2016 to connect independent creators across Africa and the diaspora with customers around the world.
Under the new structure, Afrikrea will be the platform where consumers shop, while ANKA Pay and ANKA Ship will serve as B2B software products. The company said the relaunch restores the original brand as it renews its focus on its founding mission.
“Fashion is where culture, craft, and commerce meet. Throughout my career, I have seen that the strongest businesses begin with a distinct creative point of view,” said Matilda Ceesay, CEO. “Afrikrea is returning to the name that carries that point of view: a home for African and diaspora creators whose work deserves to be seen, valued, and built into enduring businesses.”
Since its launch, Afrikrea has generated more than $30 million in sales for creators, giving the marketplace a decade-long track record in connecting African and diaspora businesses with international consumers.
The platform now connects creators in 94 countries, including 39 African countries, with buyers across 185 markets. More than 74% of its creators are women-led businesses, with consumers concentrated primarily in Europe and North America.
Afrikrea has also built a sizeable audience around its marketplace, with more than 700,000 community followers and 49,000 newsletter subscribers. Its physical pop-up events have generated hundreds of thousands of dollars in sales in less than a week, while the platform has recorded more than 125,000 five-star orders.
The restructuring separates Afrikrea’s consumer marketplace from the technology infrastructure built around it under ANKA. That allows the original Afrikrea identity to focus on shoppers and creators, while ANKA Pay and ANKA Ship remain positioned as tools for businesses handling payments and shipping.
The relaunch comes as African creators and small businesses increasingly use digital commerce and cross-border platforms to reach customers outside their domestic markets. For Afrikrea, that international connection has been central to its business since its founding.
The company said the next phase of Afrikrea will remain focused on helping independent creators reach global consumers, with the belief that where a creator starts should not determine how far their business can go.
I’ve been tracking Africa’s digital entertainment evolution for 18 years, and the transformation still catches me off guard. Back in 2007, I remember trying to load a single YouTube video and giving up after 47 minutes. Fast forward to today and we’ve got sophisticated virtual platforms processing millions of transactions daily across the continent.
Nobody saw it coming this fast.
Here’s what I found fascinating: everyone got distracted by social media and streaming wars, but virtual gaming quietly built massive infrastructure underneath everything. I’m talking about platforms mixing sports simulation with instant-play formats and real-time engagement, all running on devices everyone already carries.
The Technology That Made It Possible
Mobile penetration reached 83% across sub-Saharan Africa by late 2023. I spent months looking at payment trends, and something jumped out: mobile money transactions surged 34% year-over-year, with huge portions coming from entertainment and gaming platforms.
You can’t tell the story of online casino platform growth without talking about Africa’s fintech revolution because they’re basically the same phenomenon happening simultaneously. Better payment infrastructure opened digital entertainment to millions who never touched credit cards or traditional banks.
Why Virtual Beats Traditional Every Time
Last month I sat down with operators in Nairobi and Harare. Every single one told me the same thing: virtual products solve real problems that physical venues simply can’t address. No closing times. Zero travel requirements. No waiting for weekly events.
Virtual sports cycle every 2 to 3 minutes. Racing simulations, football matches, basketball games—they run continuously. Someone in Lusaka engages with identical content as someone in Johannesburg, even at 2:47am on a random Tuesday.
Accessibility isn’t some minor feature. It’s literally the entire value proposition.
What The Numbers Show
Southern Africa saw virtual gaming revenue jump 127% between 2021 and 2024, confirmed across three separate regulatory reports. Kenya showed similar patterns. Nigeria too.
But official reports completely miss the social dimension that’s developed. People aren’t isolated users clicking alone. They’re actively sharing strategies, debating outcomes, forming communities centered on preferred virtual sports. I’ve joined WhatsApp groups with over 200 members who analyze virtual football patterns and discuss tactics.
Calling that simple gambling misses the point entirely.
The Regulatory Picture Gets Clearer
African governments struggled for years figuring out their approach to digital gaming. But I’ve tracked a clear trend toward establishing proper licensing frameworks instead of knee-jerk prohibition. Zimbabwe overhauled regulations in 2023. Tanzania implemented changes six months after. South Africa’s been continuously refining their system since 2019.
Solid regulations benefit everyone. Operators understand expectations. Players gain confidence they’re using legitimate platforms. Tax revenue gets collected appropriately.
Infrastructure Keeps Improving
I remember when 3G felt like living in the future. Now we’re installing 5G towers across major African cities while 4G coverage extends to 67% of the population. Virtual platforms don’t require bleeding-edge speeds, but reliability matters tremendously.
Payment processing evolved even faster than connectivity. M-Pesa, Airtel Money, MTN Mobile Money—they’ve transformed into the fundamental backbone of digital transactions continent-wide. When you can complete a deposit in 12 seconds using the system you buy airtime with, friction evaporates.
NCBA Group and electric mobility company BasiGo have partnered to finance 1,000 electric vehicles in Kenya, expanding access to leasing as public transport operators and businesses seek to overcome the high upfront cost of switching to electric fleets.
The partnership will enable PSV SACCOs, established transport operators and institutions including schools and hospitals to access financing for BasiGo electric vans through asset finance and leasing. BasiGo will use the financing to scale production and lease vehicles to operators and individuals.
The deal makes NCBA the first local investor to finance BasiGo and adds one of Kenya’s largest banks to the capital providers supporting the country’s growing electric mobility sector.
Existing PSV SACCOs and established PSV companies can access financing of up to 90% of an electric vehicle’s value over 60 months, while individual SACCO members can finance up to 80% over 48 months. Both options carry a discounted processing fee of 1.5%.
NCBA and BasiGo are also combining the bank’s financing with BasiGo’s Pay-As-You-Drive model, allowing operators to spread payments over time rather than absorb the full cost of an electric vehicle upfront.
“The most critical challenge in scaling electric vehicles in Africa is financing,” said Jit Bhattacharya, CEO and co-founder of BasiGo. “We are proud to partner with NCBA to address this problem head on for operators through affordable and creative financing solutions.”
For transport operators, the financing model could reduce the capital barrier to electric vehicles while offering potential savings on fuel and maintenance costs over the life of the vehicle.
“The transition to electric mobility is not simply about putting more electric vehicles on the road; it is about creating the financing and infrastructure needed to make them commercially viable at scale,” said Lennox Mugambi, Group Director of Asset Finance and Business Solutions at NCBA Group.
The partnership forms part of NCBA’s KES 2 billion e-mobility financing program. The bank said it has already invested more than KES 800 million in sustainable mobility assets, equivalent to about 40% of the facility.
The remaining KES 1.2 billion gives NCBA further capacity to finance electric mobility projects as demand for electric vehicles grows.
For BasiGo, the deal expands the financing options available to operators as the company seeks to move electric public transport beyond early adoption. The Nairobi-based company introduced electric buses into passenger operations in Kenya in 2022 and has built its business around providing vehicles, charging and maintenance services alongside its Pay-As-You-Drive financing model.
The partnership signals a broader shift in Kenya’s electric mobility market, with financing becoming as important as the vehicles themselves. By combining traditional bank lending with leasing and usage-based payments, NCBA and BasiGo are seeking to make electric fleets accessible to operators that may not have the capital to purchase them outright.
The success of the 1,000-vehicle target will ultimately depend on whether these financing structures can move electric mobility from early adopters into Kenya’s mainstream commercial transport market.
Samsung gained market share in the Middle East and Africa during the second quarter as a 10% decline in regional smartphone shipments and a memory-component shortage squeezed manufacturers concentrated in the entry-level segment.
Smartphone shipments across the Middle East and Africa fell 10% year over year in the second quarter of 2026, according to Counterpoint Research, with the market lacking a major sales-driving occasion during the period. The decline was uneven across manufacturers, with Samsung, realme and Apple recording significant growth even as several rivals lost share.
The result marks a shift in a market historically driven by affordable smartphones. With overall demand declining, Samsung’s gains largely came at the expense of competing manufacturers rather than from an expansion of the total market.
“Every unit Samsung gained came out of Infinix, TECNO and Xiaomi’s shares,” Counterpoint said, highlighting the scale of the competitive shift.
Samsung’s performance was supported by its Galaxy A07 and A17 models, as well as its recently launched Galaxy S26 flagship lineup. The combination gives the company exposure across both mass-market and premium price segments at a time when supply constraints are changing the economics of the smartphone industry.
Budget Phones Take the Biggest Hit
The sharpest pressure was concentrated at the bottom of the market.
Smartphone shipments priced below $250 declined 26% year over year in the second quarter, the steepest decline among all price bands, according to Counterpoint. The segment’s contraction weighed heavily on the overall MEA market because entry-level devices account for a significant share of smartphone volumes across the region.
The decline is closely linked to the ongoing memory-component shortage. Manufacturers facing constrained and more expensive memory supplies have been forced to prioritize higher-margin devices, reducing the availability of lower-priced models.
“The memory crisis hit the market hard, though unevenly,” said Ahmad Shehab, an analyst at Counterpoint Research.
“Transsion and Xiaomi were hit hardest,” Shehab said, because their sales volumes are concentrated in the entry-level segment, which is particularly exposed to the increase in memory costs.
That dynamic puts brands such as Infinix and TECNO, which are part of Transsion’s portfolio, under greater pressure in a market where affordability has traditionally been a major driver of smartphone adoption.
5G Moves in the Opposite Direction
While overall smartphone shipments declined, 5G shipments in MEA increased 8% year over year during the quarter.
That compares with global 5G smartphone shipment growth of only 1%, according to Counterpoint. The regional increase reflects both the relatively low 5G base in the second quarter of 2025 and the continued expansion of 5G networks and supporting policies across MEA.
Samsung and Apple were the primary contributors to the region’s 5G growth.
The divergence between total smartphone shipments and 5G shipments illustrates the changing composition of the market. Consumers are not necessarily rushing to buy more smartphones, but a greater share of the devices being sold are connected to newer networks and positioned higher up the technology and price curve.
For manufacturers, that creates an unusual form of premiumization.
The market is becoming more expensive not simply because consumers are demanding higher-end devices, but because component shortages are making it harder and less attractive for manufacturers to maintain aggressive volumes at the lowest price points.
Samsung Benefits From the Shift
Samsung is well positioned for that transition because its portfolio spans entry-level Galaxy A models through premium Galaxy S devices.
Its ability to serve multiple price points means the company can capture demand displaced by competitors while also benefiting from growth in higher-value smartphones.
The second-quarter results therefore give Samsung more than a temporary boost in market share. They could strengthen its competitive position if the supply constraints continue and consumers become accustomed to a market with fewer choices below $250.
Counterpoint said the gains made by Samsung, realme and Apple could make it more difficult for declining brands to recover their lost share because the market did not generate enough additional demand for every manufacturer to grow simultaneously.
That creates a potentially more durable competitive advantage for the companies that were able to maintain supply during the downturn.
Realme Turns Supply Into a Competitive Weapon
Realme’s performance provides another example of how manufacturers are responding to the constrained market.
The company expanded its presence in MEA even as its global smartphone shipments declined 23% year over year in the second quarter.
Rather than securing entirely new supply, realme allocated significantly more units to MEA, diverting supply from markets including India and China.
The strategy allowed the company to take advantage of demand that was left underserved as other manufacturers struggled with component constraints.
It also highlights a broader change in smartphone competition: in a supply-constrained market, market-share growth can increasingly depend on where manufacturers choose to send their available inventory.
For realme, MEA’s budget-oriented market became a strategic destination for that supply.
A Structural Shift for MEA’s Smartphone Market
The second-quarter results point to a smartphone market undergoing more than a temporary slowdown.
MEA’s traditional dependence on entry-level smartphone volumes is colliding with higher component costs and limited memory supply. The result is a market where the lowest price segment is shrinking rapidly while 5G and higher-priced devices gain ground.
Counterpoint expects the second quarter to be the weakest quarter of 2026, with the memory crisis adding to the impact of the shift in the Islamic calendar, which concentrated major first-half sales occasions in the first quarter.
For Samsung, the downturn has created an opportunity to widen its lead.
For Transsion and Xiaomi, the challenge is more difficult. Their exposure to entry-level volumes makes them particularly vulnerable when manufacturers have to ration scarce components toward more profitable devices.
The competitive landscape could therefore look different even after the memory shortage eases. Brands that lose distribution, shelf space and consumers during the downturn will have to spend to win them back, while Samsung can use its broader ecosystem and product portfolio to retain customers who move into higher-priced devices.
The central question for MEA’s smartphone industry is no longer simply how many phones consumers will buy. It is increasingly which manufacturers can secure enough supply, at which price points, and in which markets. For the second quarter, Samsung had the stronger answer.
HassConsult is betting that wellness and community-driven living can become a bigger source of value in Kenya’s residential property market, as a global wellness real estate sector worth $876 billion increasingly reshapes how developers design, market and operate homes.
The Nairobi-based developer is expanding its Enaki model with Elevate by Hass, a resident experience platform built around fitness, wellness, dining, entertainment, work and community programming. The move comes as the global wellness real estate market, one of the fastest-growing segments of the broader wellness economy, is projected to reach $1.8 trillion by 2030.
For HassConsult, the opportunity is increasingly being measured in property performance.
Enaki’s first phase of 440 apartments is 92% occupied, with waitlists for several fully occupied unit types, according to the developer. Its next phase, Enaki Forestside, has sold 50% of its homes within four months of launch.
Those figures give HassConsult an early commercial case for a strategy that treats resident experience as more than an amenity.
“The traditional measures of residential value, location, size, specification, are no longer the full picture. When residents genuinely belong to where they live, it shows up commercially,” said Farhana Hassanali, co-CEO and development director at HassConsult.
The company’s approach reflects a broader shift in wellness real estate. The Global Wellness Institute’s latest research shows the sector grew from $151 billion in 2017 to $876 billion in 2025 and is forecast to more than double to $1.8 trillion by 2030. The sector has been growing substantially faster than overall construction, making wellness-focused development an increasingly important part of the global property industry.
The shift is also changing what developers mean by wellness.
Rather than focusing only on gyms, swimming pools or landscaped gardens, newer wellness-oriented developments are incorporating physical health, mental wellbeing, social connection, access to nature and programming into the way communities operate.
HassConsult is attempting to bring that model to Nairobi through Enaki, which it describes as a residential resort built around green space and community life. The development spans 22 acres and includes a six-acre botanical garden, while the Forestside phase is centered around a 23,000-square-foot private forest.
Elevate by Hass is intended to turn those physical assets into an ongoing resident experience.
The platform brings together fitness and gastronomy, wellness and work, children’s activities, resident events and entertainment. HassConsult says the objective is to create reasons for residents to use shared spaces regularly rather than treating amenities as facilities that sit largely idle between property viewings and occasional use.
At Enaki Town, a purpose-built movement studio provides space for fitness and wellness programming, while Artcaffé operates a marketplace designed as a social hub. The venue has hosted high teas, children’s baking competitions and cultural festivals.
That operating model is significant because HassConsult is seeking to stay involved in the development beyond the traditional property-sales cycle.
The company says its model brings together market research, development, design, pricing, marketing, sales, letting and property management. Elevate adds another layer: actively managing the experience residents have after they move in.
That could give developers a new way to differentiate projects in a market where residential developments increasingly compete on similar features such as security, parking, gyms, pools, gardens and proximity to commercial centers.
The question for the industry is whether the additional investment in programming and community infrastructure can translate into measurable commercial returns through faster sales, higher occupancy, stronger rental demand and potentially greater long-term property values.
Enaki’s early numbers offer some evidence of demand, although they do not by themselves establish that resident programming caused the development’s occupancy or sales performance.
The 92% occupancy rate across Enaki’s 440 completed apartments means the project has already absorbed much of its available residential inventory. Forestside’s 50% sales rate in its first four months provides a second indicator of buyer interest as HassConsult expands the concept.
The company is now scaling the model beyond the original Enaki experience.
“The design brief of the future has to include human connection as an outcome. What draws people out of their homes and keeps them coming back cannot be left to chance. It must be designed, programmed and sustained,” said Sakina Hassanali, co-CEO and creative director at HassConsult.
For Kenya’s property industry, the bigger opportunity may be the economics of what happens after a home is sold.
As developers increasingly compete on lifestyle, the value proposition may shift from simply selling square meters to creating communities that residents want to remain part of. That would give developers a commercial incentive to operate and program residential developments long after construction is complete.
HassConsult’s expansion of Elevate suggests it sees that shift as more than a marketing trend.
With a global wellness real estate market already at $876 billion and projected to reach $1.8 trillion by 2030, the company is positioning its Nairobi developments to capture a small but potentially valuable part of a rapidly expanding property category.