Home Blog Page 3

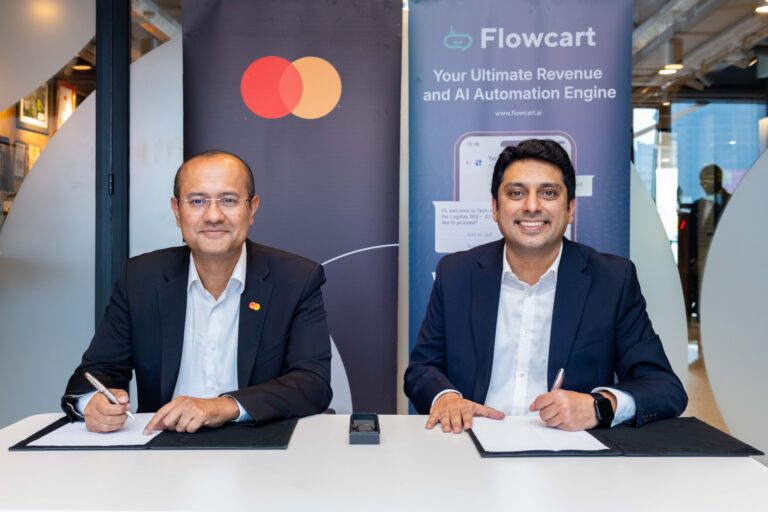
Mastercard, Flowcart Launch WhatsApp Payments to Power Social Commerce in Kenya

Mastercard and Flowcart have launched chat-to-pay offerings to allow secure, seamless card payments directly within social and conversational commerce journeys.

Initially launching in Kenya, the collaboration will expand across East Africa and into key high-growth markets including South Africa, Nigeria and Côte d’Ivoire, supported by broader scaling across pan-African markets.

According to Shehryar Ali, senior vice president and country manager for East Africa and Indian Ocean Islands at Mastercard, “Social commerce is redefining how consumers discover and engage with brands. Our collaboration with Flowcart enables us to embed secure, seamless payments directly into these experiences, unlocking new growth opportunities for merchants and expanding digital payment acceptance in one of Africa’s fastest-growing digital economies.”

The deal will allow consumers to discover products, place orders and complete payments within a single chat-based journey, eliminating the need to redirect users to external websites or apps. WhatsApp alone now handles over 20% of all online shopping orders in the country, officially surpassing traditional e-commerce websites as conversational commerce gains dominance.

By combining Flowcart’s AI-powered commerce orchestration platform with Mastercard’s global payment network, the collaboration enables merchants to capitalize on this growing trend to increase transaction frequency, drive repeat purchases and expand acceptance into underserved and informal commerce segments.

The solution is designed to support Kenya’s rapidly growing creator economy, empowering social sellers to monetize their audience directly within the platforms where they engage them. By enabling a complete “chat-to-pay” loop, from discovery to repeat purchase, the agreement removes friction and helps merchants increase conversion rates. Payments are completed within the conversation using embedded links, QR codes or native checkout flows powered by Mastercard Gateway and its network of acquiring partners.

Mastercard Gateway enables merchants to simplify payment acceptance through a single connection, streamline operations, and create secure, seamless commerce experiences across markets and channels.

Ananth Gudipati, Founder at Flowcart, said: “We are excited to collaborate with Mastercard to transform how businesses transact in social channels, whether that’s an independent social seller, a fast-growing SME or a large enterprise brand running WhatsApp as a core commerce channel. Together, we are enabling a future where commerce and payments happen seamlessly within conversations, driving higher conversion, repeat purchases and meaningful growth for merchants.”

For consumers, the initiative provides a secure and intuitive in-chat payment experience, while tokenized card details ensure frictionless repeat purchases. For merchants, from small social sellers to large enterprises, it simplifies digital commerce without requiring websites or traditional point-of-sale systems.

The 2026 Mastercard SME Confidence Index revealed, 80% of Kenyan SMEs identify simple, seamless and user-friendly payment methods as a top requirement for future growth. By digitizing informal and creator-led commerce, Mastercard and Flowcart are positioning social and messaging platforms as a dependable, end-to-end channel for digital payments and long-term customer growth.

ARC Ride Raises $33.3 Million to Expand Electric Mobility Network in Africa

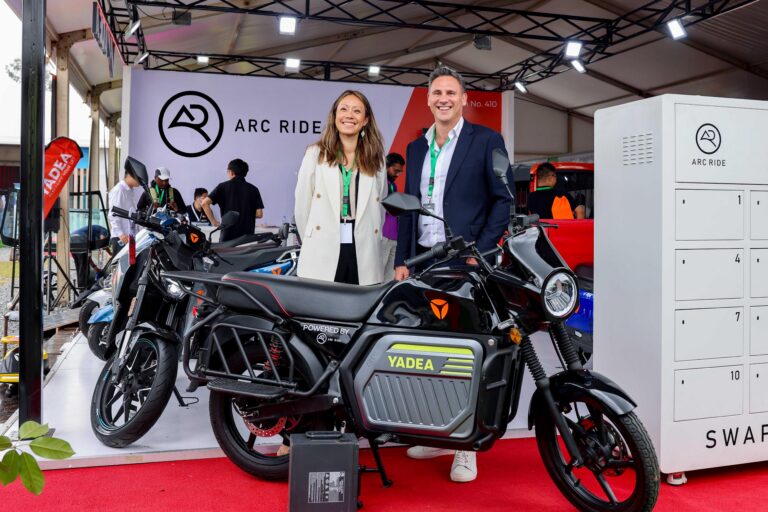
Electric mobility company ARC Ride has raised $33.3 million from venture capital firms, development finance institutions and impact investors as it seeks to expand battery-swapping infrastructure and electric two- and three-wheelers across Africa.

The financing was led by Novastar Ventures and Norrsken22, with the International Finance Corp., British International Investment and Proparco participating. Existing investors Musashi Seimitsu Industry Co., a Japanese automotive supplier, and African impact investor Talanton also committed additional capital.

The round includes debt from BII’s Kinetic program and Mirova, giving ARC Ride a mix of equity and asset-backed financing to fund what is a capital-intensive expansion.

ARC Ride plans to use the funding to expand its operations in Kenya and enter or scale in markets including Ghana, South Africa, Tanzania and Uganda. The company also plans to add 5,000 electric motorcycles to its fleet.

The Nairobi-based company operates a Battery-as-a-Service model in which riders can exchange depleted batteries at swap stations rather than purchase and maintain the batteries themselves. The approach is designed to reduce the upfront cost of switching from petrol-powered motorcycles while limiting downtime for commercial riders.

ARC Ride says its battery-swapping network is used by electric-vehicle manufacturers including Yadea.

The company is targeting Africa’s large motorcycle and three-wheeler markets, where motorcycles are a critical part of urban transportation and informal logistics but also contribute significantly to fuel consumption and air pollution.

ARC Ride will also invest in battery lifecycle management, network reliability, automated battery swapping, smart charging and integration of renewable energy.

“This funding reinforces our vision of building a robust, scalable energy and mobility network across Africa,” founder Jo Hurst Croft said in a statement. The company aims to make electric mobility more accessible and affordable than petrol alternatives, she said.

The investment comes as electric-mobility companies across Africa seek to solve the infrastructure and financing challenges that have slowed adoption of electric motorcycles. Battery swapping has emerged as an alternative to conventional charging, particularly for commercial riders who cannot afford long periods of vehicle downtime.

For investors, ARC Ride’s combination of vehicle financing, battery infrastructure and energy services offers exposure to several parts of the emerging electric-mobility market.

“ARC Ride is helping solve one of the biggest barriers to electric mobility in Africa: reliable, extensive battery-swapping infrastructure,” said Steve Beck, co-founder and managing partner at Novastar Ventures.

Norrsken22 partner Ngetha Waithaka said ARC Ride’s technology, data and network could give it the potential to become an open platform for the wider electric-mobility ecosystem.

ARC Ride’s expansion will initially deepen its presence in Kenya, including Nairobi and the western region, before extending its infrastructure footprint across additional African markets.

BII, one of the investors in the round, said the investment supports its climate strategy while helping build infrastructure needed for electric-vehicle adoption.

“Electric mobility is essential to building cleaner, more sustainable transport across Africa,” said Chris Chijiutomi, BII’s managing director and head of Africa.

ICON Corporate Finance acted as ARC Ride’s sole financial adviser on the transaction.

The latest financing gives ARC Ride additional capital to scale its network while testing whether battery swapping can achieve the operational efficiency and economics required for mass-market electric mobility in Africa.

IFC Proposes $40 Million Camco Fund Investment to Boost Renewable Energy in Africa

The International Finance Corporation (IFC) has proposed to invest $40 million in Camco Renewable Energy Performance Platform 2 (REPP 2), a private debt fund focused on financing renewable energy projects across sub-Saharan Africa.

The proposed investment will be made through REPP 2’s senior debt tranche and is subject to approval. The IFC’s Board is scheduled to review the transaction on November 6, 2026.

REPP 2 is managed by Camco, a UK-based climate and impact investment manager, and is targeting a range of small and medium-sized renewable energy projects across East, West and Southern Africa.

The fund will provide financing of between $2 million and $15 million for projects at late-stage development or construction, as well as selected corporate financing.

What REPP 2 will finance

The fund will focus on decentralised renewable energy projects, including off-grid solar, mini- and metro-grids, isolated grids, commercial and industrial energy systems, and small independent power producers (IPPs).

REPP 2 has a target fund size of $250 million and uses a blended-finance structure comprising junior equity, senior equity and senior debt.

The IFC’s proposed $40 million commitment would provide financing through the senior debt portion of the structure.

Focus on Africa’s energy gap

The investment comes as demand for reliable and affordable electricity continues to grow across Africa, while many communities and businesses remain underserved by traditional power grids.

Decentralised energy systems such as solar mini-grids and off-grid installations can provide an alternative to conventional grid infrastructure, particularly in areas where extending national electricity networks is expensive or difficult.

For businesses, renewable energy can also provide a more predictable source of power while reducing exposure to fuel and electricity costs.

Projects across three African regions

REPP 2 plans to invest across East, West and Southern Africa, with no single region expected to account for more than 60 percent of the portfolio.

The fund’s investments will be limited to countries that meet the eligibility requirements set out in its legal documentation.

The proposed IFC investment also aligns with the broader Mission 300 initiative, led by the World Bank Group and African Development Bank, which aims to connect 300 million people in Africa to electricity by 2030.

The proposed investment adds to the growing involvement of development finance institutions in Africa’s renewable energy sector.

REPP 2 has attracted backing from institutions including the Green Climate Fund, Norfund, FMO, BIO and OeEB, helping to bring additional capital into the continent’s decentralised energy market.

For Camco, the financing could provide additional capacity to support smaller renewable energy projects that often struggle to secure long-term funding.

For Africa’s energy sector, it highlights the growing role of institutional and private capital in financing the clean-energy infrastructure needed to expand electricity access.

If approved, the IFC’s $40 million investment would give REPP 2 additional firepower to finance renewable energy projects across Africa, particularly in the decentralised energy market

M-KOPA Hits 10,000 Electric Motorbike Financing Milestone in Kenya

M-KOPA has financed more than 10,000 electric motorcycles in Kenya, marking a new milestone for the fintech’s electric-mobility business as it expands into financing electric tuk-tuks.

The company said its financed motorcycle riders save an average of KSh530 ($4.10) a day through lower energy and maintenance costs and access to battery-swapping infrastructure.

Across 10,000 motorcycles, that represents about KSh5.3 million in potential daily savings, according to M-KOPA’s customer data.

“Reaching 10,000 financed electric motorbikes reflects growing demand from riders looking to lower operating costs and improve their earnings,” Brian Njao, general manager of Mobility at M-KOPA, said in a statement.

“We are now applying the same financing approach to electric tuk-tuks, helping operators access cleaner, lower-cost vehicles without the burden of a large upfront payment.”

The expansion takes M-KOPA into a larger segment of Kenya’s commercial-transport market, where tuk-tuks are widely used to carry passengers and goods.

The Kenya Tuk Tuk Operators Network estimates the country has more than 250,000 registered tuk-tuks, 750,000 active drivers and about 250,000 owners and investors.

For M-KOPA, the opportunity is to apply its pay-as-you-go financing model to another income-generating asset. Instead of requiring operators to pay the full cost of an electric vehicle upfront, the company spreads payments over time.

M-KOPA finances electric motorcycles from manufacturers including Ampersand, Roam and Spiro, and has partnered with Bolt to expand access to electric motorcycles among ride-hailing drivers.

The company says its mobility customers also receive insurance, GPS tracking, security features, flexible repayments and warranty protection.

The expansion comes as Kenya strengthens incentives for electric mobility. The country’s tax framework provides zero-rating for specified electric vehicles and lithium-ion batteries, while government policy is encouraging investment in electric-vehicle manufacturing, assembly and charging infrastructure.

For commercial operators, however, the transition is ultimately an economic calculation. Electric vehicles can reduce fuel and maintenance expenses, but the savings have to outweigh financing and energy costs while keeping the vehicle productive.

M-KOPA’s latest figures contain one discrepancy. The company’s KSh5.3 million estimate in daily savings would amount to about KSh1.93 billion a year if sustained for 365 days, rather than the approximately KSh1 billion annual figure cited in its announcement. The company did not explain the difference, which could reflect vehicle utilisation assumptions.

The tuk-tuk expansion will provide another test of whether financing can make electric commercial transport economically viable for operators who depend on their vehicles for daily income.

M-KOPA’s strategy increasingly positions the company not simply as a lender for electric vehicles, but as a financing layer connecting vehicle manufacturers, mobility platforms and the workers who use those vehicles to earn a living.

Zoho Targets AI Coding Bottleneck With Agent-Ready Catalyst Cloud Platform

0

Zoho Corporation is expanding Catalyst, its cloud platform for building and deploying applications, with tools designed to let AI coding assistants perform more of the work involved in taking software from generated code to production.

The company said Monday that Catalyst by Zoho now supports Agent Skills, a non-interactive command-line interface and Model Context Protocol (MCP), alongside integrations with AI coding tools including Anthropic’s Claude Code and OpenAI’s Codex.

The move comes as AI coding assistants increasingly automate software development, shifting a growing part of the challenge from writing code to testing, deploying, managing and governing applications once they are built.

Zoho is positioning Catalyst as the infrastructure layer for that process. Rather than requiring developers to assemble separate services for functions, databases, hosting and AI capabilities, the platform provides those components within a serverless environment.

“With AI coding assistants, applications can be created very quickly, but moving that code into production reliably remains a challenge,” said Veerakumar Natarajan, Country Head, Zoho Kenya. “With Catalyst, we are reducing that friction by providing an agent-ready, serverless full-stack platform that helps developers build, deploy and scale intelligent applications with greater control and less operational overhead.”

From AI-Generated Code to Deployment

AI coding tools have made it easier for developers to generate application code, but the resulting software still needs infrastructure, deployment workflows and operational controls before it can be used in production.

Catalyst Agent Skills are designed to give coding assistants information about Catalyst’s services, architecture and recommended development practices. Zoho says the skills help AI agents understand which Catalyst services to use and how to work with them.

The platform’s non-interactive CLI is designed to allow AI coding assistants to execute multiple Catalyst operations without requiring developers to provide manual input at every step.

MCP support takes the integration further by allowing compatible AI development environments to interact directly with Catalyst capabilities.

Developers can, for example, perform database operations and other platform tasks from their existing AI development environments rather than repeatedly switching between their coding environment and the Catalyst console. Zoho’s Catalyst MCP documentation explains how developers can connect compatible AI clients to Catalyst.

Zoho said orchestration within Agent Skills can route requests through the appropriate CLI or MCP workflow, reducing the possibility of an AI assistant selecting the wrong tool or process.

The company has also made the Agent Skills repository open source and said it is open-sourcing Catalyst’s SDK, CLI and Slyte JavaScript framework.

Human Oversight Remains Part of the Workflow

The increased role of AI agents in software development has also raised questions about how much autonomy should be given to automated systems, particularly when they have access to production infrastructure.

Zoho said Catalyst maintains a separation between development and production environments. Code must be promoted to production manually, preventing AI agents from directly accessing production environments.

The platform also provides scoped collaborator controls, allowing organizations to determine who or what can participate in development and which actions they can perform.

Audit trails record application activity, platform activity and MCP tool calls, while changes made after launch are versioned and can be attributed, tracked and reversed, according to Zoho.

Applications running on Catalyst are hosted in Zoho’s own data centers and use the company’s security infrastructure, including distributed denial-of-service protection, SOC compliance, vulnerability assessments, penetration testing and a web application firewall.

For software companies and system integrators, those controls could become increasingly important as AI agents move beyond code generation and begin executing operational tasks on behalf of developers.

Free Access for Students

Alongside the new agentic development capabilities, Zoho is removing the cost barrier for students using Catalyst to build non-commercial applications.

Students can deploy applications without a subscription or credit card and receive access to Catalyst’s full-stack development capabilities, including hosting, functions, databases and AI tools.

Catalyst’s student program is aimed at giving students practical experience building and deploying complete applications rather than limiting their exposure to writing code.

Zoho says students can use Catalyst for qualifying non-commercial projects at no cost, with up to $250 in usage over six months. Students are not automatically charged if they reach that threshold; they can request additional free usage if their projects qualify.

For other developers, Catalyst offers a monthly free tier and a pay-as-you-go pricing model, with individual features charged according to usage rather than through an additional software license.

Developers can monitor usage through the Catalyst console and set budget alerts and spending ceilings. A subscription option is also available for teams seeking more predictable costs.

Catalyst is available for immediate use.

The broader strategy reflects a shift in cloud computing as AI coding tools reduce the time required to produce software. As code generation becomes increasingly commoditized, cloud providers and platform companies are competing to control the infrastructure, deployment, security and governance layers that determine how that software reaches users.

For Zoho, Catalyst’s integration with AI coding assistants is an attempt to position its cloud platform within that emerging workflow, while retaining human approval over the final transition to production.

Uber’s Exit From Nigeria and Uganda Tests the Economics of Ride-Hailing

Uber last week announced it had withdrawn from Nigeria and Uganda with immediate effect creating an illusion that it was giving more room to its competitors such as Yango, inDrive, Bolt, Little among other local operators, but the economics of multi-homing, thin margins and the rise of electric and autonomous mobility make a simple handover unlikely.

From a simplisitic perspective, Uber’s exit from Nigeria and Uganda creates an obvious opening for its rivals such as Bolt, inDrive, LagRide, Rida and Shuttlers in Nigeria and Yango, Bolt, SafeBoda and Faras in Uganda. But it also exposes a more complicated reality about Africa’s ride-hailing industry. The departure of a major platform does not necessarily mean another company gets to inherit its market.

Uber ended its operations in Nigeria and Uganda on September 2, 2026, after 12 years in Nigeria and roughly a decade in Uganda. The company said the decision followed a review of its business operations and priorities, without providing detailed reasons. Though Nigerian authorities are looking into it, ride-hailing platforms do not operate in a vacuum. Apart from the presence of formidable alternatives, they face rising fuel costs, inflation, currency volatility, erratic human behaviours, higher operating expenses and increasingly intense competition.

For some, the obvious question is who gets Uber’s customers but that question assumes that Uber driver-partners were not already on other platforms and had captive customers who are now opharned.

Drivers can operate more than 5 apps at the same time

Unlike social networks or enterprise software, where users can become deeply locked into a particular platform, ride-hailing has relatively low switching costs. Drivers can operate several applications at the same time, passengers have multiple apps on their phones and choose whichever platform depending on prestige, price, availability, convenience or safety. Uber, for example is known for premium and safety services and is perceived civilised and reasonable. But most driver-partners operate on all major platforms, only that the training, culture and repercussions or loopholes are different.

Uber’s exit therefore means the same number of drivers are still left in the market with one-less source of trips. As Uber leaves, its drivers will now have to be redistributied across other platforms. Hence, there is no winner-takes-all businesses even though there is undoubtedly a substantial business to fight over.

According to Mordor Intelligence’s Africa ride-hailing market report, Africa’s ride-hailing market is expected to be worth $2.64 billion in 2026, up from $2.53 billion in 2025, and is projected to reach $3.25 billion by 2031, representing a 4.25% compound annual growth rate. The research estimates that motorcycles accounted for 52.45% of 2025 market revenue, while electric two-wheelers are expected to grow at an 11.45% CAGR through 2031.

Those numbers explain why Uber’s departure matters but also open a can of worms. How much of this $2.64 billion actually becomes profit? The number of rides, drivers or downloads are not close to what a firm is looking for as revenue does not equal profit.

Revenue is not profit

According to disclosures tabled in Kenya’s Parliament, Bolt Kenya generated KSh2.45 billion in revenue in the year ended June 2024, down 25% from KSh3.27 billion the previous year. Uber Kenya, meanwhile, increased revenue to KSh2.39 billion, from KSh2.15 billion. Craft Silicon’s Little Cab increased revenue to KSh1.44 billion, from KSh1.13 billion.

Together, the three companies generated about KSh6.3 billion in revenue during the period, down from KSh6.56 billion a year earlier. In Kenya, Uber and Bolt together controlled more than 70% of Kenya’s ride-hailing market by revenue and driver numbers. Uber is not leaving profitable markets.

The Kenya Revenue Authority separately told Parliament that revenue collected from digital taxi-hailing and digital delivery services amounted to KSh16.06 billion. That broader figure covers the wider industry rather than just the three companies above. The distinction is because the value of rides taking place through a platform is not necessarily the same as the platform’s recognized revenue. Platform revenue is not the same as profit as they have to spend again on technology, customer support, marketing, regulatory compliance, incentives and other operating costs.

Numbers Do Lie

These figures demonstrate why market share can be misleading. Bolt had the largest revenue decline among the top three hailing firms in Kenya and its revenue fell by KSh1.27 billion in a single year due to fare increases introduced to address driver concerns over rising fuel costs, which subsequently contributed to customer losses in a highly price-sensitive market.

Uber and Little, meanwhile, gained revenue during the same period as customers and drivers move between platforms depending on prices, availability, incentives and operating conditions. That is exactly what makes the winner-takes-all argument difficult to sustain. These means that even safer public transport can eat into a dominant players revenues if there is no other better alternative. This is not the pattern one would expect in a market where one platform simply wins and everyone else loses.

It’s also too simplistic to argue that African ride-hailing companies are loss-making or whether the profits generated are sustainable. In 2024, Uganda’s SafeBoda recorded a total income of UGX383.3 million, down from UGX420.4 million in 2023. Yet net profit after tax increased to UGX99.5 million, from UGX34.1 million. The numbers are relatively small compared with the revenues of global platforms, but they demonstrate that a ride-hailing firm can operate profitable businesses in one sane region without becoming scaling continent-wide.

Public Company vs Startup

Uber is no longer the loss-making startup that entered Africa 12 years ago. For its full-year 2025, Uber reported $52.0 billion in revenue, $5.6 billion in operating income and $193 billion in gross bookings. Its fourth-quarter revenue alone reached $14.4 billion, while gross bookings rose to $54.1 billion. Uber has therefore built a highly profitable global platform across mobility, delivery and other activities globally, with significant scale outside Africa.

Bolt, on the other hand provides a different picture.

According to Estonian Public Broadcasting’s report on Bolt’s 2024 results, Bolt generated €1.99 billion in revenue in 2024, up 17% from the previous year, but recorded a €102.6 million net loss. Ride-hailing represented 82% of its revenue. Though Bolt is not a failing company, it still has to invest in some markets like Nigeria and Uganda for its scale and profitability even if it means low margins.

inDrive offers another contrast.

According to Reuters’ report on inDrive’s 2025 results, the company increased net revenue by 31% in 2025 to $601.6 million, driven partly by improved profitability per ride. The company has also surpassed 400 million downloads since launching in 2013. Therefore, scaling and generating rides, generating revenue are not the same thing as generating cash flow and generating sustainable net profit. Nigeria and Uganda were not sustainable for Uber.

This is even harder to determine because drivers are not normally exclusive to one platform. A driver can use Uber, Bolt, inDrive and other applications simultaneously depending on what each company is offering at the time. Discounts, commisions among others matter too and there is no possibility of one firm locking up the supply side of the market.

If Bolt offers a better opportunity in the morning, the driver can use Bolt. If inDrive produces better economics later in the day, the driver can switch. If another platform provides stronger demand at another time, the driver can return to it. The same driver can therefore contribute to the gross transaction value of several competing companies during the same week. This is the same for passengers. A customer might use Uber for one trip, Bolt for another and inDrive for a third.

The real competitive unit is therefore not necessarily the customer but the trip. When Uber disappears, Bolt does not automatically acquire Uber’s entire customer base. inDrive does not automatically acquire Uber’s drivers because these are likely the same drivers on alll major platforms. Local companies do not suddenly gain exclusive access to a pool of transportation demand instead, every platform continues competing for individual trips.

Uber’s departure removes one competitor from the market, but it does not eliminate the fundamental competition between the remaining platforms. It’s depature could mean more rides for Bolt or more rides for inDrive or for local operators but it could also mean more competition among those same companies hence spending more on marketing, discounts and driver incentives. They may compete aggressively for corporate accounts and they both might see increased activity without necessarily improving margins.

The temptation after a major competitor exits is to chase market share and unplanned expansion. Growth can be particularly attractive because higher volumes can improve the appearance of scale but ride-hailing has a difficult characteristic. Costs easily grow with the transaction as more rides require more drivers and more incentives to them. These also means more customers, hence more support and more trips create more payment and operational costs.

And the underlying vehicle still has to be fueled, maintained, insured and financed. That is why a platform can become bigger without necessarily becoming much more profitable. Bigger may lead to chaos like what Bolt has had with its image in Africa. Which again works against it.

With the Uber exit, the profitable companies need more than growth. The transportation industry is beginning to change at the vehicle level and Electric Vehicles are becoming increasingly relevant to improve fleet economics. Bolt has just around 5000 EV bikes on its platform in Kenya as the acquisition cost of the EVs is still high and most owners pay exorbitant prices to own the assests. EV assest financing is also high and battery-swapping networks need to be disrupted.

Green savings aside, the biggest threat in the next few years is autonomous driving which Uber sees as a profitable venture without blood, sweat and tears from Africa. The firm is also going heavy into food delivery with the recent Uber acquisition of Glovo.

Tesla has now begun limited commercial rides with its two-seat, fully autonomous Cybercab in selected areas of Austin, Texas. Reuters reported that Tesla had 420 autonomous vehicles registered in Texas, including 45 Cybercabs, as of early September 2026.

Waymo and Amazon-backed Zoox are also expanding their autonomous ride-hailing operations. Reuters reported in September that Zoox had expanded testing to additional U.S. cities while Waymo was expanding its commercial autonomous service to 14 cities. The significance for Africa is not that robotaxis are about to replace Uber in Lagos or Kampala. No. They are not. Not tomorrow. But the global mobility industry is experimenting with a model in which the most expensive participant in today’s ride-hailing equation, the human driver could eventually be replaced and these changes everything.

Tesla’s Cybercab is particularly relevant because it was designed specifically for autonomous ride-hailing. The vehicle has no conventional steering wheel or pedals and is being developed as part of Tesla’s robotaxi strategy. If autonomous vehicles eventually reach mass commercial deployment, today’s ride-hailing leaders could find themselves competing against an entirely different cost structure and large driver networks may not matter but who can operate the most efficient autonomous fleet.

Firms with access to capital, vehicle manufacturing, energy infrastructure, artificial intelligence, mapping and fleet-management technology. will win the day and this could be inDrive, Bolt, Yango among others but not another ride-hailing application connecting trips.

Uber’s departure from Nigeria and Uganda undoubtedly creates opportunities. Bolt, inDrive, local companies but the structure of ride-hailing makes it difficult for a winner-takes-all scenario. Both drivers and passengers can multi-home at no cost depending on fuel prices, vehicle quality, available public transport alternatives and that means more trips but less choice for passengers.

The mobility winner in Africa is not a new Uber-like clone but an ecosystem that creates value for passengers, drivers, investors and cities. That could include ride-hailing, electric vehicles, charging, vehicle financing, insurance, logistics, payments, fleet management and eventually autonomous transportation.

A company that controls several parts of that ecosystem could become more defensible than a company that simply dispatches cars. The future African mobility leader is not the number of drivers or rides but sustainable cash flow for the players involved while reducing the structural costs of moving people around African cities. Tesla’s Cybercab or Uber may win as the new generation of electric and autonomous mobility companies is beginning to challenge the economics of today’s ride-hailing platforms.

That is why Uber’s exit should not be read simply as a victory for its competitors but a warning about the future of mobility. Africa’s growing mobility players demand durable revenue, positive cash flow and ultimately sustainable profits without the driver and regulatory chaos that these firms face. That’s why Moove is contemplating its next move after Uber’s announcement.

For years, Bolt appeared to be writing one of Africa’s most impressive mobility success stories. The Estonian ride-hailing company expanded aggressively and positioned itself as an affordable alternative to Uber and traditional taxis. From Nairobi and Lagos to Johannesburg and Accra, Bolt became part of the daily transportation infrastructure of African cities.

But after years of investment and expansion, the company faces a culture problem, one which cannot be solved simply by adding more drivers, launching new features or spending more money on technology. In many parts of Africa, Bolt is increasingly perceived as cheap, chaotic and unpredictable last-resort alternative and instead of choosing Bolt, Uber loyalists might find themselves home at Little or inDrive or elsewhere.

Among some middle and upper-income consumers, the Bolt brand has developed a less aspirational image compared to Uber. But with Uber’s exit in Nigeria and Uganda, Bolt can pull off a rebirth by selling off itself as a platform for calm and collected people formerly served by Uber. This is the time the company can drop its affordability, saviour messaging to a mature, trusted, aspirational mobility platform.

Bolt has invested heavily in Africa since it first launched in South Africa in 2016. It’s now operational in major African markets, including Kenya, Nigeria, Ghana, Uganda, Tanzania and Tunisia. It built around serving the mass market and localization and it acceptied cash in markets where card penetration was limited, introduced motorcycle and tuk-tuk services, adapted pricing to local purchasing power and recruited hundreds of thousands of drivers at times, regardless of the age or quality of the car.

Just yesterday, Bolt announced it was marking 10 years of operations in Kenya with over KSh19 billion invested in the country. The company didn’t say how much it has made here cumulatively since launch but it had connected over 8 million riders and created income opportunities for more than 170,000 drivers and couriers since 2016. 

According to Dimmy Kanyankole, Bolt East Africa’s Senior General Manager, “Kenya is not a market we entered lightly, and after ten years, it is certainly not one we take for granted. As we look to the next decade, our commitment is to continue investing in Kenya and expanding the opportunities that technology can create for drivers, businesses and communities across the country.”

Those investments have required substantial external capital. In 2021, Bolt raised more than $700 million to accelerate its expansion across Africa and Europe, with the funding supporting ride-hailing, food delivery and other mobility services. The company subsequently raised a further €628 million, providing additional capital for growth, technology and expansion.

In South Africa, Bolt has invested more than $160 million, in the country over the past decade. The investment has supported its driver ecosystem, operations, safety initiatives and expansion. Bolt has said it has onboarded more than 500,000 drivers in South Africa and served tens of millions of passengers.

Looking into the future, Bolt has attempted to position itself at the center of the transition toward electric mobility working with electric-mobility manufacturers and financing companies to introduce thousands of electric motorcycles to its fleet. These initiatives have reduced fuel costs for drivers, improved the economics of motorcycle transport and lowered emissions.

Bolt has also invested in safety tech, including emergency assistance, trip monitoring, identity verification, pickup verification and other features intended to make its platform safer for riders and drivers. The numbers and initiatives tell a story of a company that has not treated Africa as a peripheral market. But investment has not automatically produced trust as its challenge has been increasingly about the brand perception and quality of the experience, rather than simply the availability or affordability of the service.

Across African markets, recurring complaints center on fare disputes, drivers requesting extra payments, cancellations, lost items, inconsistent service quality, safety concerns and inadequate customer support. These problems are not necessarily unique to Bolt; ride-hailing companies everywhere operate complicated two-sided marketplaces in which drivers and passengers have competing economic interests. But Bolt’s brand has been hit hard because its the cheaper, mass market and more accomodating platform used by all sorts of passengers and drivers.

Like the iPhone and Android wars, in Africa’s major urban markets, ride-hailing has evolved beyond a simple transportation service to a lifestyle and, in some cases, a subtle marker of social class. For some urban professionals, an Uber arriving outside an office, hotel or airport carries a different psychological signal from a Bolt. Uber is often perceived as more established, predictable or premium, while Bolt is more strongly associated with affordability and hustler-mindset. Little plays in between and at times perceived as more corporate and more decent brand. Little has used this to pitch its corporate offerings. Even though the distinction is superficial, consumer brands are built on precisely these emotional sentiments.

A customer choosing between two cars is not necessarily comparing only the price and estimated arrival time. They are looking at the car make and condition, appearance of the driver and are also asking if the driver is kind, will arrive, the car is presentable, will the driver haggle prices, will I feel safe, is the car be new, clean or dirty, will the experience be professional and what happens if something goes wrong? Affordability ceases to make sense if there is too much uncertainty.

Bolt solved the affordability problem but has struggled with the uncertainty. Traditional taxi cabs in many African cities were expensive, fragmented and difficult to regulate. Ride-hailing apps brought price transparency, digital payments, GPS tracking and greater access to transport. Bolt made the service even more accessible by competing aggressively on price but the affordability angle came with a structural cost as drivers have to pay for fuel, car financing, insurance, maintenance and vehicle depreciation.

Motorbike riders face similar pressures, while also dealing with increasingly competitive platforms. When the amount a driver earns from a trip does not appear to justify the cost of completing it, the platform can create incentives for behavior that frustrates customers and leads to more uncertainty.

That is where the interests of riders and drivers collide and a rider sees a driver asking for additional money as unprofessional. A driver may see the same request as necessary to make the trip economically viable. The platform sits between them, and every unresolved conflict becomes a potential brand problem.

This is why Bolt’s perception challenge cannot be dismissed simply as a messaging issue. Some of the behavior consumers complain about may be symptoms of deeper marketplace economics and even if Bolt invests in advertising and content creators to shape its image, the underlying issues and incentives produce poor experiences. Before social media, bloggers and journalists helped shape businesses with constructive criticism, but today content creators go with the flow as long as they can cash a cheque, killing both companies and ecosystems due to broken feedback loops. When criticism becomes a commercial liability, ecosystems stop learning.

Bolt-commissioned research, Bolt-sponsored industry events and reports and similar third-party voices may reinforce the company’s preferred narrative but it won’t be solving the underlying issues. It’s only dangerous when Bolt’s messaging consistently emphasizes its economic contribution, driver opportunities, affordability or social impact while giving less attention to the persistent concerns being raised by riders and drivers.

For consumers, the distinction between genuinely independent research by regulators and self-sponsored surveys can be difficult to see. A report is a good component of a corporate communications strategy but should not be used to silence where the firm failing, it is temporary make-up and risks a firm becoming an echo chamber.

The same concern applies to influencer campaigns and favorable media narratives. Paying creators to promote a platform is legitimate marketing just as commissioning research. But neither should become a substitute for confronting uncomfortable evidence about customer experiences. Bolt does not need more people telling Africa how good it is but it needs credible mechanisms for demonstrating where it is improving, acknowledging where it is falling short and allowing independent scrutiny of both.

That is particularly important because African consumers are becoming more sophisticated about product experience and corporate messaging. They can encounter a glossy campaign praising a platform and, minutes later, find thousands of riders discussing a completely different experience offline or online. When those two realities diverge too sharply, more promotion can actually deepen skepticism.

And Bolt has created such a group who think it doesn’t listen but will pay for a survey or a podcast to avoid constructive criticism. There is another dimension to this problem that technology companies sometimes underestimate how they respond to constructive criticism.

Bolt’s messaging is top-notch from public relations, digital communications and influencer and content-creator campaigns across African markets but promotional activity appears disconnected from the frustrations customers are raising. A driver strike in South Africa or Nigeria can be countered by how Bolt is creating jobs for the masses instead of addressing the issue at hand. Content creators promote products, explain safety features or reach younger consumers, but should not be used to cover necessary noise from passengers and driver-partners.

When riders see influencers praising a platform while they are simultaneously dealing with complaints about driver conduct, cancellations, fare disputes or customer support, the gaslighting will have an unintended effect on the brand. The public sees a firm spending money managing its image rather than one addressing the experiences damaging that image. Though Google no longer lives by its don’t be evil mantra, virtue still pays.

A large consumer platform should expect criticism and should also be able to distinguish between noise and recurring signals. Complaints about drivers requesting additional payments, refusing destinations or cancelling trips are not merely reputational threats. They can reveal weaknesses in incentives, enforcement, pricing or platform design. Similarly, persistent complaints from drivers about earnings can point to structural problems that eventually spill over into the customer experience.

As it scales, Bolt therefore faces a challenge that cannot be solved by messaging alone but visible action such as stronger enforcement where rules are repeatedly violated, faster resolution of customer complaints, greater transparency around pricing and driver economics, and clearer accountability when safety or service failures occur.

Millions of rides generate enormous amounts of operational data and with AI, the company can identify where cancellations are concentrated, which markets generate the most complaints and which behaviors repeatedly undermine customer satisfaction. Uber had enough of its issues in Nigeria and Uganda and knew when to call it a day. The competitive advantage is not a more convincing narrative, but from turning those insights into measurable improvements or scaling down to improve service quality.

For Bolt, the question is ultimately whether its brand promise matches the lived experience of its customers. Influencers can shape awareness, commissioned research can shape the narrative and native advertising can shape perception, but none can permanently manufacture trust when the experience consistently remains the same.

The perception issue becomes even more complicated when viewed through the company’s relationship with drivers. Bolt’s drivers are not employees in the traditional sense. They are independent operators whose livelihoods depend on the economics of the platform. The company needs them to keep fares competitive and consistent enough to attract riders while ensuring that drivers have sufficient incentives to remain on the platform.

The reality is that African economies are dealing with inflation, higher fuel costs, expensive vehicle financing and rising urban living costs. Add to that poor government policies and taxation, a ride-hailing platform can find itself in a loss-making cycle as lower prices attract more riders. More riders attract more drivers and more drivers increase competition between drivers. Competition puts pressure on driver earnings and driver frustration creates poorer customer interactions. Poorer interactions damage the brand and the company poors more money trying to rebuild trust. Breaking that cycle requires more than predictable positive messaging by Influencer A and B.

Bolt’s electric-mobility strategy could become part of the solution. Electric motorcycles, for example, can substantially reduce fuel expenditure for commercial riders, potentially improving driver economics while also reducing emissions. If those savings are passed through effectively, electric mobility could improve both the economics of driving and the customer experience.

But like messaging, technology cannot fix every problem. An electric motorcycle does not make a driver more courteous. A sophisticated safety feature does not automatically make a customer feel safe. A new app feature does not resolve a frustrating support experience. The brand ultimately lives at the point where the customer meets the driver. That is why Bolt’s next phase in Africa may require a different definition of growth, one centered on building the driver, not just growing the platform.

The company could develop training and education partnerships that equip drivers with skills, qualifications and pathways into other careers and businesses beyond driving. Bolt doesn’t have to pay surveys everyday but can launch a foundation to fix driver frustration as some of them are already highly educated. Drivers need to know their work can be a stepping stone to a better economic future, working capital and not getting another car loan or data bundle but moving into tech, cybersecurity, hospitality, entrepreneurship, skilled trades, management or an entirely different profession.

For years, the company’s success is measured through the number of countries entered, drivers recruited, passengers served and trips completed. or jobs created. Those metrics remain important, but as the platform matures, other measurements become equally significant: customer retention, complaint resolution, driver satisfaction, safety outcomes and the willingness of higher-value customers to choose Bolt even when another platform is available.

The company does not necessarily need to become expensive to become premium but consistency can transform an inexpensive service into a trusted brand. When a customer knows that choosing Bolt means consistent pricing, not a negotiation with the driver, not worrying about what happens if something goes wrong among others. That is ultimately the gap Bolt needs to close: the distance between its corporate investment, driver expectations and the consumer’s lived experience.

Consumers do not experience Bolt’s funding rounds and do not have to understand its technology stack or corporate strategy but the car that arrives at their location, the driver behind the wheel, the fare displayed on their phone and the response they receive when something goes wrong. That is where the brand is ultimately judged. Bolt can ‘win’ the Nigerian or African mass mobility market but the bigger challenge is winning the trust of the consumers who are left with little or no options.
CEO Weekends: Joseph Ongachi of JentaHub on Connecting African Professionals to Opportunities Globally

JentaHub is a verified talent marketplace that connects businesses around the world with verified African professionals. The firm’s mission is to give qualified African professionals greater access to international opportunities offered by global businesses, clients, and NGOs.

JentaHub says despite the existence of platforms like Upwork, Toptal, and Fiverr for many years, unemployment among qualified African professionals continues to rise, showing that the unique challenges Africans face in accessing global work opportunities still need better solutions and this is exactly where JentaHub comes in..

Apart from freelance services, JentaHub includes Jenta-Gigs, a dedicated microtask platform that provides professionals with additional earning opportunities through trusted global partners such as CPX Research, BitLabs, AdGate Media, and others.

TechMoran caught up with JentaHub founder and CEO Joseph Ongachi on how the verified talent marketplace aims give qualified African professionals greater access to international opportunities.

Why did you start Jentahub?

I founded JentaHub in 2026 after recognizing the challenges many qualified African professionals continue to face on existing freelancing platforms, particularly when it comes to accessing meaningful international work despite having valuable skills, qualifications, and experience.

As the founder and CEO, I oversee product development, technology, and the overall direction of the business while continuously improving the platform based on user feedback, industry research, and the evolving needs of both professionals and businesses.

What gap in the market did you spot?

We identified a clear gap between Africa’s growing pool of qualified professionals and the global demand for skilled talent. While many freelancing platforms provide access to online work, they have not adequately addressed the barriers that continue to limit African professionals from fully participating in the global digital economy. At the same time, businesses continue to face trust challenges when hiring remotely, making verification more important than ever.

Our competitors include Upwork, Fiverr, Freelancer.com, and Toptal. JentaHub differentiates itself by focusing specifically on verified African professionals through identity, academic qualification, and skills verification, while creating multiple earning opportunities through both freelancing and Jenta-Gigs. Our goal is not simply to compete with existing platforms, but to solve the specific challenges that continue to affect qualified African professionals.

You have investors or boostrapping?

JentaHub is currently bootstrapped and has been entirely self-funded from the beginning. This has allowed us to remain focused on building the platform around the real needs of professionals and businesses rather than external pressures.

Our biggest milestone so far has been successfully launching the platform, onboarding our first users, integrating leading global earning partners through Jenta-Gigs, and establishing the foundation for strategic partnerships that will accelerate future growth.

What has uptake been like?

JentaHub is in its early launch stage and has started onboarding its first users while actively gathering feedback to improve the platform. The growth rate has been encouraging and reinforces our belief that we are solving a genuine problem in the online hiring space, where many professionals remain underserved and businesses continue to struggle with trust when hiring remotely.

Our current focus is on growing our community of verified professionals, strengthening partnerships with international businesses and organizations, and continuously improving the platform to deliver a world-class hiring experience.

What markets are you operating in currently?

While we are based in Kenya, our primary focus is Africa, where we identify, verify, and onboard qualified professionals across multiple industries. Most of our professional community is African, the businesses, clients, and organizations we serve are global. Our objective is to bridge the gap between Africa’s highly skilled workforce and international opportunities that have traditionally been difficult for many professionals to access.

As we continue to grow, we plan to expand into more African countries while increasing our presence in international markets by attracting more global businesses and organizations to hire through JentaHub. Our long-term vision is to become the leading gateway connecting verified African professionals with opportunities around the world.

What is your business model?

JentaHub generates revenue through service fees charged as a percentage of professionals’ earnings on completed freelance projects, commissions generated through Jenta-Gigs, and premium tools and hiring features offered to businesses seeking a more advanced recruitment experience.

As an early-stage startup, our primary focus is building a sustainable platform, expanding our user base, and delivering long-term value. Revenue generation is growing alongside the platform as we continue to onboard both professionals and businesses.

Any chalenges so far?

One of the biggest challenges has been building trust as a new platform while competing against well-established global marketplaces that have operated for many years. Convincing both professionals and businesses to embrace a new platform requires consistently demonstrating credibility, security, and quality at every stage of the user experience.

Because of that we have put a strong emphasis on trust through identity verification, strict academic qualification verification, and skills verification, ensuring the professionals we connect to global opportunities are backed by verified credentials rather than just claims, while supporting every project with secure payments and built-in collaboration tools.

Another major challenge has been developing the infrastructure required to support international payments, strict verification processes, secure project collaboration, and global earning partnerships while remaining completely bootstrapped. Although these challenges have required significant investment of time and resources, they have also shaped the strong foundation on which JentaHub is being built.

TryMassive AI Launches to Help Kenyan Businesses Get More Customers Through Google Search, Maps, and AI Referrals

0

TryMassive AI has launched in Kenya with a platform aimed at helping restaurants, salons, pharmacies, retailers and other small businesses gain visibility in Google Search and Maps as consumers increasingly turn to online and AI-powered tools to find local services.

Founded by software developer Segun Olaiya, TryMassive AI is targeting a problem faced by businesses that depend on customers within a relatively small geographic area: being open for business does not necessarily mean being visible when potential customers search nearby.

A consumer looking for a restaurant, pharmacy or salon may see only a small number of businesses prominently displayed on Google Maps. TryMassive AI is designed to help businesses improve their position in those results through profile optimization, local search tracking, review management and competitor analysis.

The company is also extending its focus beyond Google by building tools intended to make business information easier for artificial-intelligence systems and voice assistants to interpret when consumers ask for local recommendations which has become a new battleground for small businesses as AI assistants become increasingly popular intermediaries and search tools.

TryMassive AI’s software starts with a local visibility scan, mapping where a business appears for searches conducted across its surrounding area. It identifies competitors ranking higher and highlights gaps in the business’s online presence.

The company then works on the business’s Google Business Profile, including categories, operating hours, services, contact information and photographs. It also provides ongoing management, including posts, service updates and responses to customer reviews.

The platform tracks changes in local rankings over time and provides businesses with reports covering measures such as calls, direction requests and search visibility.

TryMassive AI says it is designed as a managed service, allowing business owners to use the platform without having to run their own search-engine-optimization campaigns.

“Your local reputation is your most valuable asset,” Olaiya said. “If you run a great business in Kenya, you deserve to be the first option people see when they search on their phones.”

The company’s initial focus is on sectors where proximity can directly influence purchasing decisions, including restaurants and cafes, beauty businesses, pharmacies, clinics, retail outlets and home-service providers.

For these businesses, the economics of local search can be significant. A customer searching for “restaurant near me” or “pharmacy open now” is typically closer to a purchasing decision than someone conducting a general search about a product or service.

TryMassive AI is entering a market that includes established search-marketing agencies and software providers, but is positioning itself around an automated, managed approach targeted at small and medium-sized businesses.

Olaiya has previously worked as a software developer for companies including MailerLite, Xtremepush and SOCi and his experience is key in helping businesses in Kenya to bolster their visitbilty through a free local-search visibility audit via TryMassive.AI. TryMassive aims to provide Google Business Profile optimization, map-rank tracking, review management, keyword research, competitor analysis and services aimed at improving visibility in AI-powered search. The company plans to expand its local-search offering across Africa.

Glovo Kenya Partners with eBee Mobilities to Attract Female Couriers

Glovo, an on-demand delivery platform owned by Uber, has partnered with e-mobility company eBee to onboard more women on the platform on its platform in Kenya from 1% to 5% over the next year.

Glovo works with more than 2,500 active couriers daily in Kenya, the initiative dubbed ‘She Delivers’, will deliver practical rider training through eBee before participants join the Glovo platform, with the initial cohort bringing together 16 women.

According to Liz Wambua, Head of Operations, Glovo Kenya, “‘She Delivers’ is a core business strategy to build a more inclusive, resilient, and sustainable logistics ecosystem. By pairing eBee’s clean mobility technology with Glovo’s platform reach, we are creating a scalable model for women to build independent incomes while setting a new benchmark for gender parity in urban last-mile delivery across the region.”

While Kenya’s digital and gig economies have created new earning opportunities, participation has not been equal. For women considering delivery work, barriers range from limited riding experience and vehicle access costs to safety concerns and social bias surrounding traditionally male-dominated mobility jobs.

Through the partnership, eBee will provide structured training covering e-bike handling, defensive road safety, basic maintenance, navigation, and delivery-platform readiness, helping participants build the practical skills and confidence required to operate independently as couriers.

“Electric bicycles remove heavy physical exertion and lower operating expenses, making last-mile delivery a genuinely viable, high-earning opportunity for women,” said Maarten Fonteijn, Managing Director eBee Africa. “Partnering with Glovo allows us to advance gender equity while accelerating the shift toward clean, zero-emission urban transport.”

Participants will operate electric bicycles, adding a strong sustainability dimension to the programme as Kenya’s last-mile delivery sector transitions toward cleaner and more affordable forms of urban mobility.

“Access to e-bikes and structured safety training removes the biggest hurdle to joining this sector,” said Yvonne Muribi, a rider from the initial cohort. “It gives us the confidence to navigate traffic safely and build an independent income on our own terms.”

Glovo and eBee are establishing a blueprint for gender-inclusive, zero-emission last-mile logistics in East Africa. By turning real-world pilot insights into optimized asset financing, safety infrastructure, and targeted onboarding channels, the partnership lays a scalable foundation to reach the 5% female representation target, proving that sustainable mobility and economic equity go hand-in-hand.

WapiPay Partners Jamaica’s JN Money in Caribbean Expansion Drive

Kenya’s WapiPay is expanding its network into the Caribbean through a partnership with Jamaica’s JN Money Services, opening a new payment corridor linking Jamaica with markets in Africa and Asia, months after it announced entry into the market.

The agreement, announced after WapiPay received regulatory approval from the Bank of Jamaica, will allow customers using WapiPay to send money to Jamaica for cash collection at JN Money locations or direct deposits into local bank accounts.

The move gives WapiPay access to JN Money’s established payout infrastructure while extending the Kenyan fintech’s reach beyond its core Africa-Asia business. JN Money operates an international remittance network spanning 18 countries, according to its parent company, Jamaica National Group.

For WapiPay, Jamaica represents an entry point into the Caribbean and another step in its effort to build payment infrastructure across emerging markets rather than operate individual remittance corridors in isolation.

WapiPay was founded in 2019 by brothers Edward and Paul Ndichu and initially focused on payments between Africa and Asia, particularly transactions involving African businesses paying suppliers in Asia. The company has since expanded its network across Africa, Asia, the UK, the US and the Caribbean.

The Jamaica partnership also broadens the potential use of the platform beyond consumer remittances. The companies said the arrangement will support both person-to-person transfers and business-to-business payments, including trade-related transactions.

That distinction is important for fintechs competing in the increasingly crowded cross-border payments market. Remittances provide a large and recurring transaction base, while business payments can generate larger transaction values and create deeper relationships with merchants and companies.

Under the arrangement, WapiPay customers will be able to send funds to Jamaica for cash pickup through JN Money or have money deposited into recipients’ local bank accounts. WapiPay said it is targeting completion of transfers in less than 30 seconds on supported transactions and will not charge a fee on its side for the service.

The partnership comes as remittance companies compete on speed, foreign-exchange transparency and distribution rather than simply the ability to move money between countries.

JN Money said the partnership will also expand the international corridors available to Jamaicans, particularly as digital-first providers seek to connect Caribbean consumers with newer sources of migration, trade and financial flows.

For WapiPay, the move fits into a broader expansion strategy. The company has recently added regulated markets and services to its network, including a Canadian Money Services Business license that allows it to provide foreign-exchange, money-transfer and payment services in Canada. The license also covers virtual-currency and digital-asset transactions.
The company has also been building products around remittance data. Earlier this year, it introduced a remittance-based credit-scoring tool designed to help financial institutions assess borrowers using patterns in their international money transfers.

Jamaica’s importance to the strategy comes from the scale of its remittance economy. The country is one of the Caribbean’s major recipients of money sent home by citizens living overseas, making access to reliable international payout infrastructure commercially significant for payment providers.

JN Money will serve as the local payout conduit under the new arrangement, allowing WapiPay to use an existing network rather than build a physical cash-distribution infrastructure in Jamaica from scratch.

The partnership effectively creates a three-region payment link: WapiPay brings its network across Africa and Asia, while JN Money provides the local Jamaican infrastructure. The companies say the arrangement could eventually connect Jamaican customers more efficiently with Africa, Asia, North America and Europe.

For African fintechs, such corridors are becoming increasingly important as companies look beyond domestic mobile-money markets and compete to capture a larger share of international payments.

WapiPay’s Jamaica expansion is therefore less about adding another destination to a remittance app than about building a broader network through which money can move between emerging-market economies with fewer intermediaries.

The company is positioning the network around consumer remittances, trade payments and business disbursements, giving it multiple potential sources of transaction volume as it expands into new regulated markets.

With Jamaica now added to its international footprint, WapiPay is betting that the next stage of African fintech growth will involve connecting the continent not only to traditional financial centers, but also directly to other high-volume emerging markets.

Wave of African IPOs Ahead of Global Surge

0

Eric Osiakwan

In addtion to the two Dangote group IPOs this year, two Chinese tech firms with predominantly African operating businesses are seeking to list on the Stock Exchange of Hong Kong (ESHK). Transsion, whose Tecno, Infinix, and itel phones are market leaders across Africa, has cleared the regulatory hurdle for an ESHK listing. Separately, its sister company, PalmPay, a fintech firm operating in Nigeria with backing from Transsion and China’s NetEase, is seeking about $200 million ahead of a potential listing on the ESHK, with a prospective valuation of one billion dollars. Hong Kong gives these companies access to international investors and deeper capital markets exposure whilst keeping them close to their Chinese ownership base. 

PalmPay’s rival, Opay, another Nigerian payment service provider headquartered in Lagos and Singapore, with operations in Nigeria, Egypt, Pakistan and Indonesia, also plans to go public in the United States, targeting a $4 billion valuation. Airtel Money, another leading African fintech with operations in 14 African markets, had earlier announced plans for a London IPO, with a $10 billion valuation target. Finally, MNT-Halan, an Egyptian fintech, is also eyeing a listing on the Egyptian Stock Exchange at a billion dollar valuation. These African IPOs slated for 2026 are well ahead of their global compatriots, a significant development and a test of whether global investors see the continent as a source of scalable growth ventures. 

Earlier in the year, OpenAI, SpaceX, Anthropic, Discord, Kraken and others were listed as potential IPO candidates for 2026. But so far, only SpaceX has gone public with Anthropic expected to close the year, whiles OpenAI is now aiming for 2027. According to Emily Zheng, Senior Research Analyst at PitchBook, “IPOs are generally suffering from continued uncertainty from multiple wars, rising energy prices, and AI’s draining of moats around business models across industries has made the market too volatile to instill confidence in the next cohort of VC-backed IPO candidates.” She argues that, “the IPO pipeline is expected to remain thin in the coming years with a more selective cohort of IPO candidates: companies that stayed private longer, are bigger at the time of listing, and go public for a specific reason tied to their growth story. This is the new normal.”

Continental Holdings PLC became the 17th company to list on the Malawi Stock Exchange (MSE) on August 10th. More than ten thousand investors subscribed to shares in the Initial Public Offering (IPO) which covered 753.3 million shares priced at 195 kwacha each. It was 93% subscribed raising approximately K135.4 billion, making it the largest IPO in Malawi’s capital market history. The stock went up more than 75% on its first day of trading, rising from 195 to 342 kwacha.  

However, the African companies that are listing on the internantional exchanges have raised concerns in some African markets over why they are not listing on the local exchanges where they generated their value, or not considering a secondary listing so that locals can share in the wealth that is created. At a meeting with the President of Nigeria, the CEO of Nigeria Exchange Group (NGX Group), Temi Popoola, advocated for policy and legal measures that could encourage major companies with substantial Nigerian operations to pursue dual listings (local and international).  

The Dangote Group is leading by example. The group’s cement business which is currently listed on the NGX announced plans for a secondary listing on the London Stock Exchange. The group’s subsidiary Dangote Refinery also seeks to list a 5% to 10% minority stake  on the Nigeria Stock Exchange (NGX) with a dual listing on other African exchanges. The company initiated talks in 2nd quarter 2026 with African stock market leaders on building a pan-African listing framework, potentially using depositary receipts rather than direct dual listings with six African exchanges, including those in Ghana, Kenya, South Africa and the regional BRVM. 

Dangote Refinery’s pursuit of an IPO comes amid the expansion of its 650,000-barrel per day plant, which has become the main domestic supplier of refined fuels to the Nigerian market, as well as exporting jet fuel to Europe. The company has secured $1 billion in an underwriting program from two firms. The amount consists of a $600 million participation in the refinery’s $2.5 billion private placement and a new $400 million commitment that will go into effect when the IPO launches in October 2026. The refinery’s CEO, David Bird said “an international listing possibly in London is at least three years away, pending a longer track record of financial performance”.

Hopefully Dangote’s example of dual listing that allows both local and international investors to participate in the wealth created is pursued by the new entrants into the market. 

Sun King Deepens Kenya Smartphone Push With Under $1-a-Day EZ 3 Series

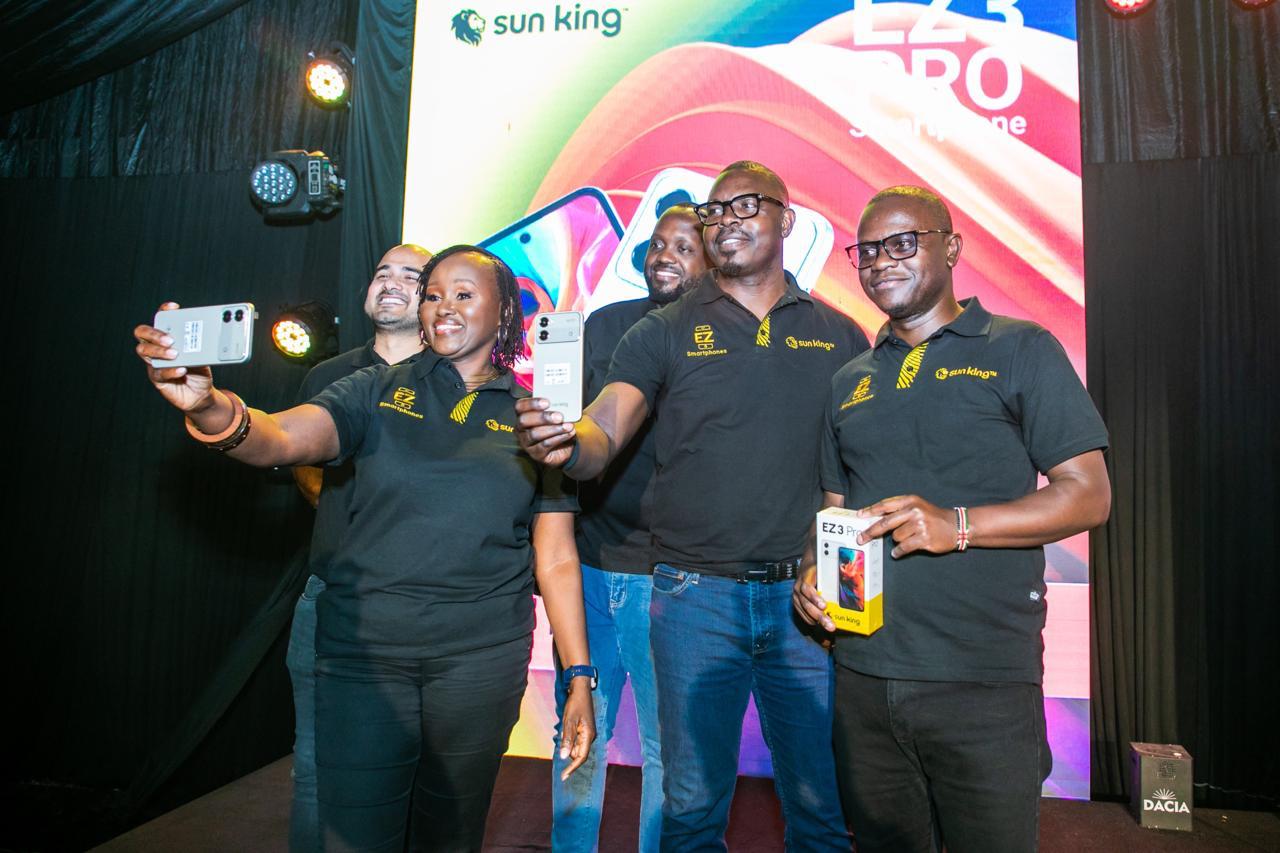
Sun King is expanding its smartphone business in Kenya, launching the EZ 3 and EZ 3 Pro less than a year after entering the market as the solar company looks to turn its distribution and financing infrastructure into a broader consumer technology business.

The company introduced the two devices Thursday, expanding its smartphone portfolio from one model to two. The EZ 3 starts at KES 55 a day with a KES 2,299 deposit, down from KES 60 a day and a KES 2,999 deposit for the EZ 1.

The EZ 3 Pro starts at KES 65 a day with a KES 3,099 deposit.

The launch marks a more deliberate phase of Sun King’s smartphone strategy. Rather than testing the market with a single device, the company is building a broader range while lowering the financial barrier to its mainstream model. Sun King has spent years building a distribution and financing network around affordable solar products in Kenya. Smartphones give the company another category in which to deploy that infrastructure.

Catherine Mudachi, Sun King’s global vice president for marketing, said at the launch that one in five Kenyan households has access to a Sun King product. She also said the company installs more than 330,000 solar kits every month across Africa. That scale gives Sun King a potential advantage in smartphones. The company already has agents, customers and experience managing recurring payments, allowing it to enter the device market without having to build an entirely new distribution model.

The challenge is converting that reach into smartphone sales in a market where established brands already compete aggressively on price, specifications and retail availability.

The EZ 3 is aimed at the mainstream market, with a 6.75-inch HD+ display, a 120Hz refresh rate, 4GB of RAM plus 4GB of virtual RAM, 64GB of storage expandable to 1TB, a 13-megapixel rear camera and a 5,000mAh battery. The EZ 3 Pro moves further up the range with a 50-megapixel camera, 6GB of RAM, 128GB of storage and a 6,000mAh battery supporting 18W fast charging.

The bigger strategic change, however, is the move from one device to a two-phone portfolio. Sun King launched the EZ 1 in February as its first Sun King-branded smartphone in Kenya. The company is now giving customers a choice between a mainstream model and a higher-specification Pro version.

That progression suggests Sun King is moving beyond an initial smartphone experiment and beginning to establish a dedicated device business.

Pay-as-you-go financing is not new to Sun King’s smartphone strategy. It was part of the EZ 1 proposition from the start.

What has changed is the combination of financing, product range and hardware.

The EZ 3 requires a lower deposit and daily payment than its predecessor while offering a larger display, faster refresh rate and expandable storage. The Pro model gives customers the option of paying more for higher specifications.
The approach builds on a model Sun King has used in its solar business: spread payments over time and use a network of local agents to reach consumers who may find conventional upfront purchases difficult.

For smartphones, however, the economics are more competitive. Sun King is competing against brands with established consumer recognition, extensive retail networks and increasingly capable devices at similar price points such as M-KOPA and mainstream phone manufacturers which also offer pay-as-you-go. Banking on affordability with the reach of its existing customer network is a plus.

Its solar products address access to electricity. Smartphones provide access to digital services, mobile money, e-commerce, online work and communication. For traders, smartphones can be used to market products and communicate with customers. For boda-boda riders, they provide navigation and access to digital payments. For creators, they are production and distribution tools.

That makes smartphones a logical adjacent category for a company that already has relationships with millions of consumers across its markets.

But the EZ 3 launch is not about introducing pay-as-you-go smartphones to Kenya. Sun King has already established that model with the EZ 1. Sun King is moving from a single smartphone to a two-device portfolio while lowering the entry payment for its mainstream model.

Sun King’s core business remains solar, but the scale of its distribution network gives the company an opportunity to build additional consumer businesses around the same infrastructure. The company says it has sold more than 31 million solar products globally, while Mudachi said it now installs more than 330,000 solar kits every month across Africa.

In Kenya, Sun King says one in five households has access to one of its products. The smartphone opportunity is to turn that existing reach into a broader consumer technology channel.

The EZ 3 series will test whether the company can do that in a market where smartphone adoption is growing but competition is intense. For Sun King, the significance of the launch is therefore bigger than the specifications of two new phones but a bet on its financing capabilities, distribution network and customer relationships that helped build its solar business.

Safaricom Ethiopia Passes 15 Million Subscribers, Nears Break-Even Five Years After License

0

Safaricom Ethiopia has surpassed 15 million active subscribers, a milestone that underscores the rapid growth of Ethiopia’s second telecom operator as it edges closer to profitability less than four years after launching commercial services.

The company reached the milestone as it marked five years since receiving a nationwide telecommunications license from the Ethiopian government in July 2021. Commercial operations began in October 2022 after more than a year of building network infrastructure and distribution channels.

The operator said it has built more than 3,500 mobile sites covering about 60% of Ethiopia’s population, with every site supporting 4G services and ready for 5G deployment. The rollout ranks among the fastest by a greenfield telecom operator in Africa, Chief Executive Officer Wim Vanhelleputte said.

“Since receiving our license, we have built more than 3,500 network sites, with our network now reaching around 60% of the country’s population. All our sites are 4G-enabled and 5G-ready, making our network state-of-the-art,” Vanhelleputte said.

Safaricom Ethiopia entered one of Africa’s last liberalised telecom markets to compete with state-owned Ethio Telecom, investing heavily in infrastructure, technology and distribution to establish a nationwide network from scratch.

Its rapid subscriber growth is helping narrow losses after years of investment. The company said it is approaching financial break-even as customer numbers and revenues continue to rise.

The expansion has also contributed to Ethiopia’s broader digital transformation, accelerating internet access, mobile data usage and digital payments while extending connectivity to previously underserved communities.

Beyond its commercial operations, Safaricom Ethiopia said it has invested ETB139 million in community projects, while shareholders and development partners have contributed a further ETB545 million, bringing total community investment to ETB684 million.

“We have also witnessed the emergence of world-class talent in information technology in Ethiopia, and we have played our part in supporting that journey,” Vanhelleputte said.

Backed by a consortium led by Safaricom Plc, Vodafone, Vodacom, Sumitomo Corporation and British International Investment, Safaricom Ethiopia has become one of Africa’s largest greenfield telecom investments and is positioning itself as a key driver of connectivity and digital financial inclusion in the country’s 130 million-strong market.

Cascador Picks 10 Nigerian Scaleups for 2026 Growth Program

0

Nigerian entrepreneurship platform Cascador has selected 10 growth-stage companies for its 2026 ScaleUp Program, backing businesses in healthcare, renewable energy, agriculture, property technology and consumer sectors as it shifts its focus toward companies with proven commercial traction.

The companies were chosen from more than 1,000 applicants for the 12-week accelerator, which provides executive mentorship, investor access and eligibility for up to $5 million in follow-on financing through Cascador’s Catalytic Fund, managed in partnership with Sterling Bank.

The 2026 cohort includes property management platform Venco, solar financing startup SunFi, cold-chain logistics provider ColdHubs, healthcare company EHA Clinics, beauty retailer Beauty Hut Africa, wellness chain BEYOND Fitness, hospitality operator Ziba Beach Resort, mineral export marketplace Tulay Africa, agritech firm Maanj Agric, and commercial bakery Finger Chops.

The latest intake marks a strategic change for Cascador, which has increasingly targeted businesses that have moved beyond the startup phase and are positioned for regional expansion.

“Our focus now is helping them scale further and unlock their full potential, giving them the training, mentorship, networks and leadership skills needed to power their next phase of growth,” Chief Executive Officer Trish Thomas said in a statement.

The accelerator combines two weeks of in-person executive sessions with 10 weeks of virtual coaching for founders and their leadership teams. Participants also compete for $50,000 in cash prizes during a live pitch event at the end of the program.

Among this year’s participants is Venco, whose software enables payments, utility billing, resident communication and estate operations for multi-tenanted residential and commercial developments.

“We’re incredibly proud to be part of Cascador’s 2026 ScaleUp Program,” said Venco Chief Executive Chude Osiegbu. “The mentorship, resources and networks the program provides will accelerate our growth as we expand our technology platform to more communities across Africa.”

Women lead 60% of this year’s cohort, while founders come from five of Nigeria’s six geopolitical zones, highlighting the program’s emphasis on building a geographically diverse pipeline of entrepreneurs.

Since its launch in 2019, Cascador has supported 70 ventures that have collectively raised $125 million in external capital. Its alumni served more than 1.7 million customers in 2025, according to the organization.

“The next chapter of Nigeria’s entrepreneurial story will be about what happens when proven businesses get the support they need to scale,” said Cascador co-founder David DeLucia. “That is where sustainable economic value will be created.”

Cascador was founded to strengthen leadership capacity among Nigerian entrepreneurs and has increasingly positioned itself as a bridge between founders, investors and business mentors as startups face a tougher funding environment and growing pressure to achieve profitability.

You can register to be notified when applications open for Cascador’s next cohort here. 

How to Buy Airtel Airtime from M-Pesa Using Pesapal Paybill 220220

0

Buying Airtel airtime from your M-Pesa account is one of the fastest ways to top up your line without visiting a shop or purchasing a scratch card. Using Pesapal Paybill 220220, Airtel customers can buy airtime directly from the M-Pesa menu in just a few simple steps.

Whether you’re topping up your own phone or sending airtime to someone else, the process takes only a few minutes.

How to Buy Airtel Airtime from M-Pesa

Follow these steps:

  1. Open the M-Pesa menu on your phone.
  2. Select Lipa na M-Pesa.
  3. Choose Pay Bill.
  4. Enter the Business Number: 220220.
  5. In the Account Number field, enter the Airtel phone number you want to top up (for example, 073XXXXXXXX).
  6. Enter the amount of airtime you want to purchase.
  7. Enter your M-Pesa PIN.
  8. Review the transaction details and confirm the payment.

Once the payment is successful, you will receive an M-Pesa confirmation message, and the airtime will be credited to the Airtel number provided.

Why Use Pesapal Paybill 220220?

Pesapal Paybill 220220 offers a convenient way to purchase Airtel airtime directly from M-Pesa without switching between apps or searching for an airtime vendor. The service is designed to provide a quick and seamless top-up experience from anywhere in Kenya.

About Pesapal

Pesapal is a Central Bank of Kenya-licensed financial technology company that provides digital payment solutions for businesses and consumers. In addition to airtime purchases, the platform supports payments for utility bills, television subscriptions and other digital services.

Customers who require assistance can contact Pesapal’s support team on +254 709 219 000 or through the company’s official social media channels.

Benefits of Buying Airtel Airtime via M-Pesa

Using M-Pesa to buy Airtel airtime offers several advantages:

  • Fast and convenient transactions.
  • Secure payments through M-Pesa.
  • Available 24 hours a day from anywhere in Kenya.
  • Ability to top up your own Airtel line or another person’s number.
  • No need to buy physical airtime vouchers or visit a retail outlet.

The Bottom Line

If you regularly buy Airtel airtime using M-Pesa, Pesapal Paybill 220220 provides a simple and reliable way to complete your top-ups. Enter 220220 as the Paybill number, use the Airtel phone number as the account number, confirm the payment, and your airtime should be credited within moments.

How AI Is Changing the Cybersecurity Battle in Kenya

Kenya’s economy has become deeply dependent on digital systems, from mobile money and digital banking to e-commerce, cloud services, online government platforms and connected workplaces. 

Digital transformation has created enormous opportunities for businesses, but it has also created a much larger attack surface for criminals. The scale of Africa’s digital transformation is strikingly high. According to INTERPOL’s African Cyberthreat Assessment Report 2026, the continent recorded more than 1.1 billion mobile subscriptions and more than $1.1 trillion in digital transactions in 2025, while more than 570 million people were using the internet.

The security challenge is growing alongside that digital economy. Kenya is now operating in an environment where criminals can continuously probe networks, devices, accounts and applications for weaknesses. Businesses therefore need to respond quickly enough to prevent compromises into their financial or operational systems.

Artificial intelligence (AI) is making that challenge harder. INTERPOL says AI is enabling 55% of reported cybercrimes across Africa, making attacks faster, more scalable and increasingly difficult for victims and platforms to detect. The agency’s 2026 assessment also describes cybercrime as having evolved from isolated incidents into an industrialized, borderless ecosystem. For Kenya, where mobile money, fintech, digital banking and online commerce are deeply embedded in the economy, the implications are particularly significant.

Kenya’s digital success has created a bigger target

Kenya has spent more than a decade building one of Africa’s most advanced digital economies making mobile money an essential part of everyday commerce. Fintech has transformed financial services and businesses of all sizes leading to increased uptake of cloud applications, digital payments, online customer service and connected workplace systems.

This has also led to the need for protection of these digital environments, identities and organizational pathways. Cybercriminals do not necessarily need to defeat the most sophisticated corporate firewall if they can compromise an employee, steal a credential, manipulate a payment or exploit a supplier with weaker security controls.

The result is that cybersecurity has moved beyond protecting computers. It now involves protecting identities, payments, data, communications, cloud infrastructure and the trust on which digital commerce depends.

INTERPOL’s latest assessment puts this into a broader African context. Financial services, telecommunications and government institutions remain among the sectors most exposed because they sit at the center of the continent’s digital economy. The report also warns that widespread use of mobile money has created new attack surfaces, particularly where customer-verification controls are weak or inconsistently enforced.

AI is changing the economics of cybercrime

The biggest change brought by AI may not be that cybercriminals have discovered an entirely new type of attack. It is that existing attacks can now be conducted faster, more cheaply and at a much greater scale.

A criminal who once needed time and technical expertise to create convincing phishing messages can increasingly use AI to generate them. A fraudster can produce communications tailored to different audiences, imitate corporate communication styles and automate parts of the process of identifying and approaching potential victims. INTERPOL says criminals are using AI for automated phishing, deepfakes for identity fraud and social engineering, synthetic identities for financial crime and techniques designed to evade traditional security systems. 

That matters in Kenya because social engineering is particularly powerful in a highly connected economy where businesses communicate constantly through email, messaging platforms and mobile phones. An attacker does not always need to exploit a sophisticated software vulnerability if they can persuade an employee to disclose credentials, approve a transaction or open a malicious file.

The attack may begin with technology, but it ultimately exploits human trust.

The financial stakes are rising

Cybersecurity has also become a financial issue for Kenyan businesses. When an attacker compromises an employee’s email account, the objective may not be to steal information; it may be to redirect a payment. When cybercriminals obtain credentials, they may be trying to gain access to financial platforms. When ransomware enters a business network, the objective may be to interrupt operations and force the organization to pay for recovery.

Local research shows why businesses should take that risk seriously. Serianu’s Africa Cybersecurity Report – Kenya 2025 estimates that Kenyan organizations suffered substantial financial losses from cybercrime, while payment fraud emerged as one of the country’s most significant cybercrime concerns. The report also highlights the widening gap between the speed of digital adoption and the maturity of cybersecurity defenses.

This makes cybersecurity spending not simply an IT expense but necessary to protect revenue, cash flow, customer relationships and business continuity.

East Africa is facing a particularly difficult threat environment

Kenya’s position within East Africa makes the regional dimension particularly important. INTERPOL identifies East Africa as a hub for mobile-money fraud and infrastructure-targeted ransomware. Kenya recorded more than 46,786 DDoS attacks targeting telecommunications companies in the first half of 2025, according to data included in the agency’s latest assessment.

The threat to mobile money is especially significant. INTERPOL says SIM-swap fraud in Kenya surged by 327% in 2025, with more than 123,000 fraudulent SIM cards detected and an estimated $3.8 million drained from mobile wallets. The figures demonstrate why cybersecurity in Kenya cannot be reduced to protecting laptops and corporate networks. The threat increasingly extends across identities, telecommunications infrastructure, financial accounts, mobile applications and the systems that connect them.

The same digital infrastructure that allows a Kenyan entrepreneur to receive a customer payment in seconds can also allow a fraudulent transaction to move just as quickly. Speed therefore becomes a critical part of defense.

By the time a business discovers that a fraudulent payment has been made, the money may already have moved through several accounts or wallets. Similarly, by the time ransomware has encrypted critical files, prevention has already failed and the organization is dealing with recovery. The goal has to be earlier detection.

Kenya is already seeing massive volumes of cyber threats

The scale of activity detected by Kenya’s cybersecurity authorities demonstrates why manual defense alone is becoming increasingly difficult. Kenya’s threat environment is characterized by persistent probing, exploitation attempts, malware, phishing, DDoS activity and credential attacks, creating an enormous volume of information for security teams to process.

The challenge is not that every alert represents a successful breach. It is that a security team can quickly be overwhelmed when thousands or millions of signals have to be examined to determine which ones represent a serious threat.

That creates an information problem.

The more alerts an organization receives, the more difficult it becomes for human analysts to determine which ones deserve immediate attention. A security team that spends its time investigating low-risk activity can miss the behavior that signals a serious compromise.

This is where AI can change the defensive equation.

The defender needs AI too

If cybercriminals are using AI to increase the speed and scale of attacks, businesses need technology that can help security teams process information at a similar scale.

AI-assisted cybersecurity can analyze large volumes of security data, identify unusual behavior, correlate related events and help prioritize incidents. Instead of forcing analysts to investigate every alert individually, intelligent systems can help identify patterns that deserve closer examination.

Consider a Kenyan company where an employee’s laptop suddenly behaves unusually. At roughly the same time, the employee’s credentials are used to access a corporate system from an unfamiliar location, while a suspicious file appears on the endpoint.

Three separate alerts might not mean much on their own. Together, however, they could indicate the early stages of an attack. The ability to correlate those signals quickly can make the difference between containing an incident and dealing with a much larger breach.

From protection to detection and response

Traditional endpoint protection remains essential. Businesses need technology capable of blocking malware, suspicious files and other known threats before they can cause damage.

But today’s threat environment requires more than prevention.

Security teams need to know what happens when something gets through, what systems are affected, how the attack developed, and what needs to happen next. That is the broader shift toward detection and response.

Kaspersky Next brings together endpoint protection with capabilities designed to help organizations detect, investigate and respond to threats. For businesses that do not have large security operations teams, this kind of integrated visibility can be particularly important because it can help reduce the amount of manual work required to understand an incident.

The objective is not to replace cybersecurity professionals with AI. It is to give those professionals better tools for making decisions.

The human factor is becoming more important, not less

The growth of AI does not eliminate the human element of cybersecurity. In some respects, it makes it more important.

Employees remain targets for phishing, impersonation, fraudulent invoices, malicious attachments and social engineering. As AI makes fraudulent messages more convincing, employees may find it increasingly difficult to distinguish legitimate communication from a carefully constructed attack.

INTERPOL’s assessment highlights the growing use of deepfakes, synthetic identities and AI-enabled social engineering across Africa. The report also says AI-generated digital personas are being used to combine real personal information with fabricated elements to bypass identity-verification systems and facilitate fraud.

That means cybersecurity awareness cannot be treated as a once-a-year training exercise. Businesses need employees who understand that a convincing email, phone call or video is not necessarily proof of identity.

At the same time, organizations need technical controls that assume humans will eventually make mistakes. Strong authentication, least-privilege access, endpoint protection, patch management, network monitoring and tested incident-response procedures all need to work together.

SMEs cannot assume they are too small to be targeted

For Kenyan small and medium-sized businesses, the temptation can be to assume that cybercriminals are interested only in banks, telecommunications companies and government institutions. That assumption can be expensive.

Smaller organizations can hold valuable customer information, financial data and credentials while often having fewer resources dedicated to cybersecurity. They can also provide attackers with access to larger organizations through suppliers, contractors and business relationships.

This makes cybersecurity a business-growth issue and not an issue for larger corporations but a priority at every scale of growth. The most dangerous strategy is not having a limited cybersecurity budget but having no cybersecurity strategy at all.

Cybersecurity is now a business resilience issue

INTERPOL’s latest assessment makes cybercrime no longer simply a technical problem but an issue of economic security, public confidence and institutional resilience. The report says cybercrime-related losses across Africa more than doubled from $192 million in 2024 to $484 million in 2025, driven primarily by AI-facilitated scams, credential harvesting and automated social-engineering campaigns. 

For Kenyan businesses, the consequences can extend far beyond the device where an attack begins. A compromised employee account can become a payment-fraud incident. A ransomware infection can become a business-continuity crisis. A stolen customer database can become a regulatory and reputational problem.

This is why businesses need to think beyond the question, “How do we stop malware?”

The better questions are: How quickly can we detect an attack? Can we identify what has been compromised? Can we contain it? Can we recover? And how much of the business can continue operating while the incident is being resolved?

Those are resilience questions.

The AI cybersecurity arms race has begun

The central question for Kenyan businesses is no longer whether AI will change cybersecurity because it already has. But the real question is whether defenders can adopt AI and automation quickly enough to keep pace with attackers.

INTERPOL’s latest assessment provides a clear warning: AI is enabling 55% of reported cybercrime across Africa, while criminals are using the technology to automate phishing, create deepfakes, develop synthetic identities and improve social engineering. 

Kenya is particularly exposed because its digital economy is built around precisely the systems cybercriminals are increasingly targeting: mobile money, digital payments, telecommunications, financial services and online platforms. INTERPOL’s finding that East Africa has emerged as a hub for mobile-money fraud and infrastructure-targeted ransomware should therefore be viewed as a business warning, not simply a law-enforcement statistic.

The answer cannot be to replace people with AI. Rather, businesses need to use technology to make their security teams more effective. AI can process enormous volumes of information, recognize patterns and help prioritize threats, while security professionals provide context, investigate incidents and make decisions about how an organization should respond. Neither works as effectively alone.

Kenya’s next digital chapter needs stronger security

Kenya’s digital economy is not slowing down. Mobile money, fintech, cloud computing, AI, e-commerce and digital public services will continue to expand. Every new layer of digital adoption will create new opportunities for businesses and new opportunities for cybercriminals.

Securing an organization won’t just need teams to prevent attacks but be able to identify threats early, understand what is happening, contain incidents quickly and recover with minimal disruption. That requires a shift from cybersecurity as a defensive product to cybersecurity as an ongoing business capability.

Designed around that shift, Kaspersky Next is bringing together protection, detection, investigation and response capabilities to help organizations gain greater visibility into modern threats and respond more effectively.

For Kenyan businesses, the message is increasingly clear. The same technologies that are accelerating digital transformation are also changing the threat landscape. AI gives criminals new tools to attack faster and at greater scale, but it can also give defenders the ability to process more information, identify threats earlier and respond more intelligently.

The cybersecurity battle in Kenya is becoming an AI battle and organizations that recognize that shift early and build their defenses accordingly will be better positioned to protect not only their systems, but their customers, their money and their ability to keep doing business.

Ready to strengthen your organization’s cybersecurity?

Learn more about Kaspersky Next and how AI-powered protection, detection and response can help your business prepare for the next generation of cyber threats.

Two Flexitech Directors Arrested Over Alleged $242,000 Misappropriation

0

Two directors of Kenya-based buy-now-pay-later firm Flexitech Group Limited have been arrested in connection with the alleged misappropriation of Sh31.2 million ($242,000) belonging to a leading retail chain.

The Directorate of Criminal Investigations (DCI) said Martin Kariuki Maina and Johnson Gituma Mwangi were arrested in Roysambu following investigations into a complaint filed by the retailer.

Flexitech had been acting as an agent for the retailer, collecting payments from customers who had purchased and collected goods from various branches.

According to the DCI, the company received Sh31,213,700.95 from customers for onward remittance to the retailer. Investigators allege that the funds were instead diverted for the personal use of the two directors, working with other suspects who remain at large.

The arrests were made by detectives from the DCI Nairobi Regional Office as they traced the funds and investigated the alleged involvement of other individuals.

Maina and Mwangi are being held ahead of their arraignment at the Milimani Law Courts, where they are expected to face charges of stealing by agent under Section 283(b) of the Penal Code.

Flexitech operates in Kenya’s consumer-financing market, providing buy-now-pay-later services that allow customers to acquire goods and pay for them over time. The sector includes other consumer-financing players such as Lipa Later, which shut down and Aspira. FlexPay is one of the innovative financial service products that has emerged from Kenya, the home of Africa’s first mobile money service, MPESA. FlexPay aims to bridge the affordability gap with practical and affordable financial services thus protecting customers from the dangers of debt.

The case puts a spotlight on the risks involved when consumer-financing companies and their agents handle large volumes of customer payments on behalf of merchants.

The DCI said investigations remain ongoing and detectives are pursuing other people believed to have been involved in the alleged diversion of the funds. The allegations have not been tested in court, and Maina and Mwangi are presumed innocent unless proven guilty.

Mbappé-Backed Tanel Acquired by Alan as French Healthtech Enters Africa

0

French health insurer Alan is buying Senegalese healthtech startup Tanel, taking its first step into Africa through a company backed by investors including football star Kylian Mbappé.

The acquisition gives Alan a foothold in two of West Africa’s fastest-growing healthcare markets and turns Tanel into the launchpad for an expansion that the companies expect will reach more than 1 million members across Africa by 2030.

Tanel, founded in 2021 by Mouhamed Ndoye and Makhtar Diop, has built a digital platform for managing employee health coverage in markets where healthcare administration remains heavily fragmented. The company operates in Senegal and Côte d’Ivoire, serving about 70,000 members at more than 400 companies and linking them to more than 1,200 pharmacies and healthcare providers.

Alan first backed Tanel in its 2024 seed round. The relationship has since evolved into an acquisition, giving the French company local infrastructure, healthcare partnerships and regulatory knowledge as it enters a continent where it previously had no operating presence.

The companies plan to strengthen their businesses in Senegal and Côte d’Ivoire before targeting Anglophone markets in West and East Africa. The first phase will focus on integrating their platforms, improving the digital patient experience and bringing Alan’s preventive healthcare and telehealth services to Tanel customers.

The deal is also an exit for Tanel’s founders and early investors, including Ventures Platform and AAIC Investment, as well as angel investors such as Dr. Mussaad M. Al-Razouki, Alyune-Blondin Diop and Charles “Chuck” Slaughter.

For Ventures Platform, which backed Tanel early, the transaction highlights the growing potential for African startups to attract strategic buyers despite a still-thin market for technology exits.

“African tech still sees too few exits, particularly in Francophone Africa,” Dotun Olowoporoku, Managing Partner at Ventures Platform, said. “Alan’s acquisition validates their vision and demonstrates the potential for ambitious, locally built companies to create lasting value.”

Alan has more than 1.2 million members across France, Spain, Belgium and Canada. Its entry into Senegal and Côte d’Ivoire gives it access to a regional health-insurance market estimated at almost €600 million, growing at about 10% annually.

For Alan co-founder and CEO Jean-Charles Samuelian-Werve, Tanel offers something difficult to build from scratch: an established network across local healthcare systems.

“Tanel has done the hard work of building relationships with users, companies, healthcare providers and regulators in Senegal and Côte d’Ivoire,” Samuelian-Werve said. “Combining that knowledge with Alan’s platform gives us a strong base from which to build in Africa.”

Ndoye and Diop will remain in charge of Tanel’s operations and Alan’s African expansion, with the startup’s full team staying in place.

Tanel began by building infrastructure for pharmacies before expanding into tools covering the broader healthcare journey, as the founders sought to replace paper-heavy processes with digital services.

The acquisition gives Alan a ready-made African operation while giving Tanel access to the technology, capital and product expertise of a European healthtech company. It also marks another major liquidity event for Africa’s startup ecosystem, where large strategic acquisitions remain relatively rare.

Uber Exits Nigeria and Uganda, Cuts 3,300 Jobs in Shift Toward Autonomous Mobility

Uber Technologies Inc. is shutting down its operations in Nigeria and Uganda, ending more than a decade in both markets as the ride-hailing company cuts about 3,300 jobs and shifts investment toward autonomous mobility.

The exits take effect Wednesday, September 2. Uber launched in Nigeria in 2014 and Uganda in 2016, meaning the withdrawals end 12 years of operations in Nigeria and 10 years in Uganda.

Uber said the decisions reflect changing business priorities and investment focus, rather than a broader retreat from Sub-Saharan Africa. Uber’s exit in Nigeria could be due to a weaker currency, high inflation, rising fuel and vehicle costs, expensive maintenance, pressure for higher driver earnings, and increasingly complex regulatory and operating requirements, while passengers have limited room to absorb higher fares. Those pressures squeeze margins from both sides and make continued investment harder to justify.

Uber stated clearly the exits from the Nigerian and Uganda markets are due to the changing business priorities and investment focus. The company will continue operating in Kenya, South Africa and Ghana. Uber launched in Egypt in 2014, initially in Cairo, and has expanded its services there and it has no signs of shutting down in these remaining markets.

The moves further reduce Uber’s African footprint after it suspended operations in Tanzania in 2022, following regulatory changes that affected fares and commissions. The company has therefore exited or suspended operations in three African markets while maintaining operations in three others.

Globally, Uber is eliminating about 3,300 positions, or roughly 10% of its workforce, in its biggest job reduction since the pandemic. Chief Executive Officer Dara Khosrowshahi said the company’s rapid expansion had created layers of management and organisational complexity that slowed decision-making.

The restructuring will flatten the company’s corporate structure and reduce fully remote roles, with savings redirected toward growth and innovation. Autonomous transportation is a major focus. Uber plans to invest more than $10 billion in robotaxis over the coming years through partnerships with companies developing self-driving technology.

The strategy positions Uber for a transportation market in which human drivers could increasingly compete with autonomous fleets. Rather than owning most of those vehicles, Uber wants its platform to connect riders with robotaxi operators.

In Nigeria, the departure is particularly significant. Uber has operated in the country since 2014 and its exit opens more room for competitors and local mobility companies to capture riders and drivers. The company has not identified regulatory disputes as the reason for leaving Nigeria, despite recent disagreements with the Federal Airports Authority of Nigeria over airport pick-up operations.

Uber’s latest restructuring signals a shift away from the rapid geographic expansion that defined much of its first decade toward a more concentrated strategy focused on efficiency, profitability and the emerging autonomous mobility market.

WIOCC Raises $300M from AFC and Vision Invest to Accelerate Expansion Across Africa

0

WIOCC Group, Africa’s top carrier-neutral digital infrastructure firm, has secured $300 million investment to expand its open-access, critical infrastructure across Africa at a pivotal moment when Africa’s demand for data, cloud services and artificial intelligence continues to grow.

The investment via a Shareholder Subscription Agreement (SSA) with Africa Finance Corporation (AFC) and Vision International Investment Company (Vision Invest) was signed at the LEAP 2026 Global Technology exhibition in Riyadh.

In a press statement seen by TechMoran, Chris Wood, Group Chief Executive Officer of WIOCC Group, said, “Africa is uniquely positioned to capitalise on the next phase of global digital growth. As demand for cloud, AI and digital services accelerates, robust and scalable infrastructure will be essential to unlocking the continent’s potential.”

Wood added that this investment will enable WIOCC to accelerate data centre deployment and consolidation, expanding open-access terrestrial fibre footprint and invest in new subsea assets to strengthen Africa’s digital infrastructure platform and enhance connectivity between the continent and key international markets.

According to the International Telecommunication Union (ITU), only 35.7% of Africa’s population was using the internet in 2025, compared with a global average of 73.6%, highlighting the scale of the continent’s digital infrastructure needs and growth potential. Meanwhile, the United Nations Conference on Trade and Development (UNCTAD) projects the global AI market will reach US $4.8 trillion by 2033, while warning that access to AI capabilities and digital infrastructure remains concentrated in a limited number of countries and companies. These trends underscore the importance of investing in resilient, high-capacity infrastructure that can expand digital access, support cross-border data flows and help narrow the digital divide.

WIOCC Group operates in more than 30 African countries with support from top firms such as International Finance Corporation (IFC) and African Capital Alliance (ACA) and various telcos across Africa. This new investment will helpit expand and serve more customers in these markets.

In December 2025, WIOCC raised $65 million in debt financing to expand its network and data centre footprint across the continent. The facility, structured as sustainability-linked debt, was arranged by the International Finance Corporation (IFC), Proparco, Emerging  Africa Infrastructure and Asia Infrastructure Fund (EAAIF), and asset manager Ninety-One.

In March the same year, WIOCC signed a colocation agreement with iColo, a carrier-neutral data centre provider to accelerate the growth of Internet Service Providers (ISPs) in Mombasa and across Kenya. The collaboration was expected to enhance digital infrastructure, improve interconnectivity and unlock new market opportunities for ISPs, ultimately contributing to Kenya’s rapidly expanding digital economy.

“The Africa we build must be connected, competitive and equipped to create value from the digital economy, not only consume it,” said Samaila Zubairu, President & Chief Executive Officer of AFC, “Just as transport corridors enable trade and energy networks power industry, fibre, data centres and subsea cables are now essential infrastructure for growth, innovation and AI. Our investment in WIOCC will expand the open-access digital backbone African businesses and communities need to integrate, innovate and compete globally.”

Together, AFC, Vision Invest and WIOCC aim to contribute to accelerating the development of Africa’s digital ecosystem and supporting the continent’s growing role in the rapidly evolving global digital economy.

‘WIOCC Group has built one of Africa’s leading digital infrastructure platforms, and we are proud to partner together with AFC and WIOCC’s existing shareholders as the company enters its next phase of growth. Home to the world’s youngest population and expected to account for more than one-quarter of the global population by 2050, demand for digital services in Africa will continue to rise, necessitating impactful investments in connectivity and digital ecosystems to unlock new opportunities for innovation, economic diversification and sustainable growth as well as opportunities for businesses, innovators and communities across Africa,” concluded President & Chief Executive Officer of Vision Invest, Omar N. Al-Midani.

How Zero-Fee Digital Transactions Are Changing Customer Loyalty in Banking

0

For decades, Kenyan banks competed on branch networks, lending products, interest rates and the strength of their customer service. However, things are a bit different today as customer loyalty is no longer shaped by customer service and branch networks but the cost and convenience of moving money.

This is partly due to the digital transformation amongst the banking sector Kenya and a digital payments revolution that has fundamentally changed how people interact with financial institutions from the banking hall to their mobile phones. Banking is no longer an occasional activity confined to branches as the mobile phone allows customers to transfer money, pay suppliers, settle school fees, receive salaries, shop online and move funds between accounts from almost anywhere in the world. 

With the convenience of the mobile phone, the major issue has been the cumulative impact of transaction fees and not access to funds like it was a decade ago. 

According to the World Bank’s Global Findex 2025, “Across low- and middle-income economies, 61 percent of adults, or 82 percent of account owners, made or received a digital payment in 2024, a 27 percentage point increase from 2014. Digital payments are the most popular formal financial service, used by twice as many adults as saved formally and by three times as many as borrowed formally. 

Use of digital merchant payments to businesses in stores or online grew to 42 percent of all adults in 2024, up from 35 percent in 2021, with variations by region. The share of adults making such payments more than doubled in some economies, including Cameroon, the Kyrgyz Republic, Paraguay, and Viet Nam, and showed widespread adoption in Kazakhstan, Kenya, and Mongolia.

The numbers illustrate just how deeply digital finance has become embedded in everyday life. The report adds that mobile phones and the internet have revolutionized financial inclusion, enabling more people to access and use digital financial services to manage their financial lives. From mobile money accounts on basic phones to bank-account-linked wallets on smartphones, digital services are fulfilling their promise of being more accessible and affordable than alternatives that are not digitally accessible, bringing daily utility payments, savings, deposits, withdrawals, loan disbursements and repayments to them via apps.

The World Bank’s latest Global Findex data shows 94% of Kenyan adults own a financial account, while 89% made or received a digital payment during the previous year. Digital transactions are no longer simply an alternative to cash; for millions of consumers, they are the default way of managing money.

That shift has changed what customers expect from their banks and increasingly, people are not choosing a financial institution based solely on its loan products, branch footprint or savings rates but the cost of access to these funds. 

Every Transaction Shapes Loyalty

Because of the need for instant access powered by technology, a successful transaction builds confidence while a delayed payment creates frustration. Also a recurring fee may appear insignificant, but when it is attached to dozens of transactional costs over a month, customers begin to notice.

This is where the cost of transaction becomes important and not just access to the funds. Consumers tend to notice frequent costs that recur on their deposits, withdrawals, utility payments, transfers, or remittance and start questioning access vs affordability on the cost of banking. Over time, those charges have influenced the loyalty of customers and how customers perceive the value they receive from their financial institution.

Recent PesaLink research highlights the changing priorities of Kenyan consumers. 64% of account-to-account payment users surveyed said affordability influences their choice of payment service, while more than 60% identified speed and convenience as important factors. The study also found that 57% of users maintain relationships with multiple financial institutions.

That last figure is particularly important for banks. Customers are increasingly comfortable maintaining several banking relationships. A salary may be paid into one bank, savings held elsewhere and everyday transactions handled through another institution or digital wallet. This gives consumers more choice and makes loyalty harder for banks to take for granted.

If another institution can provide the same service faster and at a lower cost, switching becomes increasingly easy.

The Digital-First Customer

Kenya’s financial ecosystem has produced a customer who is comfortable with digital financial services and increasingly unwilling to tolerate unnecessary friction. The modern customer may never visit a branch. Instead, their relationship with a bank is built through an app, a payment notification, an ATM or an account-to-account transfer.

They expect to pay a supplier while sitting in a café, send money to a family member from work, settle a bill from home or transfer funds between accounts late at night. The technology itself is becoming less important to the customer. What matters is the outcome like did the money arrive, how quickly did it arrive, was the transaction secure and most importantly how much did it cost?

These questions are becoming more important than the number of features a bank has added to its mobile application.

SMEs Feel the Difference

The impact is particularly significant for small and medium-sized enterprises. Speaking to TechMoran, Mbugua Njihia, a Kenyan technologist said cost is more important than access especially for SMEs which form the bulk of the Kenyan economy.

‘’An SME may make multiple payments to suppliers, employees, distributors and service providers every day,’’ he said. ‘’It may also receive hundreds of customer payments over the course of a week and for a business operating on tight margins, transaction fees can quickly become a recurring operating expense and it will soon be an issue of moving banks or payment service providers.”

To him, the banks of the future, therefore, need to remove those costs as they can have a major effect beyond customer convenience. The cost of access can keep a client as those little recurring transactions can help a business retain more working capital, simplify reconciliation and make digital payments more attractive. “Cashflow is key to SMEs,’’ he adds.’

The same principle applies to freelancers and independent professionals. A freelancer may receive payments from several clients, move income into savings, pay subscriptions and transfer money to suppliers or family members. Each transaction represents another point at which a bank can either create friction or remove it.

Families Are Changing Too

For households, digital payments have become equally important as most parents  are using digital channels to pay school fees and household bills. Families send money to relatives in different towns. Young professionals move funds between savings, investment and spending accounts. In Kenya, these are not occasional banking activities but part of everyday financial life.

When a customer repeatedly pays for routine transactions, the cumulative cost becomes part of their perception of the bank. This is why zero-fee payments can have an impact beyond the immediate amount saved. They create a sense that the bank is working with the customer rather than charging them for every movement of their own money.

Real-Time Payments Raise the Bar

Kenya’s expanding instant-payment infrastructure is reinforcing these expectations. PesaLink, the country’s real-time account-to-account payment network, now connects more than 80 banks, SACCOs and financial institutions, serves more than three million users and has processed over KES 1 trillion in transactions.

That scale matters because it demonstrates how quickly consumers and businesses have become accustomed to moving money electronically. Once customers experience instant transfers, waiting for funds to clear becomes increasingly difficult to justify. Similarly, once consumers become accustomed to lower-cost transactions, recurring charges can start to feel outdated. The result is a new baseline for banking. Speed is expected. Security is expected. Convenience is expected. Increasingly, affordability is expected too.

How SBM Bank Kenya Is Responding

This changing behaviour is reflected in SBM Bank Kenya‘s approach to digital payments. Through its Mfukoni App and #TumaForFree campaign, the bank is offering customers free PesaLink and interbank transfers, removing transaction charges on eligible transfers and reducing the cost of moving money between financial institutions.

The significance is less about a single fee and more about the changing economics of customer engagement. Customers frequently need to move money between different banks, whether paying suppliers, sending money to family, settling bills or managing funds across accounts. Removing the transfer charge can make these everyday transactions more affordable while reducing friction.

For SMEs in particular, the savings can accumulate over time. A business making multiple payments to suppliers, employees and service providers can turn transaction charges into a recurring operating expense. A zero-fee transfer proposition can therefore help businesses retain more working capital while making digital payments more attractive.

For individual customers, the proposition is similarly straightforward: where a transfer qualifies under the offer, customers can move money without paying an additional transfer fee. The benefit is not that all banking services at SBM Bank are free, but that eligible PesaLink and interbank transfers can be made at zero transaction cost.

SBM’s broader performance also provides context for its digital strategy. In the first half of 2026, the bank reported profit before tax of KES 547 million, up 171% from KES 202 million a year earlier. Customer deposits reached approximately KES 94 billion, while total assets stood at about KES 126 billion.

The figures do not prove that zero-fee transactions alone drove the growth. Rather, they show the broader environment in which the bank is expanding its digital and customer-focused strategy.

The Global Shift

Kenya’s experience is part of a much larger transformation. Worldwide, consumers are moving rapidly towards digital and real-time payments. McKinsey has identified payments as one of the most important areas of financial services transformation, with customers increasingly demanding instant and seamless experiences.

PwC has projected strong growth in global non-cash payment volumes, driven by the adoption of digital wallets, account-to-account payments and real-time payment systems. Meanwhile, estimates from Africa’s payments industry suggest that the continent’s digital payments ecosystem could reach US$1.5 trillion by 2030.

For banks, this represents both an opportunity and a challenge. As payment infrastructure becomes more interoperable, customers gain more freedom to move money between institutions. The bank that retains the customer will increasingly be the one that provides the best overall experience rather than simply the institution where the customer first opened an account.

Loyalty Through Less Friction

For years, banks invested heavily in acquiring customers by having more branches, launching mobile applications, introducing loyalty programmes and expanded product portfolios but the next challenge is keeping those customers.

Zero-fee transactions are one way of doing that because they address something customers experience repeatedly. Every time a customer transfers money without an additional charge, the bank removes a small point of friction. Repeated hundreds of times, those experiences can shape perception.

That is why the economics of banking loyalty are changing. Customers may appreciate a sophisticated app, but they are likely to remember whether the bank made everyday financial tasks easier and more affordable. The competitive advantage may therefore shift from having more features to creating fewer obstacles.

For SBM Bank Kenya, the proposition is ultimately about reducing the cost of everyday money movement. The bank is positioning zero-fee eligible transfers not as a claim that banking itself is free, but as a way of removing one of the most frequent costs customers encounter when moving money between financial institutions.

As digital payments become the infrastructure of modern commerce, every transfer becomes an opportunity to reinforce or weaken the relationship between a bank and its customers. Making eligible transfers free can turn a routine transaction into a point of customer value.

The future of banking will not necessarily belong to the institution with the most products or the most elaborate app. It may belong to the bank that makes thousands of everyday financial decisions feel effortless, affordable and secure. For customers, zero-fee transfers are increasingly becoming part of that expectation.

Uganda, Kenya Target Tourism Investment, Innovation and Regional Mobility

0

Uganda and Kenya are seeking to unlock investment and business opportunities in tourism, technology and innovation while addressing barriers to seamless movement across East Africa.

The agenda will feature at the fifth Uganda–Kenya Coast Tourism and Innovation Summit, scheduled for Oct. 26–27 at Sarova Whitesands Beach Resort & Spa in Mombasa. The summit will bring together government, tourism, technology, investment and private-sector representatives from the two countries.

Held under the theme, “Unlocking Tourism Opportunities: Resolving Policy Bottlenecks through Technology, Youth and Seamless Mobility across East Africa,” the summit will focus on practical solutions to policy and operational challenges affecting tourism and cross-border business.

Technology and youth innovation will be central to the discussions, with digital solutions expected to be showcased alongside opportunities in tourism investment, smart destinations and connectivity.

“This Summit reflects the strength of the partnership Uganda has built with our friends on the Kenya Coast over the past five years. As we mark ten years of the Consulate’s presence in Mombasa, we are moving beyond dialogue to concrete, action-oriented cooperation, particularly in harnessing technology and youth innovation to unlock the full potential of tourism between our two countries,” said Amb. Herbert Kiguli, Consul General of the Republic of Uganda in Mombasa.

Since 2022, more than 450 stakeholders have participated in the Uganda–Kenya Coast familiarisation programme, helping tourism operators build relationships and promote complementary destinations across the two markets.

Regional mobility will also be a key focus, with participants examining challenges affecting tourism and business travel under Article 104 of the East African Community Treaty, which provides for the progressive removal of restrictions on the movement of persons, labour and services.

Key tourism stakeholders came together for the launch of the 5th Uganda-Kenya Tourism & Innovation Summit 2026 which took place in Mombasa, Kenya. The Summit, convened by the Consulate General of Uganda in Mombasa will bring together stakeholders on the 26th to the 27th of October 2026 under the theme “ Unlocking Tourism Opportunities: Resolving Policy Bottlenecks through Technology, Youth and Seamless Mobility across East Africa

Easing such barriers could support cross-border tourism, investment and commercial activity by making it easier for tourists, businesses and service providers to operate across the region.

“Mombasa County is proud to welcome this Summit as a platform that puts our tourism offering firmly on the regional stage. We see real value in deepening ties with Uganda, particularly in opening up smart, tech-enabled and youth-driven approaches to tourism that benefit both our destinations,” said Hon. Mohammed Osman, County Executive Committee Member for Tourism, Mombasa County.

The summit will feature policy discussions, innovation showcases and business-to-business engagements and is expected to produce a Summit Communiqué outlining priorities and timelines for follow-up.

The event also marks the fifth annual engagement between the Ugandan Consulate and Kenya Coast stakeholders and coincides with the 10th anniversary of the Consulate’s active presence in Mombasa.

The organizers say the summit will contribute to East African integration by positioning tourism, innovation, technology and seamless mobility as drivers of investment and regional economic growth.

Doage Launches to Help African InsurTechs Bridge the Commercialisation Gap

0

Doage, a new insurance technology advisory and commercialisation platform founded by insurance executive Dominic Agesa Kavugwi, has launched with a focus on helping African InsurTech startups convert innovation and investment into sustainable commercial growth.

The launch comes as Africa’s InsurTech industry continues to attract record investment while founders face increasing pressure to demonstrate revenue growth and long-term viability. AfricInvest’s 2026 African InsurTech Landscape report estimates that more than US$300 million has been invested in African InsurTech startups over the past five years, with annual funding reaching a record US$80.6 million in 2025. The report forecasts Africa’s insurance market will expand from US$92.9 billion in 2024 to US$160.9 billion by 2033.

The broader African startup ecosystem has also become more selective. Only 178 African technology startups secured funding in 2025, although total investment recovered to more than US$1.6 billion, underscoring investors’ growing focus on businesses capable of delivering commercial returns.

Kavugwi said the challenge facing many startups is no longer developing innovative products or raising capital, but successfully taking those products to market.

“Africa does not have a shortage of innovation. What we still have is a commercialisation gap,” he said.

Doage will advise InsurTech startups, insurers, investors and international technology companies on commercial strategy across African markets. Its services include go-to-market planning, enterprise distribution, strategic partnerships, market entry, expansion, investor readiness and revenue growth.

The company said it is positioning itself as a commercialisation partner rather than another accelerator, working with businesses after product development and fundraising to help secure customers, distribution partnerships and sustainable revenue.

It also plans to work with venture capital firms and accelerator programmes to support portfolio companies after investment, helping translate funding into measurable commercial outcomes.

“Investors are very good at allocating capital. Accelerators are very good at identifying and preparing entrepreneurs. Insurers understand risk. Founders understand the problems they are solving. But there is still a question between all of them: who owns commercialisation?” Kavugwi said.

Doage is also developing what it describes as an Africa–Global InsurTech Corridor to connect African startups with international insurers, investors and technology companies, while supporting overseas insurance technology firms seeking to enter African markets through local partnerships instead of building operations from scratch.

According to AfricInvest, 86% of African InsurTech venture funding remains concentrated in South Africa, Kenya, Nigeria and Egypt, highlighting opportunities to expand insurance innovation into other markets across the continent.

Kavugwi, whose career spans insurance, bancassurance, embedded insurance, digital distribution and strategic partnerships, said the industry’s next phase should be measured by sustainable businesses rather than funding alone.

“The next phase of African InsurTech cannot only be about how many startups we accelerate or how much money we raise,” he said. “We also have to ask how many sustainable insurance businesses we build, how much revenue they generate, how many markets they enter and ultimately how much enterprise value they create.”

The Nairobi-based venture is betting that commercial execution, rather than access to capital alone, will determine the next generation of winners in Africa’s growing InsurTech market.

Google to Withhold 5% From Kenyan YouTube Creators’ Earnings

0

Google will begin withholding 5% from eligible YouTube earnings paid to Kenyan creators from September, with the company set to remit the deducted amount to the Kenya Revenue Authority (KRA) in line with the country’s tax requirements.

The withholding will apply to YouTube earnings processed through Google’s AdSense system for creators whose tax residence is Kenya. The deduction will be made before creators receive their payouts.

For a creator with KSh100,000 in eligible earnings, the 5% withholding would amount to KSh5,000, leaving KSh95,000 before any other applicable deductions.

Google has asked affected creators to provide a valid KRA Personal Identification Number through their AdSense accounts. The deadline for submitting a verified KRA PIN is Oct. 1, 2026.

Creators who fail to provide the required tax information could face restrictions affecting their payments.

The new withholding comes as Kenya increases its focus on income generated through the digital economy. YouTube has become an important revenue source for creators, with advertising, memberships and other monetisation tools supporting a growing ecosystem of online businesses.

The 5% withholding is not necessarily a creator’s final tax liability. Additional taxes may apply depending on a creator’s total income and individual circumstances.

For creators operating YouTube channels as businesses, the change could affect cash flow, revenue forecasts and production budgets. It also makes the distinction between gross YouTube revenue and actual take-home income increasingly important.

The move highlights the growing integration of global digital platforms into domestic tax systems, with Google effectively becoming part of the collection and remittance process for tax due on eligible creator earnings.

Tim Cook Steps Down as Apple CEO After Nearly 15 Years at the Helm

0

Tim Cook has finally stepped down as chief executive officer of Apple, bringing an end to nearly 15 years leading one of the world’s most valuable technology companies.

In a message to Apple employees on his final day as CEO, Cook reflected on his tenure, thanking the company’s employees and describing his time leading Apple as “the privilege of a lifetime.”

“Today is my last day as CEO of Apple,” Cook wrote. “I love this company and the team behind it, and I couldn’t let this day pass without sending a note to you, to tell you how grateful I am.”

Cook, who succeeded Apple co-founder Steve Jobs as CEO in August 2011, credited Apple’s employees for the company’s achievements during his tenure. He said whatever success was attributed to him was ultimately the result of the people he led.

“The truth is, whatever there is to say about my success, I know it is all because of you,” Cook said. “You have brought out the best in me.”

A leadership era comes to an end

Cook’s tenure has been defined by Apple’s expansion beyond the iPhone into a broader ecosystem of hardware, software and services. Under his leadership, the company launched products including the Apple Watch, AirPods and Vision Pro, while transitioning its Mac lineup to Apple-designed silicon.

The firm also significantly expanded its services business, with products including Apple Music, Apple TV+, Apple Pay, iCloud and other subscription offerings becoming increasingly important to the company’s growth. Cook also presided over the firm’s growing focus on privacy, environmental sustainability and artificial intelligence, including the company’s push into Apple Intelligence.

In his farewell message, however, Cook said the achievements that mattered most to him were not those captured in the firm’s financial reports.

“There is something truly special about Apple,” he wrote. “I am most proud of what an annual report could never capture. This place is proof that culture triumphs over everything.”

He said the firm’s culture is built around the belief that its products and work should make a meaningful difference in the world.

Cook will remain at Apple

Although Cook is leaving the CEO position, he emphasized that he is not leaving Apple.

“As you know, I am not leaving Apple. But I am stepping away from a role that I have loved deeply,” he wrote.

Cook said he would miss leading the company but remained at peace with the decision. He also expressed confidence in his successor John Ternus.

“I take enormous comfort in handing the helm to someone as brilliant and wonderful and capable as John,” Cook wrote. “Few people understand what it takes to build products that change the world the way John does and I could not be more excited for his leadership.”

The transition marks a significant moment for the firm as it enters a new phase of leadership while confronting intensifying competition in artificial intelligence, evolving consumer technology markets and continued regulatory pressure.

Cook is transitioning to executive chairman and will still be around the firm though not on a day-to-day basis. “With all I have and all I am, I am always yours,” he wrote. Cook became Apple’s CEO on August 24, 2011, succeeding Steve Jobs. His departure from the CEO role closes one of the longest and most consequential chapters in Apple’s modern history, while his continued presence at the company is expected to provide continuity as the new leadership team takes over.

Swedfund Invests $20 Million into Africa Go Green Fund to Scale Energy Efficiency in Africa

Swedfund has provided a $20 million loan to the Africa Go Green Fund to invest in firms that reduce emissions and improve energy efficiency across Africa in areas such as green buildings, clean cooking, green transport and industrial energy efficiency.

According to Gunilla Nilsson, Investment Director and Head of Energy and Climate at Swedfund, “Energy efficiency is one of the most practical ways to reduce emissions while lowering costs. Through this investment, Swedfund will support companies providing solutions that people use in everyday life, from cleaner cooking to more energy efficient housing and transport.”

Energy demand in Africa continues to grow, while many companies in the energy efficiency space lack financing that matches their long-term investment needs. This limits the scale up of solutions that can reduce emissions, lower costs and improve the reliability of essential services.

The Africa Go Green Fund has already financed close to 30 projects across 17 countries in Africa and is expanding its lending activities to reach more companies providing energy efficiency solutions.

Swedfund’s investment will strengthen the fund’s capacity to provide financing to companies that can deliver significant climate benefits but often struggle to access debt on suitable terms. By investing alongside other public and private investors, Swedfund also helps mobilise additional capital for energy efficiency solutions across Africa.

Samsung Launches Galaxy S26 FE in Kenya at KES 103,100

Samsung has launched the Exynos 2600-powered Galaxy S26 FE in Kenya, bringing flagship AI features, upgraded cameras and seven years of software support to a more accessible price point.

Available from September 4, the smartphone is the first Fan Edition device to ship with One UI 9, offering AI-powered tools designed to boost productivity, photography and content creation.

“The Kenyan market represents one of the most vibrant mobile ecosystems on the continent, where technology serves as a vital engine for productivity, entrepreneurship and everyday communication,” said Manish Jangra, Head of Mobile Experience at Samsung Electronics East Africa.

Here’s the revised paragraph:

The Galaxy S26 FE is powered by Samsung’s next-generation Exynos 2600 processor, the processor on Galaxy S26 built on a 3nm architecture. It delivers improved AI performance, stronger graphics, enhanced camera processing and greater power efficiency, supporting smoother multitasking, gaming and everyday use.

The Galaxy S26 FE features a 6.7-inch Dynamic AMOLED 2X display with a 120Hz refresh rate, a 4,900mAh battery with 45W fast charging, and IP68 water and dust resistance. Samsung has also committed to providing seven Android OS upgrades and seven years of security updates, matching support offered on its flagship devices.

On the camera front, the phone includes a 50MP main sensor, 12MP ultra-wide camera and 8MP telephoto lens with 3x optical zoom. AI features such as Photo Assist, Gemini Omni, My FanCam and Super Steady with Horizontal Lock are designed to simplify editing and improve photo and video capture.

The 8GB RAM/256GB storage model will retail at KES 103,100 in Blueberry, Pistachio and Graphite. Kenyan buyers will also receive Samsung Care+, a six-month Google AI Pro subscription, and access to Smart Switch for easy data transfer from Android and iOS devices.

Samsung Galaxy S26 FE Specs

CategorySpecification
PriceKES 103,100
AvailabilitySeptember 4, 2026
Memory & Storage8GB RAM + 256GB
Display6.7-inch Dynamic AMOLED 2X, 120Hz
Rear Cameras50MP + 12MP Ultra-wide + 8MP Telephoto (3x Optical Zoom)
Battery4,900mAh
Charging45W Fast Charging
Operating SystemOne UI 9
Software Support7 Android OS upgrades, 7 years of security updates
AI FeaturesGemini Omni, Photo Assist, My FanCam, Super Steady
DurabilityIP68 Water & Dust Resistance
ColoursBlueberry, Pistachio, Graphite
Included OffersSamsung Care+, 6-month Google AI Pro subscription

Terra Industries Hires Former WHOOP, Palantir Executive to Lead Commercial Expansion

0

Terra Industries has appointed former WHOOP executive and Palantir alumnus Todd Stiefler as its Director of Commercial, strengthening its leadership team as the defense technology startup expands sales of its autonomous security systems across critical infrastructure markets in the Global South.

The appointment brings aboard an executive with experience scaling enterprise businesses and navigating government and regulated-sector customers. At Terra, Stiefler will help lead the company’s commercial division, focusing on customers that own and operate critical infrastructure.

Before joining Terra, Stiefler served as Vice President of Enterprise at wearable technology company WHOOP, where he oversaw business-to-business growth across government and defense, corporate wellness and other enterprise segments.

Earlier, he worked in business development at data analytics firm Palantir Technologies, helping build go-to-market teams for Apollo and FedStart, platforms aimed at accelerating adoption of software by defense technology companies and U.S. government customers.

Terra said Stiefler’s background in enterprise sales, commercial partnerships and regulated industries will support the deployment of its autonomous security systems in emerging markets.

The hire comes as Terra seeks to broaden its commercial footprint beyond product development, targeting operators of energy, transport and other critical infrastructure across Africa and the wider Global South.

The announcement also prompted questions from industry observers about whether Stiefler’s experience selling to U.S. government agencies would primarily help Terra pursue American customers or adapt those commercial strategies for sovereign buyers in emerging markets, where procurement processes differ significantly.

Terra has said its commercial strategy is centered on bringing autonomous security technologies to organizations responsible for safeguarding critical infrastructure in developing economies.

SBM Bank Kenya Extends $17 Million to Safer Power for Green Manufacturing Expansion

SBM Bank Kenya will provide $17 million in financing to Safer Power Group to expand local manufacturing of power infrastructure through the construction of a new factory and workshop, as the lender increases support for Kenya’s green industrial sector.

Safer Power, a licensed Schneider Electric panel builder, will use the funding to scale production of switchboards, control panels, distribution boards, synchronization panels and other electrical equipment used in commercial and renewable energy projects.

The investment comes as East Africa’s renewable energy market, valued at $4.3 billion in 2025 by IMARC Group, continues to grow on rising industrial demand. The International Renewable Energy Agency estimates that expanding clean energy and localized manufacturing could raise regional GDP by up to 6.4% while creating thousands of skilled jobs.

“Access to targeted capital is no longer just an ESG obligation. It is a necessary catalyst to unlock industrial resilience and energy sovereignty for our economy,” SBM Bank Kenya Chief Risk Officer Edgar Mwandawiro said.

Safer Power Chief Executive Officer Dalmus Mbai said the financing would help reduce dependence on imported equipment while supporting local engineering and manufacturing capacity.

The transaction aligns with SBM Bank’s strategy of increasing lending to businesses. The lender’s net loan book rose 18.3% year-on-year to KSh 54.09 billion at the end of June, surpassing KSh 50 billion for the first time as it expanded financing to micro, small and medium-sized enterprises.

How Fintech and Mobile Money Are Transforming Online Betting inEast Africa

East Africa has become one of the world’s most exciting frontiers for fintech innovation. From M-PESA’s invention in Kenya over fifteen
years ago to the explosive growth of mobile wallets across Tanzania, Uganda, and beyond, the region has leapfrogged traditional banking
infrastructure and built a digital payments ecosystem that now powers everything from remittances to retail commerce. One of the sectors
feeling this shift most acutely is online sports betting — an industry that lives or dies by the speed, convenience, and trustworthiness of
its payment rails.

For decades, the biggest barrier to online betting in East Africa wasn’t technology or appetite. It was friction. Players who wanted to
place a bet had to navigate bank transfers, agent networks, or cash-handling systems that were slow, expensive, and often unreliable.
A punter in Nairobi who wanted to back Gor Mahia on a Saturday afternoon might wait hours for a deposit to clear — if it cleared at
all. That friction didn’t just frustrate users; it capped the entire market’s potential.

Mobile money changed everything. When M-PESA made it possible to move money with a few taps on a feature phone, it didn’t just create a new payment method — it created a new consumer behaviour. Kenyans learned to trust digital balances, instant transfers, and SMS confirmations. That trust became the foundation upon which entire digital industries
could be built, including online betting.

Today, platforms like FungaBet are capitalising on that foundation by embedding mobile money directly into the betting experience. Instead of treating M-PESA as an add-on or a secondary option, modern betting platforms are building their entire deposit and withdrawal flows around it. A player can deposit via M-PESA in seconds, place a bet on the English Premier League or the FKF Premier League, and withdraw winnings back to their mobile wallet without ever touching a bank account. The entire cycle — deposit, bet, win, withdraw — happens within a closed loop of digital trust.

But the transformation goes beyond speed. Fintech has also made it possible to localise the betting experience in ways that were
previously impossible. Platforms can now price in Kenyan shillings, offer Swahili-language interfaces, and tailor bonuses to local payment
habits. A welcome bonus that requires a card deposit would exclude the vast majority of East African bettors. A bonus built around M-PESA —deposit via mobile money, get a 200% match — speaks directly to how people actually manage their money.

The rise of stablecoins and cryptocurrency is adding another layer. While mobile money dominates the mass market, a growing segment of
tech-savvy East Africans are using USDT and other stablecoins for betting. This gives platforms a hedge against currency volatility,
reduces transaction costs for high-volume players, and opens the door to cross-border betting without the friction of traditional foreign
exchange. The most forward-thinking operators are now offering both M-PESA and USDT side by side, letting players choose the rail that
suits them best.

Tanzania is the next frontier. While Kenya’s betting market is more mature, Tanzania’s mobile money ecosystem — driven by Vodacom’s
M-PESA, Tigo Pesa, Airtel Money, and Halopesa — is equally robust. As platforms expand across borders, the ability to support multiple
mobile money providers in multiple currencies becomes a competitive advantage. A betting platform that can accept Tigo Pesa in Dar es
Salaam and M-PESA in Nairobi, settle in local currency, and manage liquidity across both markets is built for the reality of East African
fintech.

Of course, growth brings responsibility. The same fintech rails that make betting accessible also make it easier to enforce responsible
gambling measures. Digital-first platforms can set deposit limits, monitor patterns of problematic behaviour, and implement KYC (Know
Your Customer) checks at registration — something that was nearly impossible in the cash-dominated era. The best operators are treating
compliance not as a cost centre but as a trust signal. Players who know their platform is licensed, regulated, and actively monitoring
for fraud are more likely to stay loyal.

The convergence of fintech and betting in East Africa is still in its early chapters. As smartphone penetration deepens, internet costs
fall, and mobile money interoperability improves, the addressable market will only grow. The platforms that win will be those that treat
payments not as plumbing but as product — designing every deposit, bet, and withdrawal around the real financial habits of East African
users.

FungaBet is betting on exactly that vision: a platform built mobile-first, localised for East Africa, and powered by the payment
rails that already move billions of shillings every day. The technology is ready. The market is ready. The only question is how
fast the rest of the industry catches up.