Home Blog Page 4

Microsoft Names Angela Nganga East Africa Country Lead as AI Push Accelerates

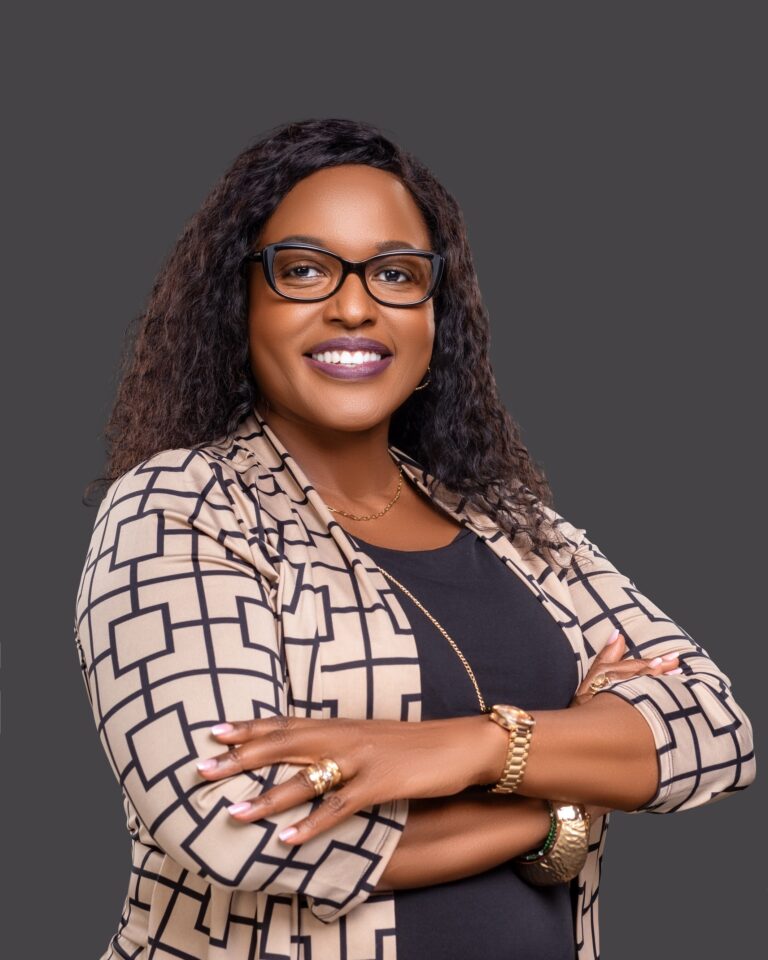
Microsoft has appointed Angela Nganga as its Country Lead for East Africa, putting an experienced regional executive at the helm as the technology giant expands its focus on artificial intelligence, digital transformation and local innovation.

Nganga will lead Microsoft’s engagement with governments, businesses and technology stakeholders across Kenya and the broader East African region, with a mandate that includes expanding AI skills, supporting workforce readiness and strengthening partnerships across the region’s technology ecosystem.

“I am delighted to lead Microsoft’s work in East Africa as the region strengthens its position as an innovation and AI hub,” Nganga said. “I look forward to partnering with governments, enterprise and the local startup ecosystem to build AI skills and workforce readiness, and to help partners develop and scale locally relevant solutions to real-world challenges.”

She added that enabling East African companies to become producers as well as consumers of AI innovation will be critical to the region’s participation in the global digital economy.

Based in Nairobi, Nganga joined Microsoft in 2012 and has held several senior positions across the company’s Middle East and Africa business. Most recently, she served as Regional Director of Customer Success for East and West Africa.
Her previous roles include Director of Corporate Affairs for the Middle East and Africa and Education Industry Director for Africa, where she was involved in customer success, digital transformation and strategic engagements across the continent.

Nganga brings more than two decades of experience spanning technology, telecommunications, healthcare, public affairs and policy. Before joining Microsoft, she held senior corporate affairs and public policy positions at Telkom Kenya and AAR Health Services Ltd.

Her appointment comes as East Africa’s technology market enters a new phase of AI adoption, building on the region’s established strengths in mobile technology, fintech and digital services.
Microsoft said Nganga’s leadership will support its efforts to advance inclusive digital and AI transformation while deepening investment in local innovation, skills development and strategic partnerships.
The region’s young population and growing startup ecosystem have also created opportunities for technology companies to develop solutions tailored to local markets. For Microsoft, the focus increasingly extends beyond deploying technology to building the skills, partnerships and businesses needed to create it.

Nganga’s appointment therefore places regional leadership at the center of Microsoft’s broader AI strategy, as governments and businesses across East Africa look to use artificial intelligence to improve productivity, create new services and build globally competitive technology companies.

Microsoft said the appointment reinforces its commitment to East Africa’s role in the global digital economy.

Afrikrea Returns as Consumer Marketplace as ANKA Focuses on B2B Services

Afrikrea is returning as the consumer-facing marketplace for African and diaspora fashion, art and crafts, while parent company ANKA focuses its other products on business-to-business commerce services.

The move marks the 10th anniversary of Afrikrea, which was founded in 2016 to connect independent creators across Africa and the diaspora with customers around the world.

Under the new structure, Afrikrea will be the platform where consumers shop, while ANKA Pay and ANKA Ship will serve as B2B software products. The company said the relaunch restores the original brand as it renews its focus on its founding mission.

“Fashion is where culture, craft, and commerce meet. Throughout my career, I have seen that the strongest businesses begin with a distinct creative point of view,” said Matilda Ceesay, CEO. “Afrikrea is returning to the name that carries that point of view: a home for African and diaspora creators whose work deserves to be seen, valued, and built into enduring businesses.”

Since its launch, Afrikrea has generated more than $30 million in sales for creators, giving the marketplace a decade-long track record in connecting African and diaspora businesses with international consumers.

The platform now connects creators in 94 countries, including 39 African countries, with buyers across 185 markets. More than 74% of its creators are women-led businesses, with consumers concentrated primarily in Europe and North America.

Afrikrea has also built a sizeable audience around its marketplace, with more than 700,000 community followers and 49,000 newsletter subscribers. Its physical pop-up events have generated hundreds of thousands of dollars in sales in less than a week, while the platform has recorded more than 125,000 five-star orders.

The restructuring separates Afrikrea’s consumer marketplace from the technology infrastructure built around it under ANKA. That allows the original Afrikrea identity to focus on shoppers and creators, while ANKA Pay and ANKA Ship remain positioned as tools for businesses handling payments and shipping.

The relaunch comes as African creators and small businesses increasingly use digital commerce and cross-border platforms to reach customers outside their domestic markets. For Afrikrea, that international connection has been central to its business since its founding.

The company said the next phase of Afrikrea will remain focused on helping independent creators reach global consumers, with the belief that where a creator starts should not determine how far their business can go.

How Virtual Gaming Became Africa’s Fastest Growing Digital Entertainment Sector

I’ve been tracking Africa’s digital entertainment evolution for 18 years, and the transformation still catches me off guard. Back in 2007, I remember trying to load a single YouTube video and giving up after 47 minutes. Fast forward to today and we’ve got sophisticated virtual platforms processing millions of transactions daily across the continent.

Nobody saw it coming this fast.

Here’s what I found fascinating: everyone got distracted by social media and streaming wars, but virtual gaming quietly built massive infrastructure underneath everything. I’m talking about platforms mixing sports simulation with instant-play formats and real-time engagement, all running on devices everyone already carries.

The Technology That Made It Possible

Mobile penetration reached 83% across sub-Saharan Africa by late 2023. I spent months looking at payment trends, and something jumped out: mobile money transactions surged 34% year-over-year, with huge portions coming from entertainment and gaming platforms.

You can’t tell the story of online casino platform growth without talking about Africa’s fintech revolution because they’re basically the same phenomenon happening simultaneously. Better payment infrastructure opened digital entertainment to millions who never touched credit cards or traditional banks.

Why Virtual Beats Traditional Every Time

Last month I sat down with operators in Nairobi and Harare. Every single one told me the same thing: virtual products solve real problems that physical venues simply can’t address. No closing times. Zero travel requirements. No waiting for weekly events.

Virtual sports cycle every 2 to 3 minutes. Racing simulations, football matches, basketball games—they run continuously. Someone in Lusaka engages with identical content as someone in Johannesburg, even at 2:47am on a random Tuesday.

Accessibility isn’t some minor feature. It’s literally the entire value proposition.

What The Numbers Show

Southern Africa saw virtual gaming revenue jump 127% between 2021 and 2024, confirmed across three separate regulatory reports. Kenya showed similar patterns. Nigeria too.

But official reports completely miss the social dimension that’s developed. People aren’t isolated users clicking alone. They’re actively sharing strategies, debating outcomes, forming communities centered on preferred virtual sports. I’ve joined WhatsApp groups with over 200 members who analyze virtual football patterns and discuss tactics.

Calling that simple gambling misses the point entirely.

The Regulatory Picture Gets Clearer

African governments struggled for years figuring out their approach to digital gaming. But I’ve tracked a clear trend toward establishing proper licensing frameworks instead of knee-jerk prohibition. Zimbabwe overhauled regulations in 2023. Tanzania implemented changes six months after. South Africa’s been continuously refining their system since 2019.

Solid regulations benefit everyone. Operators understand expectations. Players gain confidence they’re using legitimate platforms. Tax revenue gets collected appropriately.

Infrastructure Keeps Improving

I remember when 3G felt like living in the future. Now we’re installing 5G towers across major African cities while 4G coverage extends to 67% of the population. Virtual platforms don’t require bleeding-edge speeds, but reliability matters tremendously.

Payment processing evolved even faster than connectivity. M-Pesa, Airtel Money, MTN Mobile Money—they’ve transformed into the fundamental backbone of digital transactions continent-wide. When you can complete a deposit in 12 seconds using the system you buy airtime with, friction evaporates.

And when friction vanishes, adoption explodes.

NCBA, BasiGo Strike Deal to Finance 1,000 Electric Vehicles in Kenya

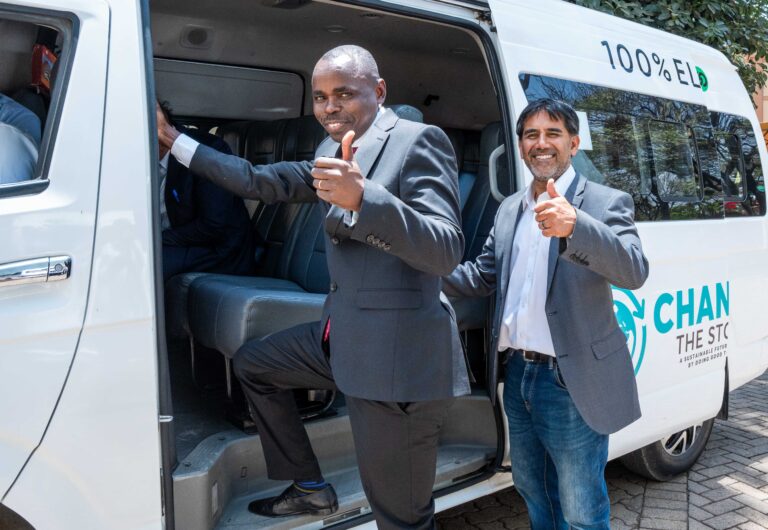
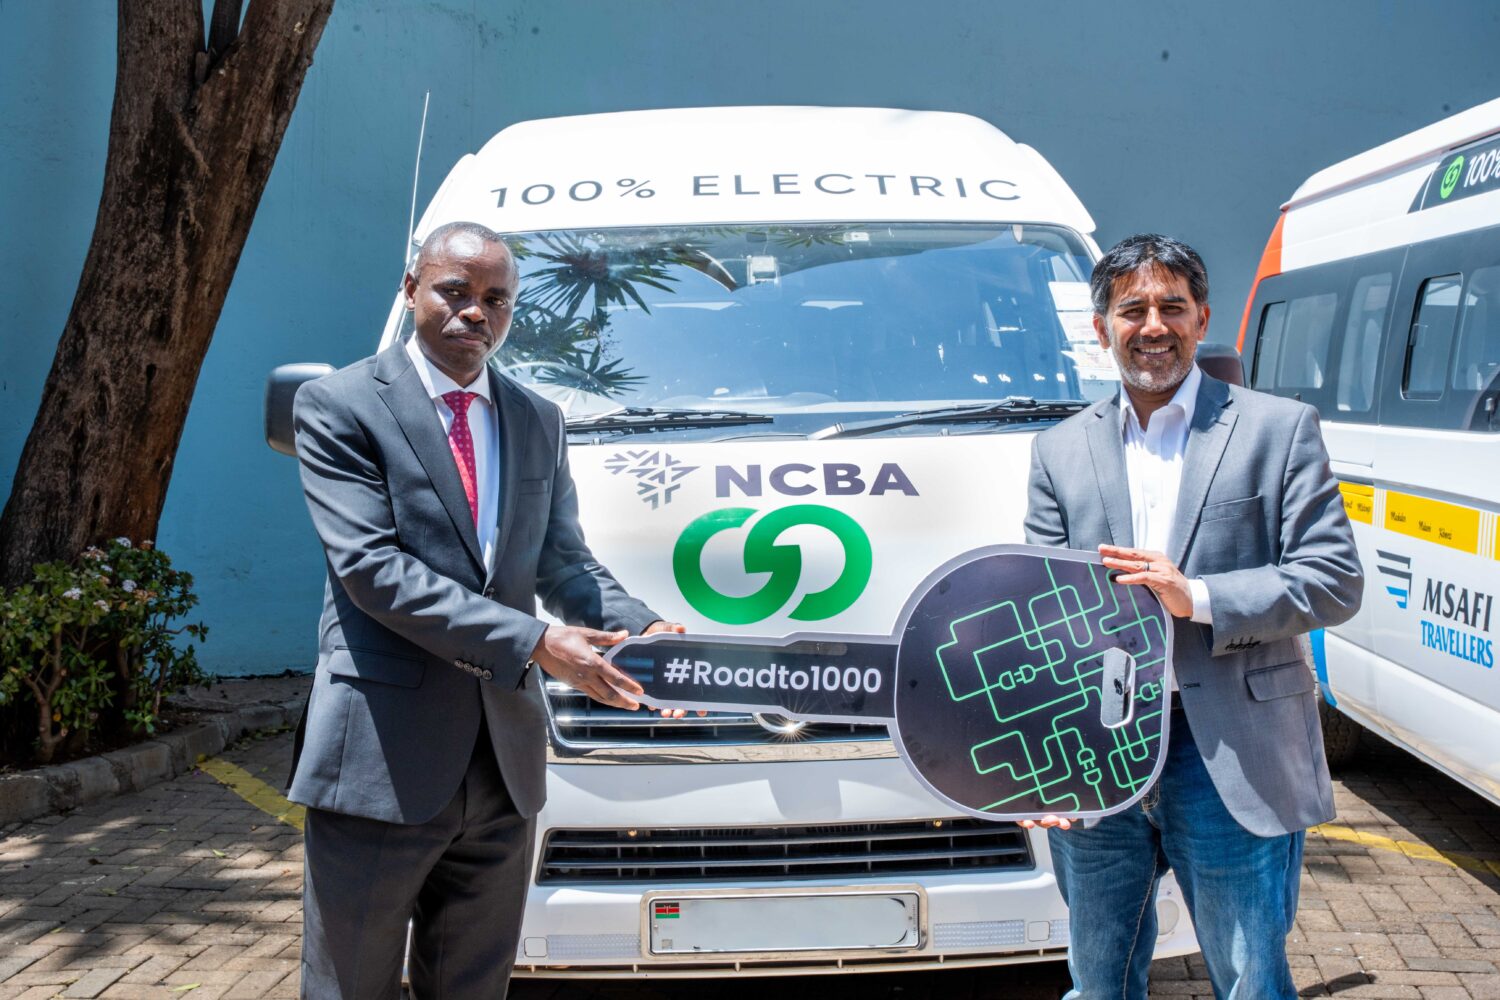
NCBA Group and electric mobility company BasiGo have partnered to finance 1,000 electric vehicles in Kenya, expanding access to leasing as public transport operators and businesses seek to overcome the high upfront cost of switching to electric fleets.

The partnership will enable PSV SACCOs, established transport operators and institutions including schools and hospitals to access financing for BasiGo electric vans through asset finance and leasing. BasiGo will use the financing to scale production and lease vehicles to operators and individuals.

The deal makes NCBA the first local investor to finance BasiGo and adds one of Kenya’s largest banks to the capital providers supporting the country’s growing electric mobility sector.

Existing PSV SACCOs and established PSV companies can access financing of up to 90% of an electric vehicle’s value over 60 months, while individual SACCO members can finance up to 80% over 48 months. Both options carry a discounted processing fee of 1.5%.

NCBA and BasiGo are also combining the bank’s financing with BasiGo’s Pay-As-You-Drive model, allowing operators to spread payments over time rather than absorb the full cost of an electric vehicle upfront.

“The most critical challenge in scaling electric vehicles in Africa is financing,” said Jit Bhattacharya, CEO and co-founder of BasiGo. “We are proud to partner with NCBA to address this problem head on for operators through affordable and creative financing solutions.”

For transport operators, the financing model could reduce the capital barrier to electric vehicles while offering potential savings on fuel and maintenance costs over the life of the vehicle.

“The transition to electric mobility is not simply about putting more electric vehicles on the road; it is about creating the financing and infrastructure needed to make them commercially viable at scale,” said Lennox Mugambi, Group Director of Asset Finance and Business Solutions at NCBA Group.

The partnership forms part of NCBA’s KES 2 billion e-mobility financing program. The bank said it has already invested more than KES 800 million in sustainable mobility assets, equivalent to about 40% of the facility.

The remaining KES 1.2 billion gives NCBA further capacity to finance electric mobility projects as demand for electric vehicles grows.

For BasiGo, the deal expands the financing options available to operators as the company seeks to move electric public transport beyond early adoption. The Nairobi-based company introduced electric buses into passenger operations in Kenya in 2022 and has built its business around providing vehicles, charging and maintenance services alongside its Pay-As-You-Drive financing model.

The partnership signals a broader shift in Kenya’s electric mobility market, with financing becoming as important as the vehicles themselves. By combining traditional bank lending with leasing and usage-based payments, NCBA and BasiGo are seeking to make electric fleets accessible to operators that may not have the capital to purchase them outright.

The success of the 1,000-vehicle target will ultimately depend on whether these financing structures can move electric mobility from early adopters into Kenya’s mainstream commercial transport market.

Samsung Gains as MEA Smartphone Market Shrinks 10% Amid Memory Crunch

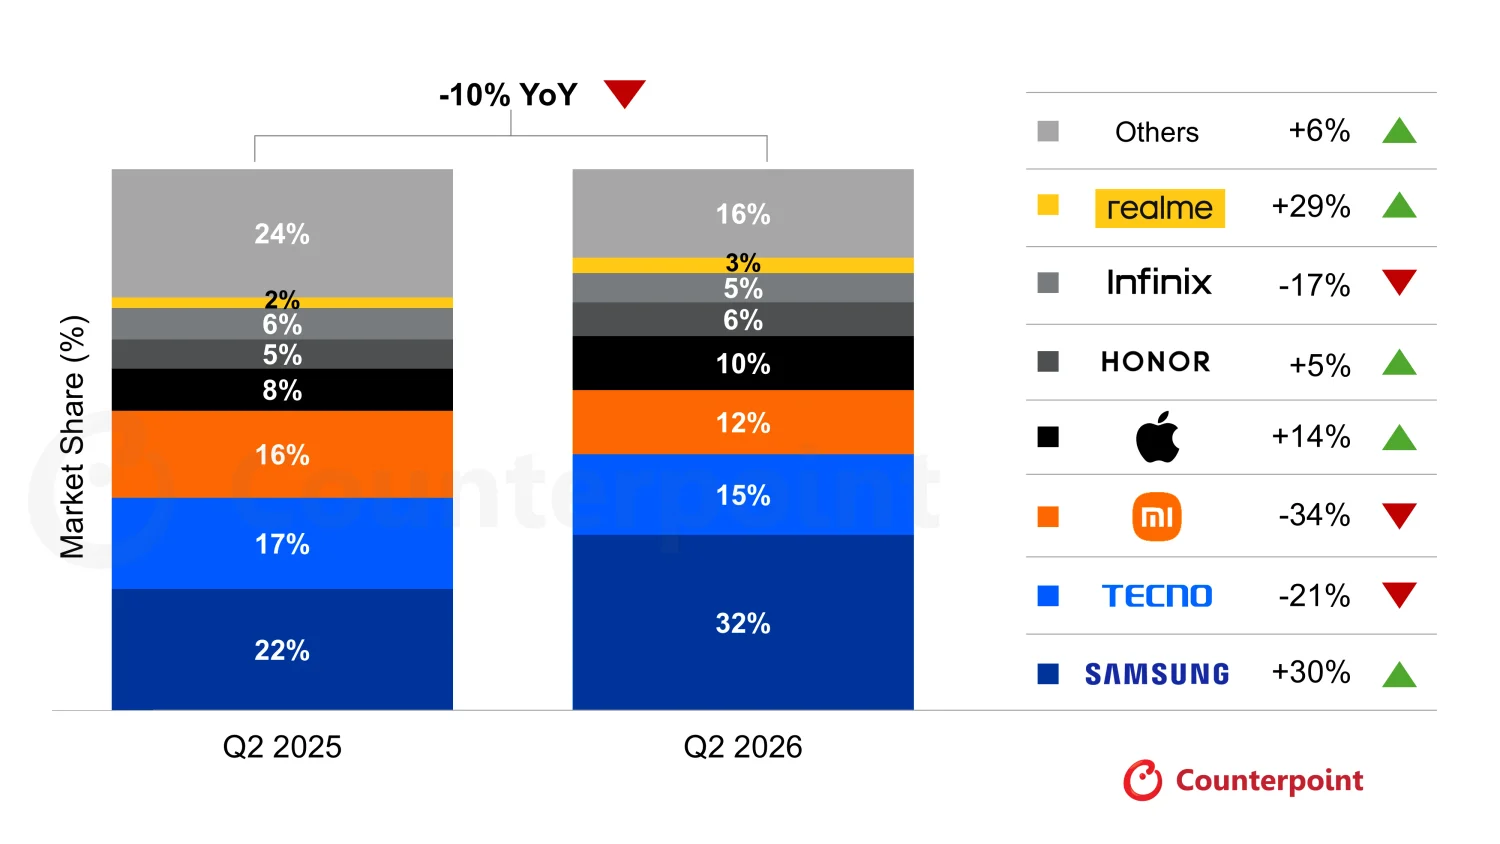
Samsung gained market share in the Middle East and Africa during the second quarter as a 10% decline in regional smartphone shipments and a memory-component shortage squeezed manufacturers concentrated in the entry-level segment.

Smartphone shipments across the Middle East and Africa fell 10% year over year in the second quarter of 2026, according to Counterpoint Research, with the market lacking a major sales-driving occasion during the period. The decline was uneven across manufacturers, with Samsung, realme and Apple recording significant growth even as several rivals lost share.

The result marks a shift in a market historically driven by affordable smartphones. With overall demand declining, Samsung’s gains largely came at the expense of competing manufacturers rather than from an expansion of the total market.

“Every unit Samsung gained came out of Infinix, TECNO and Xiaomi’s shares,” Counterpoint said, highlighting the scale of the competitive shift.

Samsung’s performance was supported by its Galaxy A07 and A17 models, as well as its recently launched Galaxy S26 flagship lineup. The combination gives the company exposure across both mass-market and premium price segments at a time when supply constraints are changing the economics of the smartphone industry.

Budget Phones Take the Biggest Hit

The sharpest pressure was concentrated at the bottom of the market.

Smartphone shipments priced below $250 declined 26% year over year in the second quarter, the steepest decline among all price bands, according to Counterpoint. The segment’s contraction weighed heavily on the overall MEA market because entry-level devices account for a significant share of smartphone volumes across the region.

The decline is closely linked to the ongoing memory-component shortage. Manufacturers facing constrained and more expensive memory supplies have been forced to prioritize higher-margin devices, reducing the availability of lower-priced models.

“The memory crisis hit the market hard, though unevenly,” said Ahmad Shehab, an analyst at Counterpoint Research.

“Transsion and Xiaomi were hit hardest,” Shehab said, because their sales volumes are concentrated in the entry-level segment, which is particularly exposed to the increase in memory costs.

That dynamic puts brands such as Infinix and TECNO, which are part of Transsion’s portfolio, under greater pressure in a market where affordability has traditionally been a major driver of smartphone adoption.

5G Moves in the Opposite Direction

While overall smartphone shipments declined, 5G shipments in MEA increased 8% year over year during the quarter.

That compares with global 5G smartphone shipment growth of only 1%, according to Counterpoint. The regional increase reflects both the relatively low 5G base in the second quarter of 2025 and the continued expansion of 5G networks and supporting policies across MEA.

Samsung and Apple were the primary contributors to the region’s 5G growth.

The divergence between total smartphone shipments and 5G shipments illustrates the changing composition of the market. Consumers are not necessarily rushing to buy more smartphones, but a greater share of the devices being sold are connected to newer networks and positioned higher up the technology and price curve.

For manufacturers, that creates an unusual form of premiumization.

The market is becoming more expensive not simply because consumers are demanding higher-end devices, but because component shortages are making it harder and less attractive for manufacturers to maintain aggressive volumes at the lowest price points.

Samsung Benefits From the Shift

Samsung is well positioned for that transition because its portfolio spans entry-level Galaxy A models through premium Galaxy S devices.

Its ability to serve multiple price points means the company can capture demand displaced by competitors while also benefiting from growth in higher-value smartphones.

The second-quarter results therefore give Samsung more than a temporary boost in market share. They could strengthen its competitive position if the supply constraints continue and consumers become accustomed to a market with fewer choices below $250.

Counterpoint said the gains made by Samsung, realme and Apple could make it more difficult for declining brands to recover their lost share because the market did not generate enough additional demand for every manufacturer to grow simultaneously.

That creates a potentially more durable competitive advantage for the companies that were able to maintain supply during the downturn.

Realme Turns Supply Into a Competitive Weapon

Realme’s performance provides another example of how manufacturers are responding to the constrained market.

The company expanded its presence in MEA even as its global smartphone shipments declined 23% year over year in the second quarter.

Rather than securing entirely new supply, realme allocated significantly more units to MEA, diverting supply from markets including India and China.

The strategy allowed the company to take advantage of demand that was left underserved as other manufacturers struggled with component constraints.

It also highlights a broader change in smartphone competition: in a supply-constrained market, market-share growth can increasingly depend on where manufacturers choose to send their available inventory.

For realme, MEA’s budget-oriented market became a strategic destination for that supply.

A Structural Shift for MEA’s Smartphone Market

The second-quarter results point to a smartphone market undergoing more than a temporary slowdown.

MEA’s traditional dependence on entry-level smartphone volumes is colliding with higher component costs and limited memory supply. The result is a market where the lowest price segment is shrinking rapidly while 5G and higher-priced devices gain ground.

Counterpoint expects the second quarter to be the weakest quarter of 2026, with the memory crisis adding to the impact of the shift in the Islamic calendar, which concentrated major first-half sales occasions in the first quarter.

For Samsung, the downturn has created an opportunity to widen its lead.

For Transsion and Xiaomi, the challenge is more difficult. Their exposure to entry-level volumes makes them particularly vulnerable when manufacturers have to ration scarce components toward more profitable devices.

The competitive landscape could therefore look different even after the memory shortage eases. Brands that lose distribution, shelf space and consumers during the downturn will have to spend to win them back, while Samsung can use its broader ecosystem and product portfolio to retain customers who move into higher-priced devices.

The central question for MEA’s smartphone industry is no longer simply how many phones consumers will buy. It is increasingly which manufacturers can secure enough supply, at which price points, and in which markets. For the second quarter, Samsung had the stronger answer.

HassConsult Bets on $548 Billion Wellness Property Trend After Enaki Hits 92% Occupancy

0

HassConsult is betting that wellness and community-driven living can become a bigger source of value in Kenya’s residential property market, as a global wellness real estate sector worth $876 billion increasingly reshapes how developers design, market and operate homes.

The Nairobi-based developer is expanding its Enaki model with Elevate by Hass, a resident experience platform built around fitness, wellness, dining, entertainment, work and community programming. The move comes as the global wellness real estate market, one of the fastest-growing segments of the broader wellness economy, is projected to reach $1.8 trillion by 2030.

For HassConsult, the opportunity is increasingly being measured in property performance.

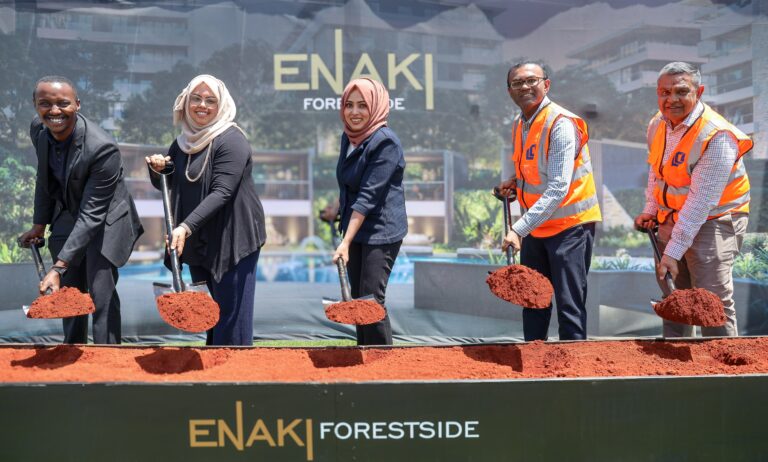
Enaki’s first phase of 440 apartments is 92% occupied, with waitlists for several fully occupied unit types, according to the developer. Its next phase, Enaki Forestside, has sold 50% of its homes within four months of launch.

Those figures give HassConsult an early commercial case for a strategy that treats resident experience as more than an amenity.

“The traditional measures of residential value, location, size, specification, are no longer the full picture. When residents genuinely belong to where they live, it shows up commercially,” said Farhana Hassanali, co-CEO and development director at HassConsult.

The company’s approach reflects a broader shift in wellness real estate. The Global Wellness Institute’s latest research shows the sector grew from $151 billion in 2017 to $876 billion in 2025 and is forecast to more than double to $1.8 trillion by 2030. The sector has been growing substantially faster than overall construction, making wellness-focused development an increasingly important part of the global property industry.

The shift is also changing what developers mean by wellness.

Rather than focusing only on gyms, swimming pools or landscaped gardens, newer wellness-oriented developments are incorporating physical health, mental wellbeing, social connection, access to nature and programming into the way communities operate.

HassConsult is attempting to bring that model to Nairobi through Enaki, which it describes as a residential resort built around green space and community life. The development spans 22 acres and includes a six-acre botanical garden, while the Forestside phase is centered around a 23,000-square-foot private forest.

Elevate by Hass is intended to turn those physical assets into an ongoing resident experience.

The platform brings together fitness and gastronomy, wellness and work, children’s activities, resident events and entertainment. HassConsult says the objective is to create reasons for residents to use shared spaces regularly rather than treating amenities as facilities that sit largely idle between property viewings and occasional use.

At Enaki Town, a purpose-built movement studio provides space for fitness and wellness programming, while Artcaffé operates a marketplace designed as a social hub. The venue has hosted high teas, children’s baking competitions and cultural festivals.

That operating model is significant because HassConsult is seeking to stay involved in the development beyond the traditional property-sales cycle.

The company says its model brings together market research, development, design, pricing, marketing, sales, letting and property management. Elevate adds another layer: actively managing the experience residents have after they move in.

That could give developers a new way to differentiate projects in a market where residential developments increasingly compete on similar features such as security, parking, gyms, pools, gardens and proximity to commercial centers.

The question for the industry is whether the additional investment in programming and community infrastructure can translate into measurable commercial returns through faster sales, higher occupancy, stronger rental demand and potentially greater long-term property values.

Enaki’s early numbers offer some evidence of demand, although they do not by themselves establish that resident programming caused the development’s occupancy or sales performance.

The 92% occupancy rate across Enaki’s 440 completed apartments means the project has already absorbed much of its available residential inventory. Forestside’s 50% sales rate in its first four months provides a second indicator of buyer interest as HassConsult expands the concept.

The company is now scaling the model beyond the original Enaki experience.

“The design brief of the future has to include human connection as an outcome. What draws people out of their homes and keeps them coming back cannot be left to chance. It must be designed, programmed and sustained,” said Sakina Hassanali, co-CEO and creative director at HassConsult.

For Kenya’s property industry, the bigger opportunity may be the economics of what happens after a home is sold.

As developers increasingly compete on lifestyle, the value proposition may shift from simply selling square meters to creating communities that residents want to remain part of. That would give developers a commercial incentive to operate and program residential developments long after construction is complete.

HassConsult’s expansion of Elevate suggests it sees that shift as more than a marketing trend.

With a global wellness real estate market already at $876 billion and projected to reach $1.8 trillion by 2030, the company is positioning its Nairobi developments to capture a small but potentially valuable part of a rapidly expanding property category.

Google Offers African Students One Year of Free Google AI Plus

0

Google is expanding access to its AI-powered learning tools across Africa, offering eligible higher education students in 27 countries one year of Google AI Plus at no cost.

The offer gives university and college students 12 months of access to Google AI Plus, including Gemini Omni, higher usage limits in Gemini and 400 GB of cloud storage across Google Drive, Gmail and Google Photos.

Students can use Gemini and Google’s AI-powered learning tools to support research, coursework, revision and other academic tasks. The offer is available in markets including Kenya, Nigeria and South Africa, alongside 24 other African countries, subject to eligibility requirements.

Students can claim the offer through Google’s student program.

The expansion comes as higher education students across Africa navigate different academic calendars, with some preparing for a new academic year while others are already midway through their studies. Google said the initiative is intended to give students greater access to technology that can support learning throughout their academic journey.

The new offer follows Google’s Gemini Student promotion launched last year. Students who previously claimed the offer can renew their access for another 12 months, subject to re-verification.

“This Google AI Plus student offer reflects our commitment to making advanced AI tools more accessible to Africa’s next generation of learners and innovators,” said Alex Okosi, Managing Director for Google in Africa. “Higher education requires students to research deeply, solve complex problems and continuously build new skills.”

“As AI becomes an increasingly important tool for learning and work, we want to enable more students across Africa to access the resources they need to explore ideas, build knowledge and prepare for the future,” Okosi said.

AI Tools for Students

Google said its AI learning tools are designed to help students work through complex topics, explore ideas and develop a deeper understanding of their subjects rather than simply provide answers.

The Google AI Plus student experience includes a dedicated Student Hub within Gemini, where students can organize their studies, create practice quizzes and explore different learning approaches.

Students can also use Study Notebooks to upload course materials such as lecture notes, syllabi and reading materials. Gemini can use those materials to break down topics, identify potential knowledge gaps and create tailored lessons and quizzes.

Other tools include interactive visualizations that can generate 3D models, simulations, tables and other visual elements to help students understand complex concepts across different subjects.

Students can also use Gemini Live for conversational discussions about research and launch Deep Research reports that conduct multi-step research in the background.

Google’s broader AI learning experiences allow students to explore concepts, practice what they have learned and work through visual problems and diagrams.

Availability Across 27 African Countries

Eligible higher education students can verify their student status through SheerID and claim or renew the 12-month Google AI Plus offer through Google’s student program.

The offer is available to eligible students in Angola, Benin, Botswana, Burkina Faso, Cabo Verde, Cameroon, Côte d’Ivoire, Gabon, Ghana, Guinea-Bissau, Kenya, Mali, Mauritius, Mozambique, Namibia, Niger, Nigeria, Rwanda, Senegal, Seychelles, Sierra Leone, South Africa, Tanzania, Togo, Uganda, Zambia and Zimbabwe.

Students can check eligibility and access Google’s student AI program through the company’s dedicated student portal.

Google Cloud Unveils Gemini AI Solutions for Finance, Legal Industries

0

Google Cloud is expanding its enterprise artificial intelligence offering with two new industry-specific products designed to automate complex workflows in financial services and legal work.

The company announced Gemini Enterprise for Financial Services and Gemini Enterprise for Legal, the first in a planned series of specialized industry solutions built on its Gemini Enterprise platform. The products combine AI agents, workflow tools, data connectors and model optimizations tailored to specific industries, allowing organizations to deploy AI for tasks that often require extensive research, analysis and review.

For financial institutions, Gemini Enterprise for Financial Services includes a Google-managed Financial Research agent, more than 50 specialized skills and 13 data connectors to providers including FactSet, LSEG, Moody’s and MSCI. It also supports third-party agents from companies including Dun & Bradstreet and S&P.

The system is designed to connect market data, regulatory filings and internal company systems to automate multistep research while maintaining data lineage, Google said. Potential applications include know-your-customer research and analysis, dealmaking and pitching, risk and trading, adviser insights and identifying credit opportunities.

Deutsche Bank is a design partner for the financial-services product, while CME Group is among its early users.

Gemini Enterprise for Legal is aimed at workflows including contract review, due diligence, regulatory monitoring, legal research and privacy requests. The platform connects with legal technology and information systems including iManage, NetDocuments, RelativityOne, Thomson Reuters, Harvey and CourtListener.

Google said the legal solution grounds research outputs in primary legal authority rather than relying only on information contained in an AI model’s training data. The company also said customers’ data, playbooks, client files and negotiated positions remain within their private environment.

Law firms including Cleary, Freshfields, Weil and Williams & Connolly are among the launch customers.

The products represent Google’s effort to move enterprise AI beyond general-purpose assistants and into specialized workflows where companies require tighter controls over data and how AI-generated work is produced and reviewed. That distinction is particularly important in financial services and legal work, where sensitive client information, regulatory requirements and audit trails can limit how organizations use general-purpose AI tools.

Google Cloud is positioning Gemini Enterprise as the underlying platform for these deployments, with the new industry offerings adding domain-specific agents, skills and connections to external and internal data sources.

The launch comes as cloud providers and enterprise software companies increasingly target AI applications that can perform multistep tasks rather than simply generate text or answer questions.

By packaging industry-specific capabilities into Gemini Enterprise, Google is seeking to give financial institutions and law firms a way to deploy AI across established workflows while maintaining governance and control over sensitive information.

Ventures Platform Closes $84 Million Second Africa Venture Fund

0

African early-stage investor Ventures Platform has closed its second institutional fund at $84 million, surpassing its $75 million target as new investors including the European Bank for Reconstruction and Development, Norfund and Alphatron joined its limited partner base.

The close comes three years after the firm raised its first institutional fund and at a time when venture investment in Africa has faced tighter funding conditions and greater scrutiny from global investors.

Ventures Platform said the fund, known as VP Pan-African Fund II, will invest from the pre-seed stage through Series A, with additional capital available to support portfolio companies in later funding rounds.

The new investors include EBRD, Norway’s development finance institution Norfund, investment firm Alphatron and Ashesi University Foundation. A group of family offices also participated in the final close.

They join existing investors including Nigeria’s Investment in Digital and Creative Enterprises program, the International Finance Corp., Standard Bank of South Africa, British International Investment, Proparco, the Micro, Small & Medium Enterprises Development Agency, AfricaGrow and Alder Tree Investment.

CHAZI

The fund’s $84 million close is notable as African startups have faced a more difficult fundraising environment following the surge in venture capital activity earlier in the decade. Investors have increasingly focused on companies with clearer paths to revenue, stronger governance and more disciplined capital use.

Ventures Platform, which has operated for more than a decade, has invested in African technology companies including Moniepoint, PiggyVest, OmniRetail, Raenest, _able and Seamless Technologies, formerly SeamlessHR.

Kola Aina, the firm’s founding and managing partner, said the fund would focus on entrepreneurs building companies with stronger technical capabilities, governance and knowledge of the markets they serve.

“This fund is ultimately not about the capital we’ve raised, but about the entrepreneurs we’re privileged to be able to back,” Aina said in a statement.

The firm’s new institutional backing comes as development finance institutions continue to play a significant role in African venture capital, helping channel institutional capital into an asset class that remains relatively small compared with other emerging markets.

Dirk Werner, managing director of equity at EBRD, said venture capital in Africa remains underdeveloped relative to the continent’s entrepreneurial activity and that the investment would help strengthen access to growth capital.

Alphatron Investment Manager Jerry Jansen said the firm sees potential in Africa’s technology sector and expects to work with Ventures Platform to support companies as they expand.

Ventures Platform said the new fund will target businesses addressing challenges and opportunities across sectors, with technology used to expand economic access and inclusion.

The firm did not disclose the amount raised in the fund’s initial close or the individual commitments from its limited partners.

The $84 million fund gives Ventures Platform additional capital to deploy as African startups contend with a funding market that has become more selective, while investors remain interested in businesses capable of serving large and underpenetrated markets across the continent.

MTN Plans 150MW AI Data Center Buildout as Telecom Giant Expands Beyond Connectivity

0

MTN Group is planning to develop about 150 megawatts of AI-ready data-center capacity in South Africa and Nigeria, expanding its push into digital infrastructure as demand for computing power grows across Africa.

The telecommunications group is pursuing the project through Africa Data Hub Holding Ltd., a new venture established with a UAE-backed data-center investment platform. MTN will hold a minority stake in the venture, Chief Executive Officer Ralph Mupita said at a media roundtable this week.

The first phase will target about 150MW, with additional capacity possible depending on demand. MTN has not disclosed the investment size or the identity of its UAE-backed partner.

The venture was disclosed in MTN’s interim results for the six months ended June 30, when the company said it had entered into a strategic partnership to expand its data-center and related infrastructure business in Africa.

The move puts data centers alongside connectivity and fintech as areas of growth under MTN’s Ambition 2030 strategy. AI applications require large amounts of computing capacity, as well as reliable power, cooling and high-capacity connectivity, creating an opportunity for telecommunications operators with established infrastructure to expand into adjacent markets.

South Africa and Nigeria are the initial focus markets. MTN already has data-center operations in both countries, giving the group existing infrastructure and enterprise relationships from which to expand.

The company is also looking at ways to finance the expansion without carrying the entire cost itself. By retaining a minority position in Africa Data Hub, MTN can combine its network and customer base with external capital and data-center expertise. The company has not provided details on how much each partner will invest.

The data-center plans come as MTN reports stronger financial performance across its African operations. Group service revenue increased 17.5% to R115.3 billion in the first half, while adjusted headline earnings per share rose 21.3% to 793 cents. Core earnings increased 24.4%, according to the company’s interim results.

Fintech is another part of the group’s expansion beyond traditional telecommunications. Transaction value in MTN’s fintech business increased 33.8% to $330.5 billion in the first half, as the company expanded its payments and other digital financial services.

MTN is now considering going further into banking. Mupita said the company is evaluating banking licenses in selected African markets as it looks to expand lending through its Mobile Money business. MTN currently works with banks and other financial institutions to fund loans, but a banking license could eventually allow it to take deposits and lend from its own balance sheet.

The company is not planning to seek banking licenses across all of its markets. Mupita said MTN would focus on countries where it has large customer bases and significant activity in mobile wallets. Any move toward balance-sheet lending would also be gradual because it would expose MTN to greater credit and regulatory risks.

MTN is also returning capital to shareholders after the stronger first-half performance. The group approved a R6 billion ($375 million) share repurchase program, which forms part of its capital-allocation framework.

The company is simultaneously pursuing greater ownership of its tower infrastructure through its proposed acquisition of the remaining shares in IHS Towers. MTN agreed in February to acquire the shares it does not already own, with the transaction subject to regulatory approvals.

Nigeria’s competition regulator has approved the deal conditionally, including a requirement for MTN to sell down 30% of the Nigerian business to local investors. MTN said regulatory processes for the transaction remain ongoing.

The IHS transaction would give MTN greater control of infrastructure supporting its networks, while the Africa Data Hub venture would give the group a larger role in the infrastructure used to process digital workloads.

Together, the moves show how MTN is broadening its business beyond mobile connectivity. The group is investing in infrastructure for data and AI, expanding financial services and increasing its ownership of telecommunications infrastructure while using partnerships and capital-market transactions to manage the cost of that expansion.

For now, the 150MW data-center target is the clearest indication of the scale of MTN’s ambitions in AI infrastructure. The company has yet to disclose the specific facilities, investment commitments or timetable for the first phase, leaving the size and pace of the rollout dependent on power availability, customer demand and the completion of project development in South Africa and Nigeria.

Why APIs Are Becoming Essential to Africa’s Digital Platforms

0

If you examine digital businesses, you’ll find that many of these aren’t built entirely from scratch. A fintech startup can connect to an existing payment network, an e-commerce company can tap into an external logistics service, and a gaming platform is able to integrate products created by numerous developers. 

Application programming interfaces, better known as APIs, are what make many of these connections possible. They allow separate software systems to exchange information, helping companies add services without developing every component internally. For African startups operating with limited resources, this can make launching and expanding a product much easier.

APIs Help Startups Build Faster

More goes into developing a digital platform than many realise. They need payment processing, identity verification, communication, and a host of other functions. Developing every system internally would need a considerable input of time and money.

APIs are there to provide an alternative. A company is given the freedom to integrate specialist services from external providers while being able to concentrate its resources on its main product. 

Payments provide a good example. Rather than creating a financial network, an e-commerce business can connect with existing payment providers. Information passes between the company’s platform and the financial service whenever customers make transactions.

Kenya Shows The Potential

Kenya provides a strong example of API-based financial infrastructure. Safaricom’s Daraja platform gives developers access to M-PESA APIs, allowing businesses to integrate mobile payments into websites and applications.

In April 2026, Daraja supported more than 66,000 integrations. This goes to show how a single established financial service can become the infrastructure used by thousands of other digital products.

Similar models are able to support companies expanding across Africa. Instead of asking customers to adopt unfamiliar payment methods, businesses can connect with services already widely used within individual markets.

Gaming Uses The Same Model

Another example of API-driven development can be seen when looking at online gaming. A platform can offer games that come from hundreds of studios while offering payment methods and other tech that come from separate companies.

An operator offering crash games online, for example, doesn’t necessarily develop those games itself. A specialist studio can provide the software, while an integration makes the product accessible through the operator’s existing platform and customer accounts.

This allows gaming companies to expand their products without becoming software studios themselves. The principle is similar to an online retailer integrating an established payment provider instead of developing its own banking infrastructure.

This means that gaming companies can expand their products at speed without the need to become software studios in their own right. This is similar to how an online retailer uses established payment providers rather than developing a standalone banking infrastructure. 

APIs Can Make Expansion Easier

When technology companies enter another country, there tends to be a whole host of new challenges. The likes of currencies, ID requirements, and customer preferences can all be different as a border is crossed.

A modular platform can make adaptation easier. Instead of rebuilding the entire service, developers may be able to add or replace individual integrations according to the requirements of a particular market.

Payment infrastructure is especially important. A financial service widely used in Kenya won’t have the same position in Nigeria, Ghana or South Africa. Connecting with established local providers can consequently be important for companies pursuing regional expansion.

Familiar Products Have Changed Too

Developments linked to API aren’t just about new tech products. It has also had an impact on how established forms of digital entertainment are distributed.

Someone choosing to play slots online can potentially access titles from numerous independent studios through one gaming platform. The operator doesn’t have to develop every title because external providers can connect their games to the wider service.

Similar models exist throughout technology. Streaming platforms distribute content from different studios, marketplaces connect thousands of independent sellers with customers, and app stores provide access to software created by outside developers.

External Services Create New Risks

Businesses need to think about what happens if a supplier goes ahead and changes its prices, tech requirements, or availability. A service that helps a startup to get up and running quickly can soon become a dependency as the company grows.

Using APIs doesn’t remove the need for strong technical management. Monitoring services and planning for failures become increasingly important as platforms add more external connections.

Platforms Are Becoming Collections Of Services

APIs have changed what companies need to build themselves. A startup can combine payments, communications, identity tools and specialist content from different providers while presenting everything through a single product.

This can reduce development time and give smaller companies access to infrastructure that would be expensive to create independently. Africa’s fintech industry provides a particularly clear example, with mobile money systems creating foundations on which other digital businesses can build.

HassConsult Bets on Connected Communities to Redefine Kenya’s Residential Experience

0

Kenya’s growing dependence on digital platforms is changing how people work, communicate, shop and entertain themselves, but property developer HassConsult is betting that the next evolution of the connected lifestyle may require people to step away from their screens and reconnect in the physical world.

The developer has introduced Elevate by Hass, a resident experience platform designed to bring together fitness, wellness, entertainment, work, dining and community activities within its residential developments, with Enaki Residential Resort serving as its first major pilot.

The move comes as technology continues to reshape everyday life in Kenya. While social media and digital services have made it easier to remain constantly connected online, they have also contributed to more fragmented physical communities. HassConsult is responding by bringing a technology and platform mindset to residential living, where the value of a home extends beyond its walls.

From Smart Homes to Connected Communities

The opportunity comes as the global wellness real estate market continues to expand. The Global Wellness Institute estimates the sector is worth about $548 billion globally and projects it will surpass $1 trillion by 2029. The sector is increasingly moving beyond buildings and amenities towards environments designed to support physical, mental and social wellbeing.

For Kenya, the shift is particularly relevant. HassConsult, citing the latest industry research, says Kenyans spend more time on social media than any other nation, with 20 percent spending more than six hours a day on social platforms. The same research indicates that 26 percent of Kenyan employees experience loneliness frequently.

This creates a technology paradox: as digital tools connect people virtually, residential developers are increasingly looking at how physical spaces can restore real-world interaction.

At Enaki Town, this approach is already taking shape through purpose-built spaces and curated programming. A dedicated movement studio provides permanent fitness and wellness programming delivered by specialist operator Yves Preissler, while Artcaffe operates a marketplace designed as a social hub, hosting activities ranging from high teas and children’s baking competitions to cultural festivals.

These spaces are designed to do more than provide amenities. They give residents reasons to leave their apartments, interact with one another and build connections around shared interests turning everyday residential facilities into an active community experience.

Sakina Hassanali, Co-Ceo and Creative Director, HassConsult

At Enaki, Elevate by Hass operates as an ongoing resident experience rather than simply a collection of amenities. Residents have access to fitness and wellness programmes, children’s activities, entertainment, workspaces, dining and community events. Some facilities incorporate technology such as video-conferencing, while fitness programmes include community challenges and wellness sessions.

The model effectively treats a residential development like a service platform, one that needs continuous programming and engagement after residents move in.

The Urge for Connected Living

Farhana Hassanali, Co-CEO and Development Director at HassConsult, says traditional measures of residential value such as location, size and specification are no longer the full picture.“When residents genuinely belong to where they live, it shows up commercially,” she says.

The model potentially creates a growing opportunity for Kenya’s proptech sector. As residential developments become more service-oriented, developers will need digital systems for resident communication, bookings, events, payments, access to shared facilities and potentially AI-powered property and wellness services.

The future smart home, therefore, may not simply be one where appliances, security systems and lighting are connected but one where the entire community is connected.

Sakina Hassanali, Co-CEO and Creative Director at HassConsult, argues that human connection should increasingly become part of the development brief.“The design brief of the future has to include human connection as an outcome.”

For Kenya’s property and technology sectors, that could mark a shift from building smarter homes to creating smarter, more connected communities.

NCBA, HEVA Launch KES 20 Million Collateral-Free Startup Financing for Creative Sector

NCBA Group and HEVA Fund have launched a KES 20 million ($154,000) financing facility for startups and small businesses in Kenya’s creative economy, offering capital without collateral at a 9% interest rate.

The Start-Up Incubator facility is the first financing product introduced under the organizations’ strategic partnership. It targets individuals and registered small and medium-sized enterprises operating across the creative industry value chain.

Borrowers can access short-term financing with repayment periods of up to six months. The facility also includes insurance, with the partners positioning the product as a way for creative entrepreneurs to fund immediate business needs, pursue new opportunities and strengthen their operations without providing security.

“Through this product, we are empowering the ambitions of many creatives and demonstrating the power of our Ubuntu strategy in unlocking opportunity, building resilience and creating lasting impact for creative entrepreneurs, their families and the wider economy,” NCBA Group Managing Director John Gachora said.

The facility is being deployed through a shared-risk financing model, with NCBA and HEVA planning additional products aimed at addressing different cash-flow needs among creative businesses.

The planned products include event financing, invoice discounting, LPO financing and working-capital financing.

Wakiuru Njuguna, managing partner at HEVA, said the partnership is intended to bring financing designed specifically for creative businesses into mainstream banking.

“We have spent the last 12 years at HEVA proving that creative businesses are commercially viable and investable,” Njuguna said. “This partnership with NCBA marks an important step in bringing that vision into mainstream commercial banking, combining HEVA’s sector expertise with NCBA’s scale to expand access to capital and accelerate the growth of Kenya’s creative economy.”

HEVA said it has mobilized more than $45 million since 2013 and developed financing instruments for businesses operating in fashion, digital content, music, gaming, performing and visual arts, film and live events.

The partnership combines NCBA’s banking infrastructure and regional reach with HEVA’s experience financing creative enterprises, as financial institutions increasingly look to develop products for businesses whose revenue cycles and assets differ from traditional sectors.

NCBA operates in Kenya, Uganda, Tanzania, Rwanda and Côte d’Ivoire and provides banking services to corporate, institutional, SME and consumer customers.

The launch gives startups and other creative businesses access to a dedicated pool of capital while laying the groundwork for a broader range of financing products tied to their operating and growth needs.

Swvl Raises $13 Million in Strategic Investment Led by Sawiris-Backed Coefficient

0

Swvl Holdings Corp. has agreed to raise $13 million from investors led by Coefficient LP, a U.S. investment firm backed by Egypt’s Sawiris family, as the mobility technology company expands into the U.S. market.

Coefficient will invest $10 million in the private placement, while an existing Swvl shareholder will contribute another $3 million. The transaction is expected to close on Aug. 27, subject to customary closing conditions, according to a company statement on Tuesday.

Swvl will issue 8,990,317 Class A shares at $1.446 each. Following the investment, Coefficient is expected to become Swvl’s largest institutional shareholder.

Abdalla Ali, Coefficient’s founder and managing partner, will join Swvl’s board as part of the transaction.

The financing comes as Swvl seeks to expand beyond its core markets in the Middle East and Africa and build its business in the United States. The company said it has recently started U.S. operations and plans to use part of the proceeds to accelerate that expansion.

Swvl also plans to use the funds to launch a lending product for transportation operators and partners in its network and strengthen its balance sheet as it pursues multi-year contracts with enterprises and governments.

The Cairo-founded company reported revenue of $8.2 million in the first quarter of 2026, up 68% from a year earlier. Revenue from the Gulf Cooperation Council rose 111%, while recurring revenue accounted for 88% of total revenue.

Swvl reported net dollar retention of 114% during the quarter, while revenue pegged to the U.S. dollar increased to 44% of total revenue. Operating expenses fell to 23% of revenue, according to the company.

Swvl said the results put it closer to operating breakeven as it shifts its focus toward enterprise and government customers.

“We believe that our results demonstrate that Swvl’s enterprise-first model can scale profitably,” Chief Executive Officer Mostafa Kandil said in the statement.

The latest financing gives Swvl additional capital as it enters the U.S. market, one of the company’s most significant expansion efforts since its public listing.

Swvl, which trades on Nasdaq under the ticker SWVL, provides technology for managing transportation networks for companies, governments, schools and healthcare providers. Its operations span Egypt, Saudi Arabia, the United Arab Emirates, Kuwait, Qatar, the United Kingdom and the United States.

Coefficient is based in Houston and invests in founder-led companies, with a focus that includes decarbonization and the energy transition. The firm is backed by the Sawiris family, one of Egypt’s most prominent business families.

The shares are being sold through a private placement under exemptions from registration requirements of the U.S. Securities Act. Swvl has agreed to file a resale registration statement covering the securities issued to Coefficient. The transaction remains subject to customary closing conditions.

Nigeria’s ThriveAgric Raises $3.93 Million for Expansion

0

Nigerian agritech company ThriveAgric has raised 5.3 billion naira ($3.93 million) through its first commercial paper issuance, the company said on Tuesday.

The Series 1 issuance was oversubscribed after investors placed orders above ThriveAgric’s initial target of 5 billion Naira and is the first issuance under ThriveAgric’s 50 billion-naira commercial paper program approved by Nigeria’s Securities and Exchange Commission.

The company plans to use the proceeds to finance the purchase of agricultural produce from smallholder farmers and supply it to established buyers, Chief Executive Officer Uka Eje said at a signing ceremony and media briefing in Lagos.

“The initial problem we’ve always faced has been accessing the right capital,” Eje said.

ThriveAgric finances farmers, purchases their produce after harvest and sells the commodities to processors and fast-moving consumer goods companies. Eje said the commercial paper would primarily finance the commodity-trading part of the business.

“This is why it’s not equity; it is debt to expand our business in Nigeria,” he said.

ThriveAgric expects to make additional commercial paper issuances over the next 12 months under the 50 billion-naira program.

The company previously raised $56.4 million in debt financing in 2022 from local commercial banks and institutional investors. The financing was intended to support its farmer network and expansion into markets including Ghana, Zambia and Kenya.

ThriveAgric currently operates in Nigeria, Ghana, Kenya, Uganda and Rwanda, with Nigeria accounting for about 90% of its business, Eje said.

The latest funding will be focused on its Nigerian operations, including the purchase and aggregation of agricultural commodities.

Founded in 2017 by Eje and Ayodeji Arikawe, ThriveAgric provides financing and market access to smallholder farmers.

The company said it currently serves more than 1.3 million smallholder farmers across 26 Nigerian states and works with about 5,000 field agents.

ThriveAgric’s Agricultural Operating System, known as AOS, is used to collect and manage information on farmers and their agricultural activities, including onboarding, farm data collection, distribution of inputs, field monitoring and inventory management.

The company has also said it plans to use agricultural and transaction data to help farmers gain access to financial services.

ThriveAgric’s agricultural production activities can require nine to 12 months, while the purchase and sale of harvested commodities takes place over a shorter period, Eje said. The commercial paper will therefore be used primarily for the company’s shorter-term trading activities.

Anchoria Advisory Services acted as the lead issuing house for the transaction. BAS Capital, Mulberry, FCMB Capital Markets and FCSL were also involved in the issuance.

The 5.3 billion-naira transaction is the first issuance under the company’s 50 billion-naira program, leaving ThriveAgric with capacity to raise additional funds through the program. The company did not disclose the individual investors participating in the issuance.

Moniepoint Shuts Down MonieWorld, Its UK Remittance Business

Moniepoint Inc. is reportedly shutting down MonieWorld, its UK remittance business, less than 18 months after launching the service, as the Nigerian fintech redirects resources toward its operations in Africa.

The company said the decision followed a review of its businesses and long-term priorities. Moniepoint will redeploy technology and staff from MonieWorld to other parts of the group.

MonieWorld launched in April 2025, allowing Nigerians in the UK to send money to Nigerian bank accounts using the service, UK bank cards, Apple Pay and Google Pay. It was Moniepoint’s first major push into a consumer financial-services market outside Africa.

The service recorded some early growth. Monthly transaction volumes among UK customers rose 70%, Moniepoint said. The company didn’t disclose the value of transactions processed, revenue from the business or the number of customers it acquired.

The decision brings a relatively short-lived UK expansion to an end and comes after Moniepoint invested in building the infrastructure needed to operate in the country’s regulated financial-services market.

UK Expansion

Moniepoint GB was incorporated in February 2024, ahead of the launch of MonieWorld.

The company spent about £1.2 million on administrative expenses, technology infrastructure and compliance staffing for its UK operations, according to figures disclosed by Moniepoint.

It also committed a $2.5 million equity deposit toward the acquisition of Bancom Europe Ltd., an electronic-money institution authorized by the UK Financial Conduct Authority.

The acquisition was intended to give Moniepoint additional regulatory infrastructure for its UK operations and potentially support expansion into other European markets.

Moniepoint didn’t disclose its total investment in MonieWorld or say whether the business had reached profitability.

The company said the UK operation nevertheless helped it develop and test infrastructure for cross-border payments. That technology and experience will now be used in its African businesses.

“Having validated its cross-border infrastructure and delivered value to thousands of diaspora users,” Moniepoint said it would redirect its technical, capital and operational resources toward its primary African markets.

Focus on Nigeria and Kenya

Moniepoint has continued to expand in Africa while building out its UK operation.

Nigeria remains its biggest market, where the company provides banking and payments services to businesses and merchants. Its Moniepoint Microfinance Bank serves businesses through its payments and banking products, while Monnify provides payment infrastructure for businesses and online merchants.

The company has also expanded beyond payments. It acquired restaurant technology company Orda as it builds services around the day-to-day operations of small and medium-sized businesses.

Kenya has become another important market.

Moniepoint acquired a 78% stake in Sumac Microfinance Bank, giving it a regulated financial-services platform in the country. It later appointed Rose Muturi as chief executive of its Kenyan operations.

The acquisition gives Moniepoint a base from which to expand its banking and payments products in a market where small and medium-sized businesses are already significant users of digital financial services.

The UK decision allows the company to put more resources behind those markets rather than continue spending on a relatively new operation in a competitive remittance market.

Customers and Staff

Moniepoint said MonieWorld customers will receive information about the shutdown, including details on outstanding transactions, access to funds and the timetable for the closure.

The company hasn’t announced a final date for the shutdown.

Most employees on the MonieWorld team will be moved into other roles within Moniepoint, the company said. Some positions will change as the UK operation is closed.

For Moniepoint, the move leaves Africa as the main focus of its expansion plans. Nigeria provides the company with an established customer base and operating infrastructure, while its investment in Kenya gives it a foothold in another large African financial market.

The UK exit also shows the limits of a strategy that requires fintech companies to build new regulatory and operational infrastructure before they can scale in foreign markets. Moniepoint is now choosing to put more of that investment behind businesses where it already has customers and a regulatory presence.

Apple Unveils M6 Mac Mini as AI Push Moves Computing Onto Devices

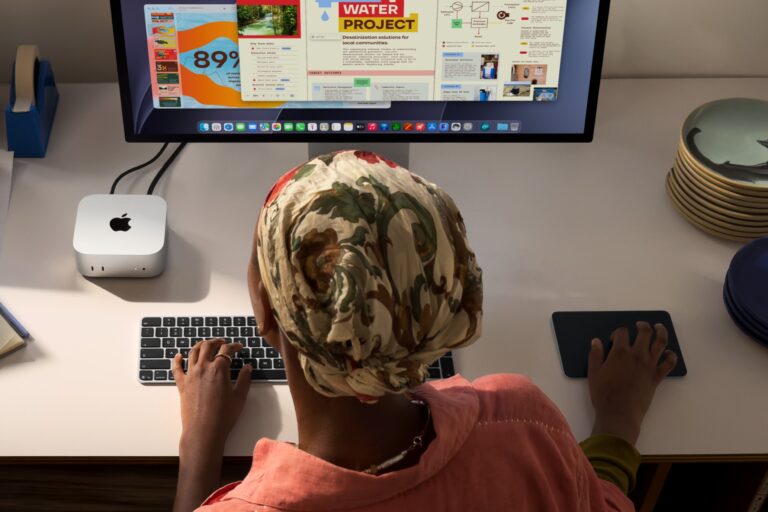
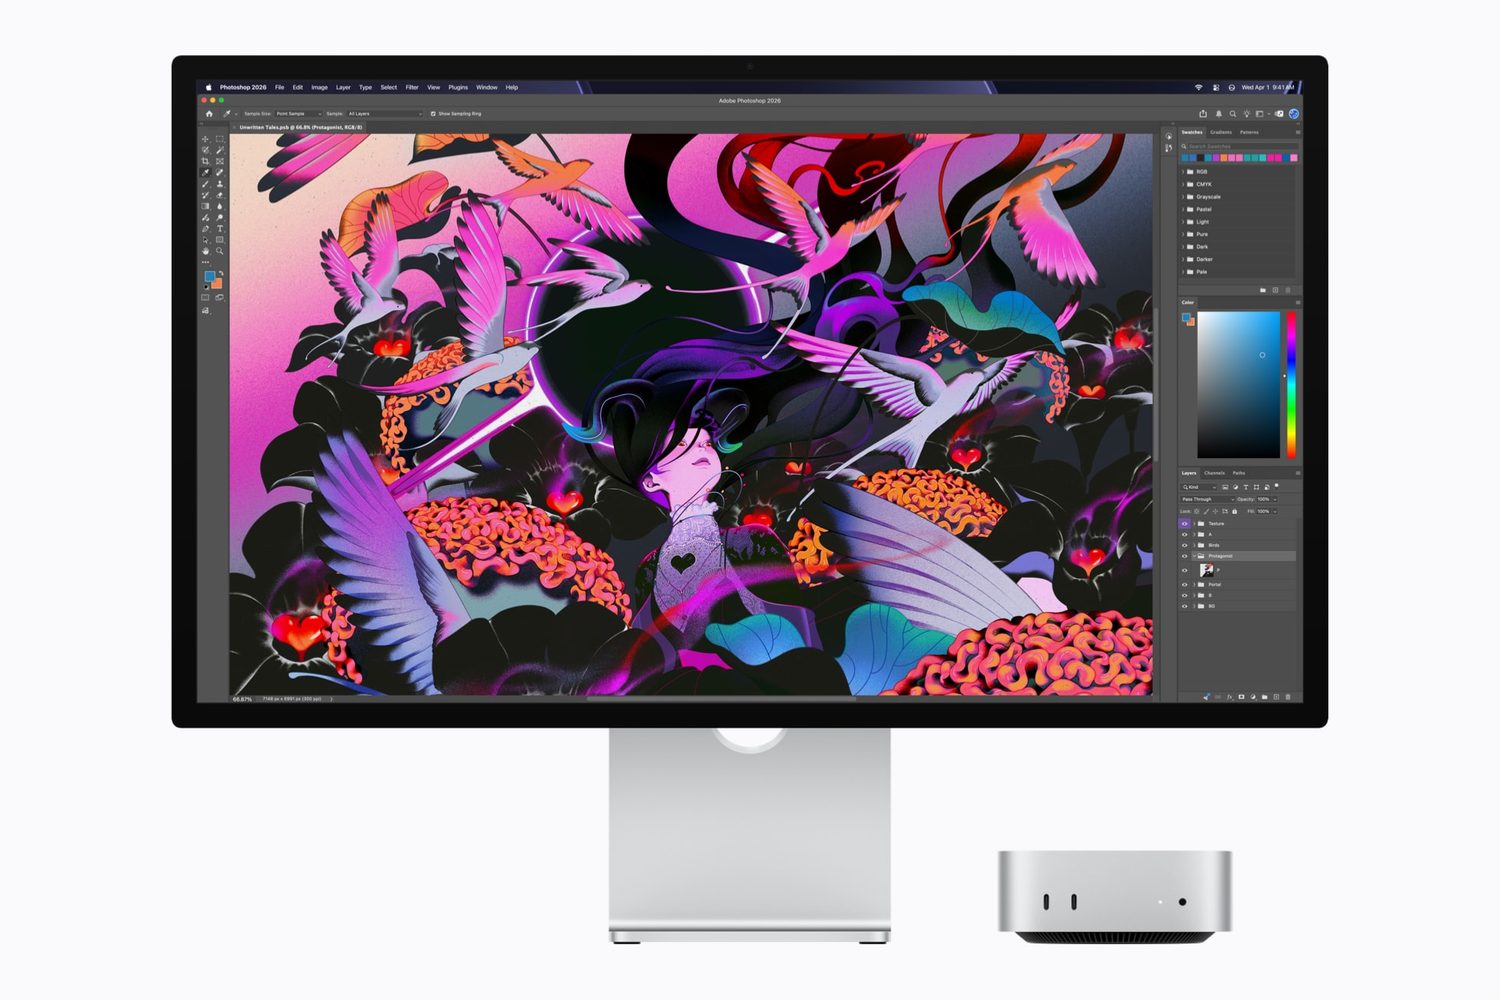
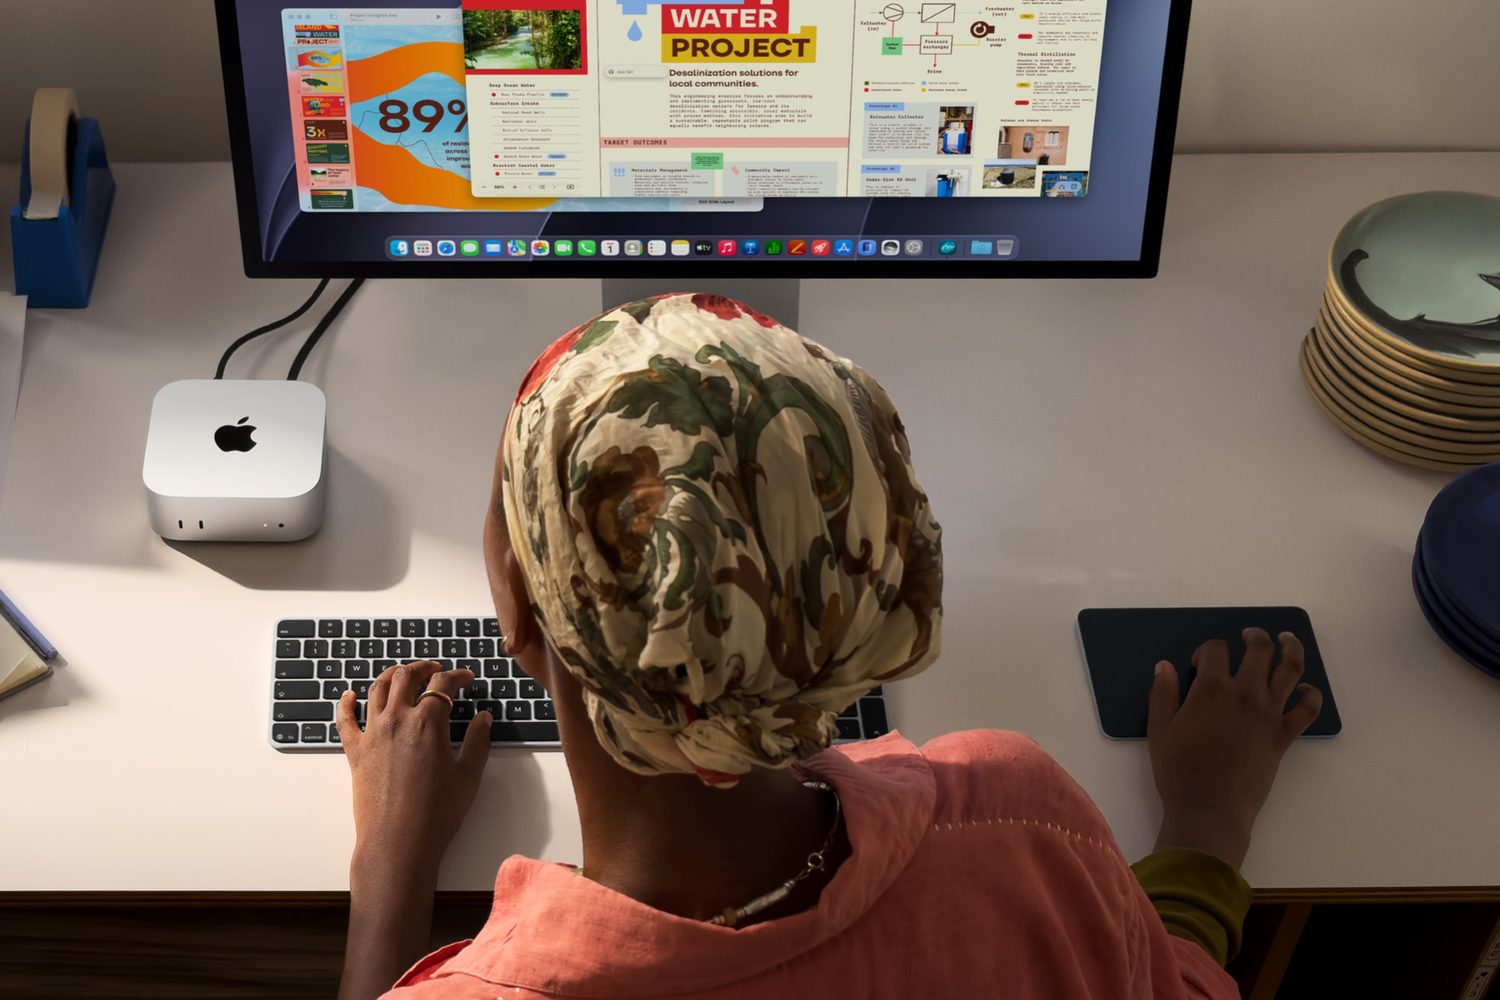
Apple unveiled a new Mac mini powered by its M6 chip, positioning the compact desktop as a machine for running artificial-intelligence workloads locally as the company pushes more computing away from the cloud and onto consumer devices.

The new Mac mini delivers up to four times faster AI performance than the previous M4 model, along with twice the graphics and storage performance and a 40% increase in CPU performance, Apple said Tuesday. A higher-end M5 Pro version is aimed at developers, creative professionals and other users running demanding AI and graphics workloads.

The launch reflects a broader shift in personal computing as generative AI and software agents demand more processing power. Apple is betting that its own silicon can handle increasingly sophisticated workloads directly on the device, reducing reliance on cloud infrastructure and allowing more AI processing to happen locally.

The M6 Mac mini has a 12-core CPU and 12-core GPU, with Neural Accelerators in every GPU core and a dual 16-core Neural Engine. It starts with 16GB of unified memory and can be configured with up to 32GB, while memory bandwidth reaches 170GB per second.

Apple says the M6 model can deliver up to four times faster AI performance and twice the graphics performance of the M4 Mac mini. Storage performance is also up to twice as fast, giving the machine gains across both traditional computing and AI workloads.

The M5 Pro version raises the performance ceiling, with configurations reaching 18 CPU cores, 20 GPU cores and 64GB of unified memory. Its memory bandwidth reaches 307GB per second, making it better suited to larger AI models, professional video production, 3D rendering and other computationally intensive workloads.

Apple says the M5 Pro can process large-language-model prompts up to 8.5 times faster than a Mac mini with M2 Pro. It also delivers substantial gains in ray-tracing performance, while its Thunderbolt 5 connectivity allows multiple Mac mini systems to be connected for larger on-device AI workloads.

Mac mini M6 vs. M5 Pro

SpecificationMac mini with M6Mac mini with M5 Pro
Starting price (US)$899$1,699
CPU12-coreUp to 18-core
GPU12-coreUp to 20-core
Neural processingDual 16-core Neural Engine + Neural AcceleratorsNeural Accelerators in every GPU core
Unified memory16GB, configurable to 32GBUp to 64GB
Memory bandwidthUp to 170GB/s307GB/s
AI performanceUp to 4x faster than M4Up to 8.5x faster LLM prompt processing than M2 Pro
GraphicsUp to 2x faster than M4Up to 4.5x faster ray-tracing rendering than M2 Pro
Ethernet2.5Gb, 10Gb option2.5Gb, 10Gb option
WirelessWi-Fi 7, Bluetooth 6Wi-Fi 7, Bluetooth 6
Thunderbolt3 × Thunderbolt 43 × Thunderbolt 5
AvailabilitySept. 22, 2026Sept. 22, 2026

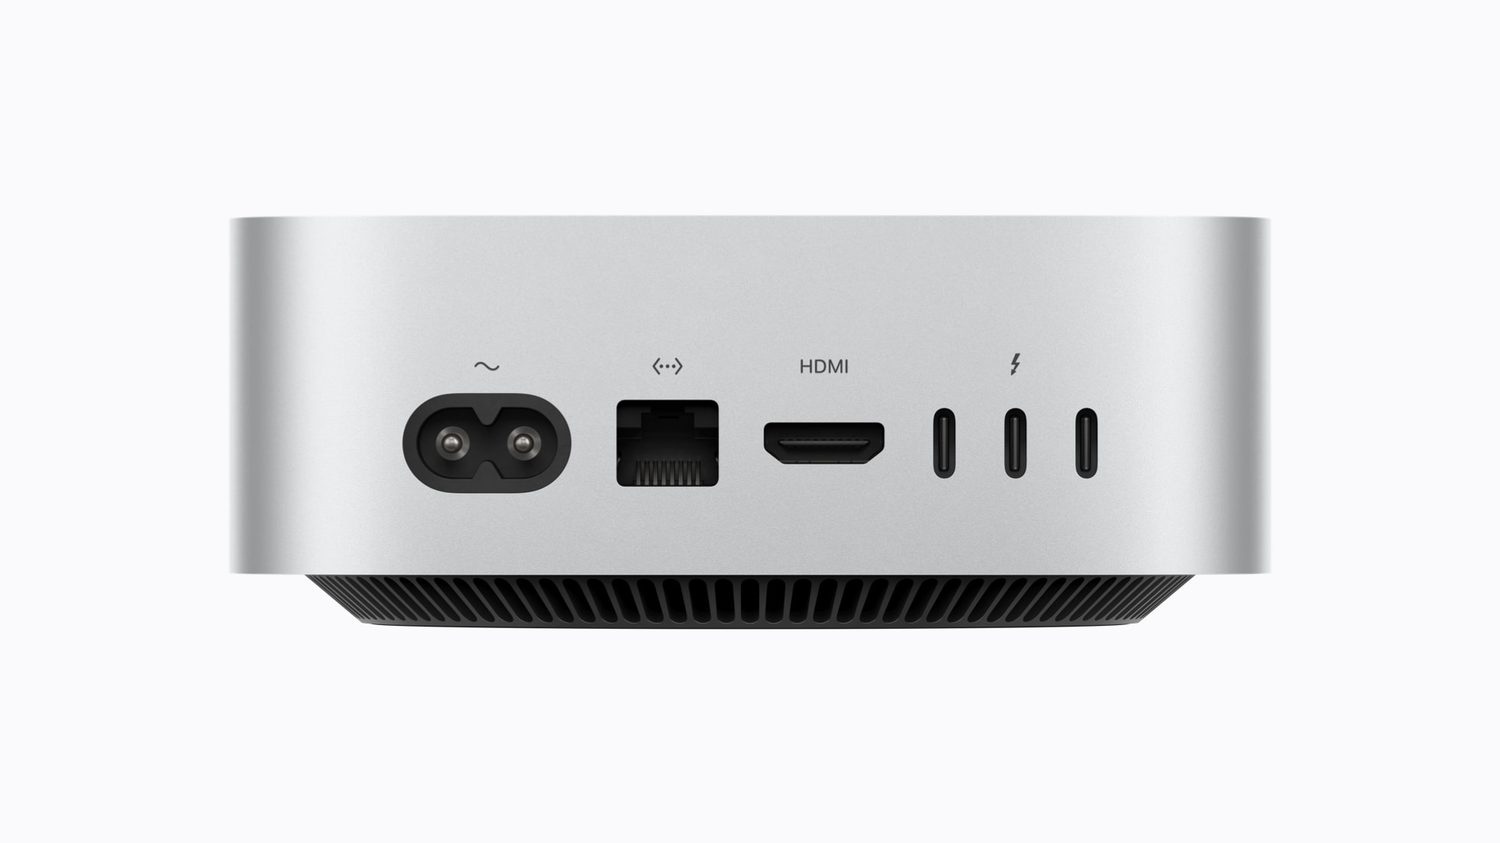
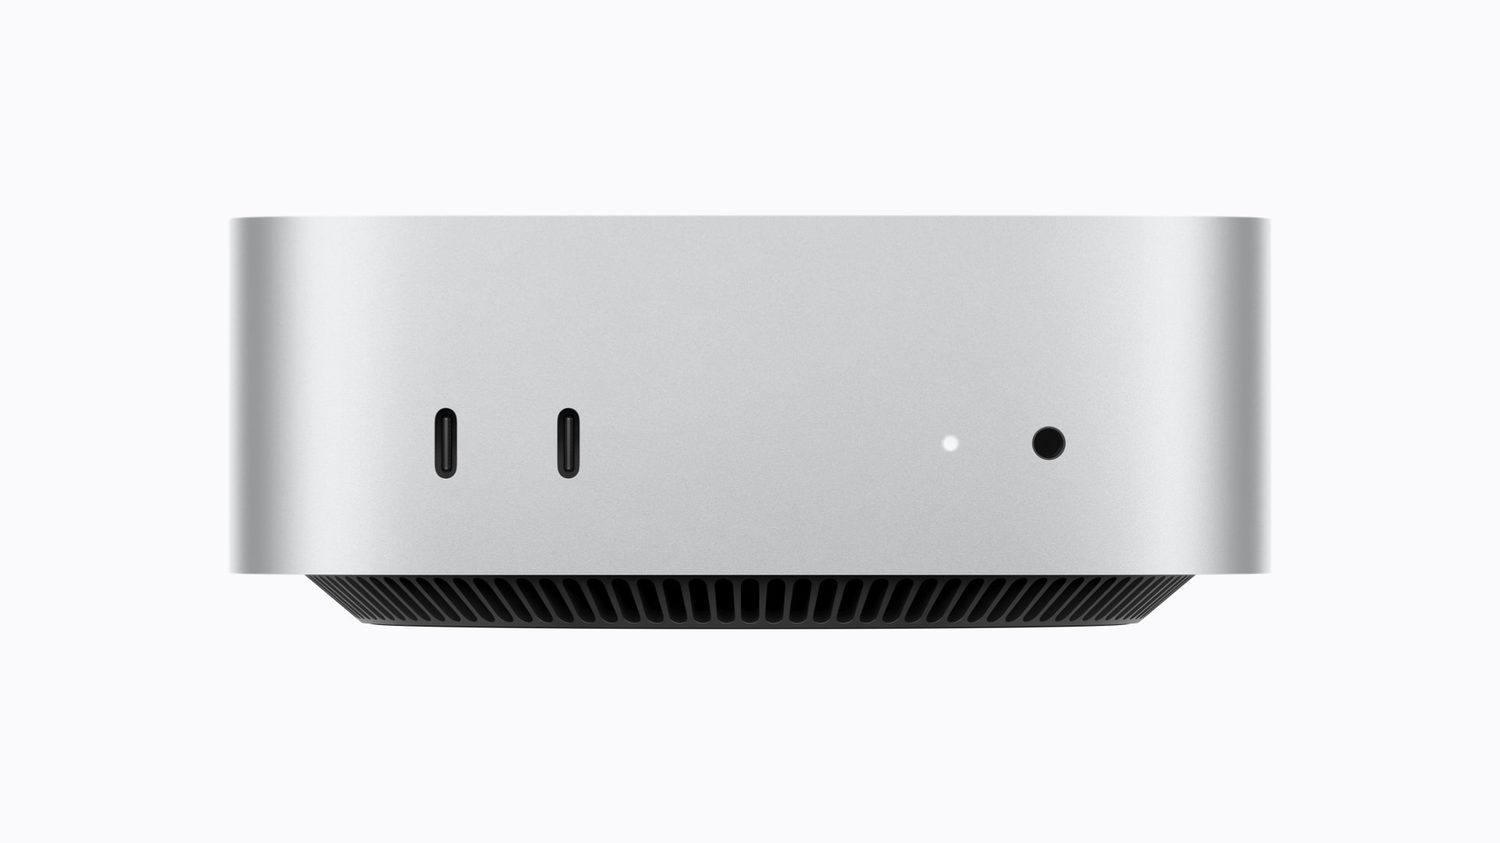
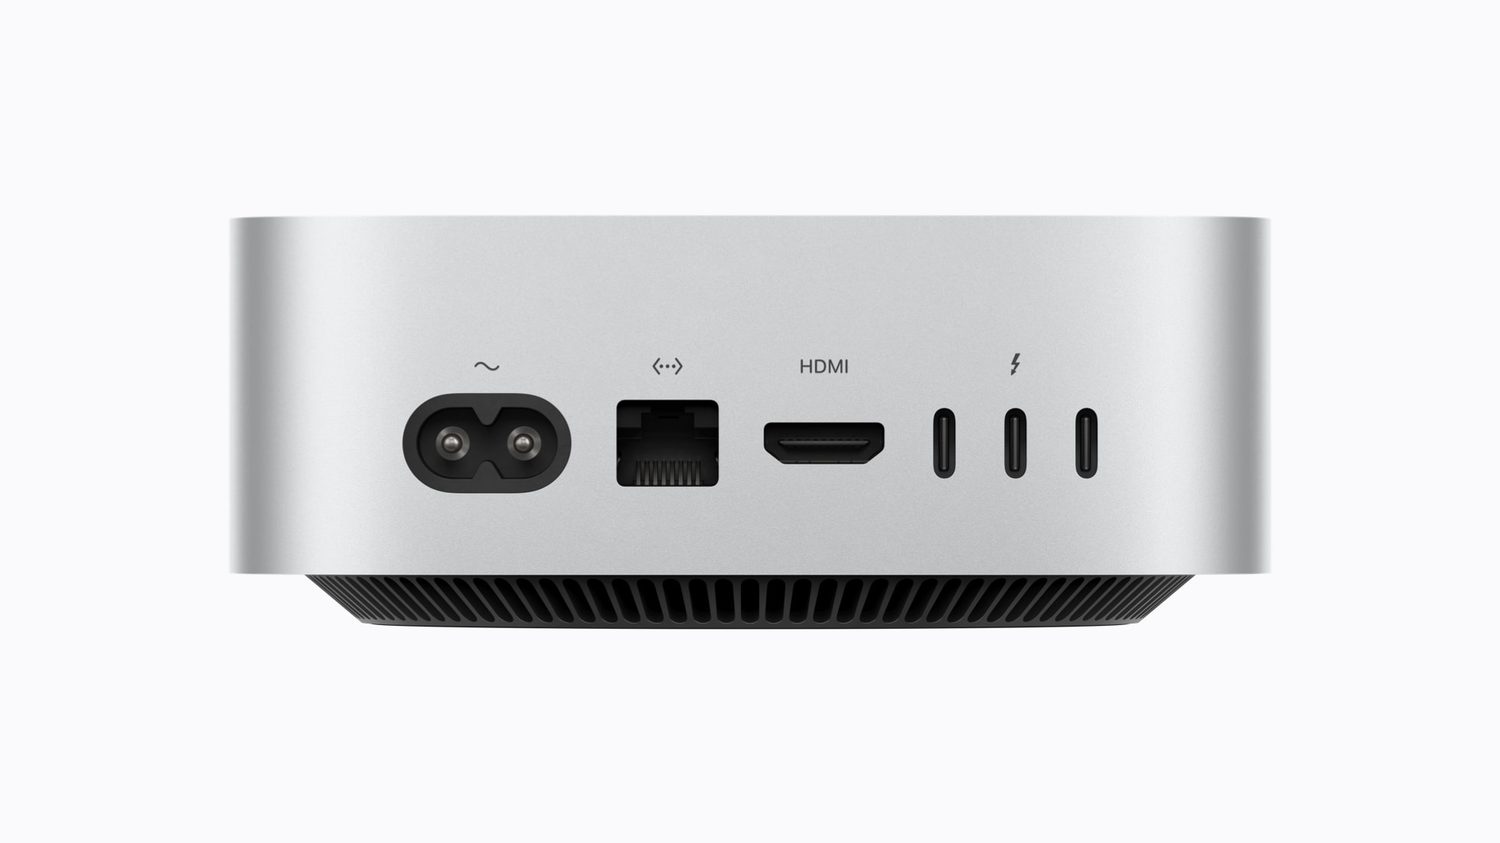
Connectivity has also been upgraded. Both models support Wi-Fi 7, Bluetooth 6 and 2.5-gigabit Ethernet, with 10-gigabit Ethernet available as an option. The M6 version has three Thunderbolt 4 ports, while the M5 Pro moves to Thunderbolt 5.

Apple is also linking the hardware to its broader AI software strategy. The new Macs are designed to support macOS 27 and the next generation of Apple Intelligence, including new Siri AI capabilities and workflows that can operate across applications.

That combination of silicon and software is central to Apple’s strategy. Rather than treating AI as a feature that users access primarily through the cloud, the company is building machines capable of running models and AI-powered workflows directly on the computer.

The approach could become increasingly important as AI agents move beyond answering questions toward performing tasks on behalf of users. Local processing can reduce latency and, in some cases, limit the amount of personal information that needs to leave the device.

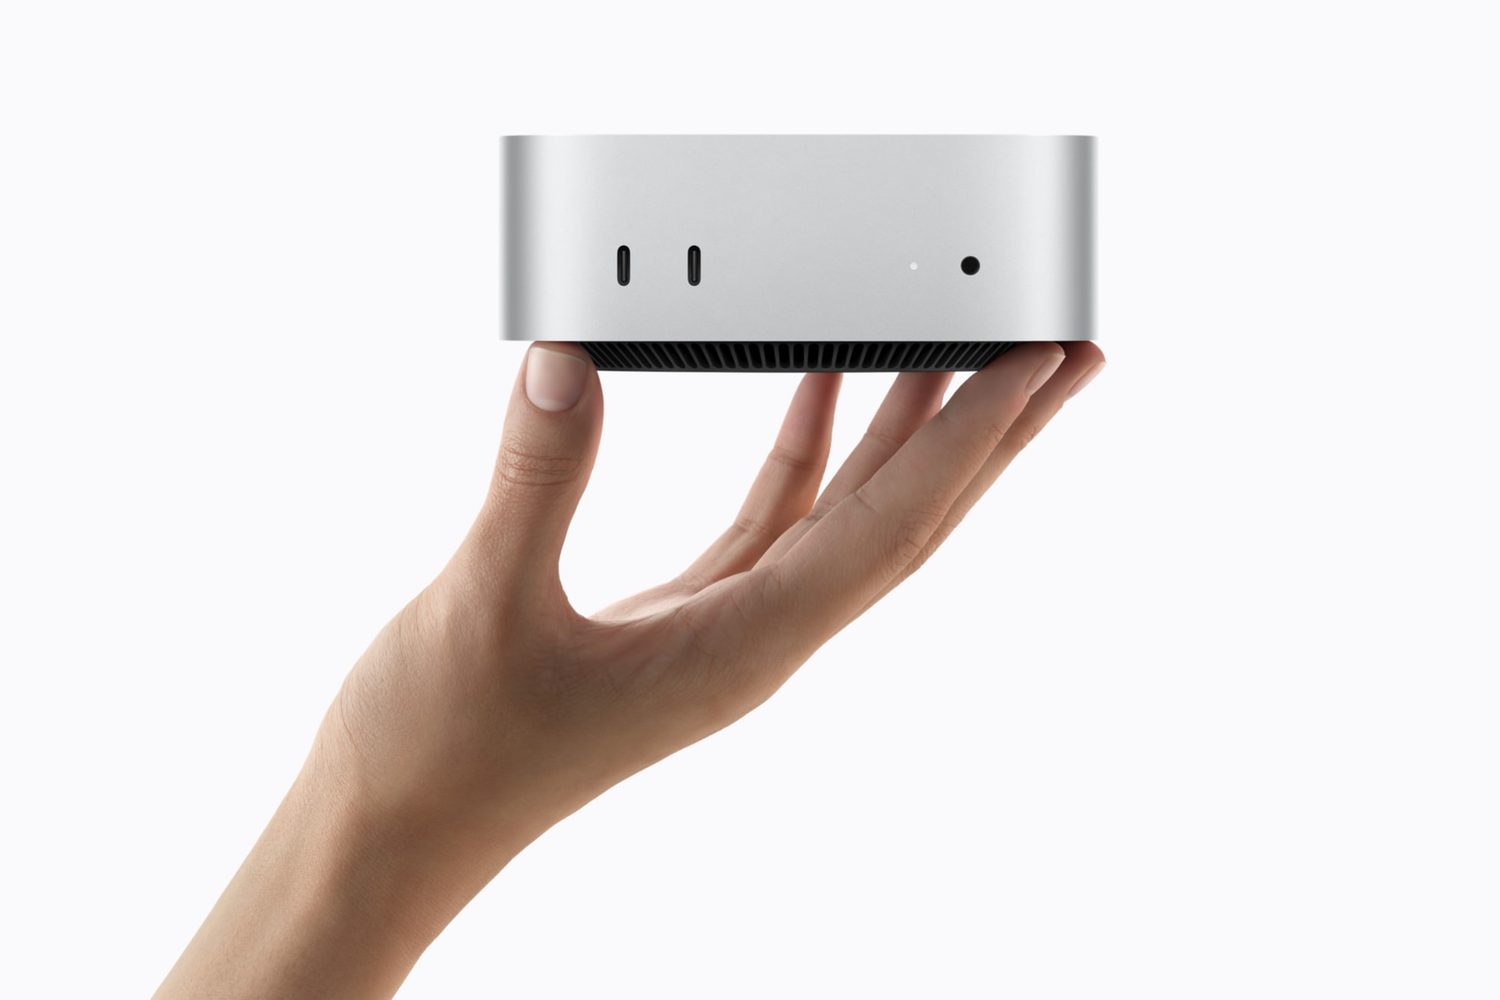
Apple has kept the Mac mini’s compact five-by-five-inch footprint while substantially increasing its processing capabilities. The M6 is also Apple’s first 2-nanometer chip, underscoring the company’s effort to improve performance and efficiency without moving to a larger desktop design.

The M6 Mac mini starts at $899 in the US, while the M5 Pro version starts at $1,699. Apple began taking preorders Tuesday, with customer deliveries and retail availability scheduled for Sept. 22.

For Apple, the significance of the launch extends beyond a faster desktop. The Mac mini gives the company a relatively compact and lower-cost platform for its broader push toward on-device AI — where computers increasingly process models locally and act on a user’s behalf rather than simply running conventional applications.

Flowt Raises Pre-Seed Funding to Expand AI-Driven Lending to African Climate Businesses

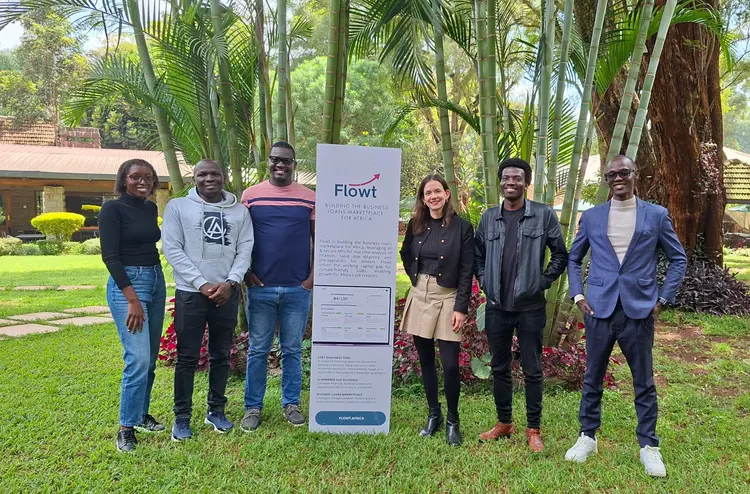
Flowt, a Nairobi-based financial technology startup has raised pre-seed funding to expand access to working capital for Africa’s climate-focused small businesses.

Founded by Elana Laichena, Flowt raised the pre-seed round from Delta40 Fund I, Impacc and Argidius Foundation and has issued its first working capital facility to GreenBay, a Kenyan refurbished and pre-owned appliances and solar home systems firm.

“Funders in Africa have three bad options when they look at a small business. Ask for collateral it does not have. Spend six months on due diligence, which makes a small loan uneconomical. Or assume the worst, price for it, and charge an interest rate the business cannot afford,” Laichena, Flowt’s founder and chief executive, said.

“Flowt lends against verified transaction history, which makes working capital both fast and affordable,” she said.

Flowt uses artificial intelligence to analyze financial information from bank accounts, mobile-money records and accounting systems, allowing lenders to assess businesses using transaction history rather than traditional collateral and plans to use the funding to expand its lending operations in Kenya and develop a financial data assessment platform for lenders and investors.

Flowt is entering a field served by platforms such as Pezesha, Pngme, Numida, Float, TradeDepot, Kuunda, Kwara and 4G Capital among others. These companies operate across financial-data infrastructure, alternative credit scoring, SME lending, embedded finance and working-capital financing.

However, the market is big as many businesses fail to raise capital as they don’t meet criteria needed by microfinance institutions and commercial banks, leaving them dependent on expensive or limited sources of capital.

According to the African Development Bank, SMEs contribute over 40 percent of GDP in many African countries and employ nearly 80 percent of the continent’s workforce yet only about 20 percent of SMEs in Africa have access to formal financing, leaving a massive funding shortfall of about $330 billion every year.

Flowt therefore argues that a lack of standardized and reliable financial information is one of the main reasons lenders struggle to serve the segment. Flowt provides its financial health assessment through a platform that allows businesses to upload bank and M-Pesa statements or connect accounting platforms including QuickBooks, Zoho and Odoo.

The company provides short-term loans through Choice Bank, a microfinance bank regulated by Kenya’s central bank. Flowt said it aims to reach a loan book of $1 million by the end of 2026 as it extends financing to more climate-smart businesses. The company also plans to generate revenue from software subscriptions for businesses and financial intelligence tools for investors and lenders. It said its longer-term goal is to build a financial data layer covering African climate-focused small and medium-sized businesses.

“A lender that only lends has to raise capital forever in order to grow,” Laichena said. “The data we build to underwrite a loan is worth something to the business that generated it, and worth something again to the investor trying to find that business.”

The funding comes as investment in African climate technology has grown rapidly. Flowt said climate technology attracted more than $1.5 billion in African venture funding in 2025, making it the continent’s largest venture funding category among disclosed investments.

For investors, however, smaller climate businesses can remain difficult to finance because the cost of assessing relatively small transactions can outweigh the potential returns.

Flowt was incubated by Delta40 Venture Studio, where Laichena previously served as managing director for Kenya. She has also worked at Open Capital and previously founded a business that converted sugarcane waste into an alternative fuel product. Delta40 is providing venture-building support, while Impacc and Argidius Foundation support its techmdevelopment and pilot lending.

“Africa’s climate SMEs are generating real revenue, creating jobs, and delivering measurable climate impact. They are not unbankable. They are underdocumented,” said Lyndsay Holley-Handler, founder and managing partner at Delta40.

Flowt said its current fundraising remains open as it prepares to expand its lending portfolio. It’s objective is not to replace commercial banks but to make businesses sufficiently transparent and measurable to eventually access conventional financing. Flowt aims to help firms establish a verified financial record before graduating to larger lenders and banks.

NTT DATA, Palo Alto Networks Form Global Alliance, Target $1 Billion in Joint Business

0

NTT DATA and Palo Alto Networks have formed a multi-year global strategic alliance to help businesses secure the adoption of artificial intelligence, with the companies targeting $1 billion in joint business by the end of 2029.

The agreement combines Palo Alto Networks’ AI-powered cybersecurity platforms and Unit 42 threat intelligence with NTT DATA’s consulting, engineering and managed services, the companies said on Tuesday.

The partnership is Palo Alto Networks’ first strategic alliance of this kind with a global systems integrator, according to the companies, as businesses increasingly deploy AI systems while facing new cybersecurity, governance and compliance risks.

The companies will work together on cybersecurity strategy, implementation and managed services, supported by joint engineering, co-innovation and coordinated global delivery.

“AI is reshaping both business and cybersecurity, making deep ecosystem collaboration more important than ever,” Palo Alto Networks Chairman and CEO Nikesh Arora said.

The alliance will initially focus on six areas: autonomous security operations centers, AI governance, identity security, Zero Trust and secure access service edge, resilient cloud environments and firewall modernization.

The companies said the solutions will initially target highly regulated and critical industries, including financial services, healthcare, manufacturing and the public sector.

Focus on AI security

The partnership comes as companies move from experimenting with generative AI toward deploying more autonomous systems and AI agents across business operations.

Those systems can introduce new security challenges by gaining access to corporate applications, data and infrastructure. Managing the identities and permissions of AI agents, while ensuring their actions can be monitored and governed, is becoming an emerging concern for enterprise security teams.

NTT DATA and Palo Alto Networks said their AI governance offering will help organizations manage security and risk throughout the AI lifecycle.

The companies will also work on identity security covering employees, machines, workloads, devices and AI agents.

Their autonomous security operations offering will use agentic AI and managed services to help organizations detect, investigate and respond to cyber threats more quickly.

The alliance also includes Zero Trust and SASE architectures designed to protect users, applications and data, as well as cloud security capabilities aimed at improving visibility, compliance and risk management across multi-cloud environments.

Firewall modernization will be another area of focus as enterprises seek to reduce the complexity of legacy security infrastructure.

Thousands of certified professionals

NTT DATA will support the alliance with more than 2,000 Palo Alto Networks-certified professionals, as well as dedicated Forward Deployed Engineers and joint engineering teams.

The Japanese technology services company said it has more than 7,500 cybersecurity professionals, more than 70 delivery centers and more than 20 Cyber Defense Centers globally.

Palo Alto Networks will contribute its cybersecurity platforms and Unit 42 threat intelligence capabilities.

The companies said NTT DATA will receive early access to new platform features through direct engineering collaboration, allowing it to develop and deliver security services around new capabilities more quickly.

“AI is redefining every aspect of the enterprise, but it is also transforming the threat landscape at unprecedented speed,” NTT DATA CEO and Chief AI Officer Abhijit Dubey said.

The alliance is intended to give enterprises a single approach covering cybersecurity consulting, technology deployment and ongoing managed services, the companies said.

For Palo Alto Networks, the agreement expands its reach through a global technology services provider with expertise across enterprise infrastructure and industry-specific systems.

For NTT DATA, it strengthens its cybersecurity and AI services offering as businesses seek to deploy AI while managing the associated security risks. The companies aim to generate $1 billion in joint business from the alliance by the end of 2029.

How Medical Technology Can Negatively Impact Effective Cancer Care

0

While technology has brought many celebrated breakthroughs in general healthcare, it’s important not to ignore the negative impacts it has introduced, especially in cancer care. Patients have suffered significant health challenges caused by medical technological failures, leading to a deteriorated quality of life and costly treatments. 

Some of these medical failures qualify for legal compensation with the help of reputable personal injury attorneys. Below, we’ll look at how modern medical technologies can negatively impact cancer care and how you can maintain a safer approach or even compensation if you fall victim.

Risk of Over-Reliance on Technology

When medical practitioners over-rely on technology for even basic functions, the risk of detachment from important patient interactions increases. While data and test results are important for a successful diagnosis, physicians should not ignore basic diagnostic techniques, such as physical examinations and thorough patient histories. Over-reliance on technology makes doctors forget the simplest diagnostic approaches that would give them more accurate and reliable answers.

Overreliance on diagnostic tests can lead to unnecessary stress for patients, higher healthcare costs, and even misdiagnoses when results are misinterpreted. These mistakes can cost patients time and money treating the wrong diseases, which expose them to far worse risks, especially in the case of cancer. If this happens, you can seek compensation for a misdiagnosis with the help of relevant firms, such as a lung cancer law firm, depending on the type of misdiagnosis.

Data Privacy and Security Risks

With the rising use of technology, more patient and medical institutions’ data is gathered and stored on the internet. These electronic health records and other digital technologies only expose users to the prying eyes of cybercriminals and scammers. Patients are often the hardest hit when a breach occurs, as their sensitive medical information is exposed to malicious actors or third parties. 

If not recovered in time, the information in the wrong hands can be used to commit crimes or engage in other fraudulent activities. This can expose the victims to identity theft and other security risks.

Disconnected Human Interactions

One of the key ingredients for successful treatment of chronic illnesses like cancer is the instillation of hope in patients. Face-to-face communication between physicians and patients helps convey this hope and build stronger connections for effective recovery. 

However, when this communication pattern is replaced with the latest communication technologies, patients miss out on one of the most important aspects of effective recovery. When patients feel less cared for, even with the right medical attention, they may not recover fully or fast enough.

High Overall Costs

The adoption of technology in cancer care might have streamlined cancer treatment, but this efficiency comes at a cost that’s too high for many patients to bear. Patients in low-income areas may miss out entirely on their only line of hope if technologies remain expensive and accessible only to the few wealthy individuals. Healthcare facilities may also need to invest substantial resources to implement and maintain these technology systems.

While technology is a necessary part of modern healthcare, overreliance on it can lead to various costly challenges for both healthcare facilities and their patients. Understanding these challenges and mitigating them early can help secure safer, more affordable cancer care for more patients worldwide.

South Africa’s Verascient Raises $1.2 Million to Build Infrastructure for AI-Native Businesses

0

South African AI infrastructure startup Verascient has raised $1.2 million in an oversubscribed seed round as it builds technology designed to help businesses move from experimenting with artificial intelligence to deploying AI agents across everyday operations.

The round was led by Founder Collective, an early investor in companies including Uber, Airtable and Whoop. Andrena Ventures, Cambridge Enterprise and Summit Ventures also participated, alongside angel investors Alan Knott-Craig and Shayne Mann.

Verascient plans to use the capital to expand its engineering team, deepen its technology and support more enterprise deployments.

Founded by Keagan Stokoe and Emile Dos Santos Ferreira, the Cape Town-based startup is targeting financial services, insurance and logistics, industries where critical institutional knowledge is often scattered across emails, documents, meetings, spreadsheets and internal systems.

Building the infrastructure underneath enterprise AI

Verascient is positioning itself differently from the growing number of startups building AI assistants and applications. Its core technology is a temporal knowledge graph that maps an organization’s knowledge, workflows and history, allowing AI agents to operate with a deeper understanding of the business.

“At the centre of Verascient’s technology is a temporal knowledge graph designed to build and maintain a comprehensive understanding of an organisation,” said Ferreira, Verascient’s co-founder and CTO. The system is designed to preserve the history, permissions and provenance associated with information while making that knowledge available to AI agents.

The problem Verascient is targeting is increasingly important as businesses adopt AI.

Giving employees access to an AI model does not necessarily give that model an understanding of how a particular company works. Information may exist across dozens of systems, while key decisions and institutional knowledge can remain locked inside individual employees.

Ferreira argues that this creates a distinction between simply giving workers AI tools and building an organization capable of operating around AI.

“There is a significant difference between giving employees access to an AI tool and building a company that can operate intelligently with AI,” Ferreira said.

Verascient’s platform includes an agent-to-agent messaging protocol, background agents that can operate without continuous prompting, role-based access controls and more than 1,000 integrations with existing business systems. The company is also taking a hands-on approach to implementation.

Rather than leaving customers to determine how AI should fit into their operations, Verascient deploys AI engineers who work alongside company teams to identify inefficiencies and build workflows around specific business problems.

From hallucination detection to an AI operating system

Verascient initially developed technology for detecting hallucinations in AI models but it failed as large language models became more capable and fixed hallucination forcing the founders to push aside the standalone hallucination detector was becoming smaller. The company pivoted toward the infrastructure needed to make AI useful inside businesses. That shift has placed Verascient in a part of the AI market focused less on the model itself and more on the systems surrounding it. Stokoe said the opportunity is to rethink how businesses perform important functions rather than simply automate isolated tasks.

“AI is far more capable than most businesses yet realise,” Stokoe said. “The opportunity is to improve existing processes and, in many cases, rethink how the company works altogether.”

He said Verascient starts with areas including revenue, operations, customer experience, decision-making and delivery, then builds the systems and agents needed around those functions.

The objective, he said, is to create businesses that become progressively faster and more capable as they adopt more AI-enabled workflows.

South Africa becomes the talent bet

The funding round is also significant because Verascient intends to build its engineering organization in South Africa. The company is recruiting engineers and AI builders with the ambition of attracting the country’s highest-level technical talent.

Stokoe described the target as the “top 1%” of AI talent in South Africa, with an emphasis on people capable of taking ownership of difficult technical and commercial problems. That strategy comes at a time when African technology companies continue to compete with global technology firms for scarce engineering talent. For Verascient, however, South Africa is not simply a lower-cost engineering base. The founders are positioning the country as a source of technical talent capable of building products for international markets.

“We are looking for high-agency people with the curiosity, technical depth and ambition to build something meaningful to solve real-world problems,” Stokoe said.

He also sees AI as creating opportunities for South African engineers rather than simply eliminating jobs.

“AI will change the shape of many jobs,” Stokoe said. “It also creates a real opportunity for South Africa to develop more people who can build and deploy these systems in the real world.”

Founders bring deep AI and technology experience

Ferreira began programming at the age of 12 and later became an early developer at Replit. While still in high school, he built an on-device AI assistant that attracted more than 200,000 users and won Most Innovative Solution at the App of the Year Awards. He later completed an MPhil in Advanced Computer Science at the University of Cambridge and has worked on research involving enterprise AI costs and AI energy efficiency.

Stokoe was previously part of the founding team at Fibertime, a South African pay-as-you-go fiber provider that has grown to more than 1.5 million users per month. He also founded Purple Dorm, an AI consultancy that worked with organizations in South Africa and the UK. The founders are now attempting to turn that experience into a global enterprise AI company built from South Africa.

Why investors are backing the company

Founder Collective’s participation gives Verascient a notable early-stage technology investor, while Cambridge Enterprise adds a connection to the university ecosystem where Ferreira developed his technical background. The company is betting that as businesses deploy multiple AI agents, they will need a common layer capable of giving those agents access to reliable organizational knowledge and the ability to operate within established permissions and workflows.

That is the thinking behind Verascient’s “operating system” analogy. The temporal knowledge graph acts as the underlying information layer, while agent-to-agent communication allows different AI processes to work together. Background agents can perform tasks without being continuously prompted, while access controls determine what those agents are allowed to see and do.

“When running on our system, an agent doesn’t start from a prompt, it starts with the collective knowledge and established workflows of the company,” Ferreira said.

That distinction could become increasingly important as enterprise AI moves beyond individual productivity tools toward systems capable of carrying out multi-step business processes.

For now, Verascient is using its new $1.2 million to build the team and infrastructure required for that transition. Its larger ambition is to make South Africa a base for a company competing in one of the fastest-growing segments of the global technology industry: the infrastructure that allows businesses to operate with AI at their core.

ASUS ROG Targets Kenya’s Growing Gaming and Creator Economy at Otamatsuri 2026

0

ASUS Republic of Gamers is stepping up its focus on Kenya’s gaming and digital-creation market, using Nairobi’s Otamatsuri 2026 to put high-performance hardware in front of a growing community of gamers, artists, animators and developers.

The ASUS ROG brand was the official technology partner for the second edition of Otamatsuri, an anime and manga convention held Saturday at the Carnivore Grounds in Nairobi. The event brought together communities around Japanese and Korean pop culture, including gaming, cosplay and music.

ASUS said more than 4,000 people attended the event, giving the company an opportunity to position its gaming hardware beyond traditional PC gaming and toward a broader creative economy.

At its experiential booth, attendees tested gaming laptops, handheld devices and other hardware designed for demanding workloads. The company targeted users whose computing needs increasingly overlap across gaming, video production, animation, graphic design and software development.

The push comes as AI is becoming another consideration in the purchase of premium computers. ASUS showcased Copilot+ PCs equipped with dedicated Neural Processing Units, or NPUs, which are designed to handle certain AI workloads locally rather than relying entirely on cloud computing.

For Kenyan creators, that could translate into faster AI-assisted workflows in supported applications, while reducing the need to send every task to remote servers. For ASUS, the broader opportunity is to sell high-performance machines as productivity and creative tools rather than products aimed only at gamers.

The company also demonstrated its latest ROG hardware, including the ROG Strix SCAR 18 G835, ROG Ally, ASUS TUF Gaming A15 and TUF Gaming F16.

The G835 designation refers to the 2026 ROG Strix SCAR 18, ASUS’s flagship 18-inch gaming laptop. The machine is positioned for demanding gaming as well as workloads such as content creation, multimedia editing, game development and AI applications.

The event also highlighted the challenge facing premium hardware brands in markets such as Kenya: convincing consumers that expensive devices offer value beyond specifications.

ASUS used the event to engage consumers around technical support, durability and product longevity, including its Perfect Warranty service, which provides localized protection against certain accidental damage.

That after-sales proposition could become increasingly important as more Kenyan consumers and businesses invest in higher-priced laptops for professional creative work. Hardware failures can represent more than a repair bill for freelancers and creators whose income depends on having a functioning workstation.

The company’s local distribution strategy is also becoming more important as the gaming and creator markets develop. The ROG and ASUS models showcased at Otamatsuri are available in Kenya through authorized retail partners Elevetus Technologies and Anisuma.

Otamatsuri itself illustrates the size of the audience technology companies are beginning to pursue. The 2026 convention was a full-day event at the Carnivore Grounds featuring anime, manga, cosplay, gaming and other elements of Japanese and Korean pop culture.

For ASUS, the opportunity extends beyond selling gaming machines. Kenya’s emerging creator economy needs computers capable of handling increasingly sophisticated workloads, while gamers represent a highly engaged technology audience that is often among the first to adopt higher-performance hardware.

By putting its products directly in front of those communities, ASUS is betting that the next generation of Kenyan PC buyers will see gaming hardware not simply as entertainment equipment, but as a platform for creating, developing and earning online.

Kenya Moves to Operationalize its National Cybersecurity Agency With Koyabe as Chair

0

Kenya is moving to operationalize its new National Cybersecurity Agency, appointing cybersecurity expert Dr. Martin Koyabe as chairman of the board as the government steps up efforts to protect critical digital infrastructure and the country’s expanding online economy.

Koyabe’s three-year term as Non-Executive Chairperson began Aug. 21, according to Gazette Notice No. 13506. His appointment is a key step in establishing the agency’s leadership structure.

The National Cybersecurity Agency was legally established on May 15 under Legal Notice No. 89, meaning the latest move is not the creation of the agency but the transition toward making it operational.

The agency is mandated to coordinate national cybersecurity, protect critical information infrastructure and strengthen Kenya’s ability to prevent and respond to cyber threats.

That responsibility is becoming more urgent as Kenya expands digital payments, mobile services, cloud computing, e-government and other online infrastructure. The Communications Authority detected 3.4 billion cyber threat events in the three months through March, underscoring the scale of the challenge.

Koyabe brings more than three decades of experience across ICT, telecommunications, cybersecurity, digital policy and emerging technologies. He has worked on cybersecurity capacity-building initiatives across Africa and served as a Senior Advisor for Africa at the Global Forum on Cyber Expertise.

He has also been involved in the African Union-GFCE cyber-capacity-building initiative, which supports efforts to strengthen cyber resilience across the continent’s 55 countries.

Koyabe is a founding partner and technical director at Africa Cyber Expertise, where his work has included national cybersecurity assessments, strategy development, regulatory advisory and cyber-capacity-building programs.

His academic background includes a PhD in Communication Engineering from the University of Aberdeen, according to his professional profile. He has also undertaken executive and professional studies at institutions including the University of Cambridge and Harvard Kennedy School.

The combination of technical and policy experience is significant for NCSA, whose mandate extends beyond responding to individual attacks. The agency is expected to coordinate cybersecurity across government and the private sector, assess the resilience of critical infrastructure, support incident response and help develop local cybersecurity capabilities.

Its responsibilities include operating the National Cybersecurity Operations Center, supporting sector-specific cyber operations centers, conducting vulnerability assessments and developing technical capabilities for cyber defense.

The agency is also expected to establish a Cybersecurity Center of Excellence focused on research, innovation and locally developed cybersecurity technologies.

For Kenya’s businesses, the agency’s emergence could push cybersecurity further into boardrooms. Banks, telecom operators, payment companies and other critical digital-service providers face growing pressure to manage cyber risk as an operational and financial threat rather than solely an IT issue.

The appointment comes as Kenya seeks to expand its digital economy and attract investment into technology and digital services. Protecting that infrastructure is increasingly tied to the country’s ability to sustain growth. Koyabe’s challenge will be turning a legally established institution into an effective national cybersecurity coordinator.

Sabvest Bets $47 Million on South Africa’s Fiber Expansion With Frogfoot and Vox

Sabvest Capital is investing about $47 million in South African telecommunications companies Frogfoot and Vox, betting that faster fiber expansion into lower-income communities can unlock growth in a market where millions of households remain without high-speed internet.

The investment holding company will subscribe for new shares in Frogfoot and Vox for $47 million, giving it an interest of at least 8.97% in the businesses. The transaction values the combined operations at about $900 million on an enterprise-value basis and about $525 million after debt. The figures are converted from South African rand at roughly 16 rand to the dollar on Aug. 24, 2026.

The deal gives Sabvest exposure to one of South Africa’s most important broadband infrastructure plays at a time when fiber operators are shifting their attention from affluent suburbs and business districts to townships and lower-income communities.

Frogfoot is South Africa’s fourth-largest fiber network operator and provides open-access fiber infrastructure for homes, businesses and other customers. Vox operates as a national internet service provider serving households, businesses and public-sector customers, with services spanning connectivity, voice, cloud, collaboration and cybersecurity.

The transaction also includes Hypa, Vox’s prepaid broadband business, which is targeting lower-income households through networks including Frogfoot Rise, Vuma Reach and Openserve.

Betting on the next wave of broadband growth

The investment comes despite the companies’ recent financial challenges.

Frogfoot and Vox reported a combined net loss after tax of about $16 million for the year ended Aug. 31, 2025, while their combined net asset value was negative by roughly $42 million.

Sabvest is therefore not making a conventional investment in profitable telecom operations. Instead, it is backing the value of the underlying fiber infrastructure and the potential for higher network utilization as the companies expand into markets that have historically been poorly served by fixed broadband.

That opportunity is substantial.

The companies are targeting as many as 15 million homes that could potentially be connected to high-speed internet, compared with about 4.5 million homes currently connected, according to Frogfoot Chief Executive Officer Abraham van der Merwe. The group plans to increase annual fiber deployment fourfold to about 360,000 homes a year, with much of the expansion focused on townships.

That makes the investment as much about market expansion as infrastructure ownership.

South Africa has one of the continent’s most developed telecommunications markets, but broadband access remains uneven. Fiber operators have traditionally concentrated on areas where household incomes and customer density can support the economics of network construction. The next stage of growth is likely to depend on whether operators can make fiber commercially viable in lower-income areas.

Capital to accelerate rollout

Sabvest’s investment forms part of a broader financing and shareholder restructuring involving several investors.

The largest shareholder grouping will be a consortium led by DNI 4PL Contracts and including Sabvest, Masimong Group and Draper Gain International. The consortium will hold about 34.8% of the companies, with DNI itself holding 18.13%. Sabvest currently owns about 19.4% of DNI directly and indirectly.

The wider transaction values the companies at about $900 million, comprising roughly $525 million of after-debt equity value and about $375 million of debt.

For Sabvest, the investment will be funded through new term bank debt rather than existing cash resources.

That financing structure highlights the investment thesis: Sabvest is committing capital to an infrastructure-heavy business where the payoff depends on scaling the network and increasing the number of paying customers connected to it.

Townships become the next fiber battleground

The shift toward townships reflects a broader change in South Africa’s broadband market.

For years, fiber companies focused on affluent residential neighborhoods and commercial centers, where customers were more likely to afford relatively expensive fixed broadband packages. The market is now moving toward prepaid and lower-cost offerings designed for customers with less predictable incomes.

Vox’s Hypa business is part of that strategy, while Frogfoot recently introduced Frogfoot Leap, a prepaid fiber service designed to provide uncapped broadband without long-term contracts.

The economics could become increasingly attractive if operators can reduce the cost of deploying networks while building sufficient customer density.

Van der Merwe has described the new capital as a way to significantly increase rollout velocity, particularly in townships and lower-income communities. The companies estimate that their addressable market could reach millions of additional households.

For consumers, the expansion could mean greater access to high-speed internet for education, digital financial services, remote work and small businesses. For investors, the opportunity is to turn previously underserved communities into a large new broadband customer base.

Sabvest takes an infrastructure bet

Sabvest, which has a market value of about $344 million, is making the investment through its wholly owned subsidiary Sabvest Finance and Guarantee Corporation.

The size of the investment is significant relative to Sabvest’s own market value, underscoring the importance of the transaction to its portfolio.

The investment also brings Sabvest closer to the operational growth strategy of Frogfoot and Vox, while the broader transaction brings together financial investors and an experienced management team.

Frogfoot has operated for more than 25 years and has built a substantial open-access fiber network across South Africa. Vox provides the customer-facing layer, giving the combined group exposure to both infrastructure and retail broadband economics. (Business Day)

That combination could become increasingly valuable as fiber penetration grows and operators compete for customers beyond the traditional middle- and upper-income market.

Transaction set for October

The boards of Frogfoot and Vox have approved the transaction, with the relevant agreements already executed. The investment is scheduled to become effective on Oct. 1, 2026, subject to the outstanding conditions being fulfilled by Sept. 24.

The deal leaves Sabvest with a minority position, but gives the investment group exposure to a broadband market that is entering a new phase of expansion.

The bigger bet is whether South Africa’s fiber industry can make the economics of connecting lower-income communities work at scale.

With a potential market of millions of unconnected homes and a target of 360,000 new homes passed or connected each year, Frogfoot and Vox are positioning fiber as less of a suburban premium service and more of a mass-market infrastructure business.

For Sabvest, the $47 million investment is a wager that the next significant growth opportunity in South African broadband will come not from connecting the richest neighborhoods, but from bringing high-speed internet to the communities that have been left behind.

SBM Bank Kenya Launches 34th Branch in Nanyuki Town

0

SBM Bank Kenya has opened its 34th branch in Nanyuki, Laikipia County, expanding its physical footprint into the Mt. Kenya region as the lender targets the area’s growing agriculture, tourism, conservancy, real estate and SME economy.

The branch, located at Peak Place Building in Nanyuki Town, gives SBM a presence in a market anchored by major conservancies including Ol Pejeta, Lewa, Borana and Loisaba, as well as high-end tourism lodges, horticulture exporters, agribusinesses, real estate developers and SMEs operating across Nanyuki and Timau.

The lender is also positioning the branch to serve businesses and institutions connected to the British Army Training Unit Kenya (BATUK), alongside farmers, flower and horticulture exporters and other institutional customers in the region.

The expansion comes as SBM Bank moves to convert a sharp improvement in financial performance into balance-sheet growth and deeper customer acquisition outside Kenya’s largest urban centers.

For the six months ended June 30, 2026, SBM Bank Kenya reported a 171.3% increase in profit before tax to KSh548 million, from KSh202 million a year earlier. Net profit rose 88.2% to KSh380.2 million, while operating profit increased 279% to KSh852 million.

Customer deposits increased 24% to KSh94 billion, while net loans and advances grew 18% to KSh54.1 billion. Total assets stood at KSh109.9 billion at the end of June, compared with KSh105.7 billion in December 2025.

The bank also reported an improvement in asset quality, with its gross non-performing loan ratio falling to 17.3% from 32.4% a year earlier. Shareholders’ equity increased to KSh11.1 billion.

The Nanyuki expansion therefore comes at a point when SBM is showing greater capacity to lend and take on new customers, particularly in markets where businesses require relationship-based banking alongside digital services.

“Nanyuki is exactly the kind of market our strategy is built for. The region is a high-growth economy where relationship banking and digital convenience should work together,” said SBM Bank Kenya CEO Bhartesh Shah.

“We are determined to bring banking closer to our customers at a time when our own numbers show the model is working. This branch is not a one-off activity, it is proof that we can back our growth ambitions with a strong balance sheet,” Shah said.

Laikipia Governor Joshua Irungu said the region’s mix of agribusiness, tourism, real estate and manufacturing presents significant opportunities for private-sector investment.

“From agribusiness and tourism to real estate and manufacturing, the potential here is enormous, and we are ready to work with partners who share our ambition for this region,” Irungu said.

For SBM, the move also reflects a broader shift in Kenya’s banking industry, where lenders are continuing to add physical branches even as mobile and internet banking become more dominant. Physical branches are increasingly being used for relationship management, business acquisition and complex financial services rather than simply cash transactions.

The Nanyuki branch is SBM Bank Kenya’s first new outlet since it opened its Kilifi branch in July 2025, bringing the lender’s national branch network to 34. The expansion is aimed at improving access to banking services in emerging commercial centers while allowing the bank to build deeper relationships with businesses and institutions outside Nairobi and other major cities.

The strategy is also consistent with SBM’s focus on business development at branch level. The bank’s recruitment for the Nanyuki branch has emphasized business acquisition, customer growth, profitability and alignment with the lender’s wider strategy.

With deposits approaching KSh100 billion and its loan book expanding, SBM is entering the next phase of its Kenyan growth story with a stronger financial base. Nanyuki gives the lender access to a regional economy where tourism, conservation, horticulture, agriculture and property development generate demand for both conventional banking and more specialized corporate and SME financing.

The challenge will be turning that economic activity into profitable loans and deposits while maintaining the asset-quality improvements that have helped drive the bank’s 2026 earnings recovery.

3 Problems Women in Business Face and How to Fix Them

0

As a woman, you may have noticed that the obstacles in your career do not always appear discriminatory on their own. They tend to look like a manager who stands too close, a salary you can’t compare to anyone else’s, or a project quietly reassigned after you shared some news. Each of these examples has a legal shape underneath it, but you can’t use what you can’t name. Here’s more about three common problems women in business face and how they should react.

Report Sexual Harassment Instead of Absorbing IT

If a colleague or a manager has made you uncomfortable at work, you may have spent longer questioning your own reaction than questioning his behavior. A man who behaves this way usually controls something you need, like a promotion, a shift, a client account, or a visa sponsorship, which is why sexual abuse or harassment shows up more often in workplaces with few women in senior roles.

You must understand that your employer cannot punish you for raising a complaint, which is the whole point of the protections available to you. However, only a lawyer can tell you what your evidence shows before you decide anything. These experts will make you understand that you have a second claim if an employer demotes you after a complaint, as retaliation is illegal on its own terms.


The deadlines for filing are shorter than most people expect, so the sooner you ask, the more options stay open to you. Fortunately, most employment lawyers take these cases on contingency, and the outcomes range from a negotiated exit with compensation to a policy change that protects the woman hired after you.

Do Not Accept Lower Salaries

If you suspect you’re paid less than a male colleague doing the same job, you’re unlikely to confirm it by asking your employer. Companies keep pay private for a reason; after all, a gap no one can see is a gap no one has to explain.

Your options depend partly on where you work, as a growing number of states now require employers to post salary ranges in job ads or provide them upon request. Federal law goes much further back, and the Equal Pay Act has required equal pay for substantially equal work since 1963, with job content determining what counts as equal. However, if you want to take action, you should first contact a lawyer. They can compare what you actually do against what your colleague does and tell you whether the pay gap is legal.

Push Back When Motherhood Changes How You’re Treated

If your responsibilities shrank after you announced a pregnancy, or after your caring duties became visible at work, you’ve reached the point where many women’s careers stall.  Researchers who study hiring decisions have found that mothers are judged as less committed than women without children with identical resumes. 

However, employers who act on this belief that a mother is less committed now stand on weaker legal ground than they used to. The Pregnant Workers Fairness Act requires your employer to provide reasonable accommodations for pregnancy and recovery, and a refusal is actionable by itself.

To take legal action, you need to keep a dated record of what changed and when. Only a lawyer can tell you whether what you’ve written down amounts to a claim. Fortunately, that first conversation usually costs you nothing. 

Endnote

It is common for women in business to experience unique problems, but they don’t have to solve them alone. You don’t have to be sure before you raise a question. However, working with a legal expert puts you in a better position to understand what a realistic outcome looks like before you decide whether to act.

HealthTech Startups Are Changing How Families Access Medical Information

0

When a family receives a diagnosis for a complex medical condition, the first challenge often begins after the medical appointment ends. Caregivers may search online for answers about the condition, available support, and what steps to take next, but finding accurate and easy-to-understand information is not always simple. 

Medical resources can be highly technical, spread across multiple platforms, or difficult to connect with a family’s specific situation. This article explores how HealthTech startups are solving these challenges by creating digital platforms that improve access to medical information, simplify patient education, and help families make informed healthcare decisions.

The Information Gap Families Face After a Medical Diagnosis

After receiving a diagnosis, families often need practical information about symptoms, care options, and long-term support. However, many healthcare resources are created with medical professionals as the primary audience, leaving patients and caregivers to interpret complex information on their own. The main challenges include:

  • Medical terminology that can be difficult for non-specialists to understand.
  • Information spread across multiple websites and healthcare sources.
  • Difficulty identifying trustworthy educational resources.
  • Limited guidance for preparing questions before medical appointments.

This information gap can make healthcare decisions stressful, especially for families managing conditions that require ongoing support. HealthTech startups are addressing this challenge by developing platforms that organize medical knowledge into patient-focused formats.

How HealthTech Startups Are Improving Patient Education

HealthTech companies are transforming patient education by using technology to deliver healthcare information in a more accessible way. Instead of requiring users to navigate complex medical documents, modern platforms focus on presenting information through structured guides, digital tools, and user-friendly resources. Many HealthTech solutions now provide:

  • Condition-specific educational content.
  • Simplified explanations of medical concepts.
  • Digital resources for understanding treatment and care pathways.
  • Tools that help families prepare for discussions with healthcare providers.

For families researching neurological conditions, reliable educational resources can help them understand important details about a diagnosis and available support options. Learning about specific classifications and variations of a condition allows caregivers to communicate effectively with healthcare professionals. 

Platforms such as cerebralpalsyguide.com help families explore information about different types of cerebral palsy through organized, condition-focused resources. These digital resources support better conversations between families and medical teams by helping caregivers arrive at appointments with a clearer understanding of their concerns.

Digital Tools Helping Families Make Better Healthcare Decisions

Beyond medical education, HealthTech startups are developing tools that help families manage healthcare information throughout the care journey. These solutions make it easier to organize records, communicate with specialists, and monitor important health details. Examples of digital healthcare tools include:

  • Telehealth platforms that connect families with healthcare professionals remotely.
  • Mobile applications for tracking symptoms, appointments, and treatment progress.
  • Online communities that provide caregiver support and shared experiences.

These technologies help families become more involved in healthcare planning while reducing the challenges of managing information across different providers and services.

What HealthTech Startups Need to Prioritize for Better Patient Support

Building effective healthcare technology requires a strong focus on trust and usability. Families depend on these platforms for important decisions, making accuracy and accessibility essential. HealthTech startups should prioritize:

  • Medical content reviewed by qualified professionals.
  • Simple user experiences for people with different levels of technical knowledge.
  • Accessible design features for diverse users.
  • Regular updates to reflect current healthcare guidance.

Successful healthcare platforms combine innovation with reliable information, ensuring technology supports rather than complicates the patient experience.

Endnote

HealthTech startups are changing how families find, understand, and use medical information. By creating accessible digital resources and patient-focused tools, these companies are helping people approach healthcare decisions with greater confidence.

The future of digital healthcare will depend on solutions that combine technology, accuracy, and accessibility to ensure reliable medical knowledge is available when families need it most.

Samsung Pushes Connected Home Strategy in Kenya

0

Samsung Electronics is taking its connected-home strategy directly to Kenyan consumers, using three Nairobi shopping malls to demonstrate how smartphones, televisions, wearables and AI-enabled appliances can operate as a single technology ecosystem rather than as standalone products.

The Korean electronics giant will launch its Connected Living Experience at The Junction Mall from August 28 to 30, followed by The Galleria Mall from September 4 to 6 and Sarit Mall from October 2 to 4.

The campaign is more than a conventional product showcase. It reflects Samsung’s broader attempt to shift consumers from buying individual devices to participating in an ecosystem built around SmartThings, its Internet of Things platform that connects and manages compatible devices across the home.

That shift has important implications for Samsung’s business in Kenya, where the company is competing not only on hardware but increasingly on software, artificial intelligence, connectivity and the recurring relationship it can build with consumers after a device is purchased.

Samsung says SmartThings had more than 430 million users globally as of December 2025, giving the platform a substantial installed base from which to expand connected-home services.

From gadgets to an ecosystem

For years, consumer electronics companies competed largely on specifications: the number of megapixels in a smartphone camera, the size of a television, refrigerator capacity or washing-machine efficiency.

Samsung is increasingly selling something different.

The proposition is that the Galaxy smartphone can become the control center for a home in which the television, refrigerator, washing machine, air conditioner and other appliances communicate with one another.

Its SmartThings platform allows users to remotely control compatible devices, create automations and monitor energy consumption. Samsung has also expanded the platform with features such as 3D Map View, device diagnostics, energy management and home routines.

The Nairobi activation is designed to make that proposition tangible.

Instead of placing a phone, television or refrigerator on separate display stands, Samsung will recreate living-room, kitchen and laundry environments where consumers can see how the products interact.

That distinction matters because connected-home technology can be difficult to sell when its benefits remain theoretical. A consumer may understand why a new television has a better display, but the economic and practical value of connecting that television to a refrigerator, smartphone or washing machine is less immediately obvious.

Samsung is effectively turning the mall into a live demonstration of its ecosystem strategy.

AI is becoming the connective layer

Artificial intelligence is central to the pitch.

Samsung’s latest connected-home strategy goes beyond allowing consumers to switch appliances on and off remotely. The company is increasingly using AI to interpret usage patterns, automate routines and optimize the operation of connected devices.

SmartThings’ AI Energy Mode, for example, is designed to analyze usage patterns and adjust connected appliances to reduce energy consumption. Samsung’s Africa platform highlights energy management as one of the core use cases for its connected-home ecosystem.

That is particularly relevant in Kenya, where electricity costs and household energy consumption are important considerations for consumers.

Samsung has also been extending AI deeper into individual appliances. Its AI-enabled refrigerators, for example, can use AI Vision to identify food items and support food-management and recipe functions, while connected cooking appliances can receive instructions through the SmartThings ecosystem.

The result is a shift in the definition of an appliance.

A refrigerator is no longer simply a machine that keeps food cold. A television is no longer simply a screen. A washing machine is increasingly positioned as part of an intelligent household system.

Kenya becomes an important test market

Samsung’s decision to take the experience into three major Nairobi malls also highlights the importance of physical consumer engagement in a market where smart-home adoption is still developing.

The company needs consumers to understand the value proposition before asking them to invest in multiple connected devices.

That creates a potentially important commercial cycle.

A consumer may initially purchase a Galaxy smartphone, then add a Samsung television, followed by an appliance. Each additional device increases the usefulness of the ecosystem and creates another opportunity for Samsung to retain the customer within its hardware and software environment.

The strategy is already visible in Samsung’s wider Kenyan business.

The company recently used a Nairobi event to promote SmartThings alongside its Galaxy A Series smartphones, demonstrating appliance and lighting controls as part of a broader push to make the smartphone an entry point into the connected home.

Samsung has also positioned its 2026 television lineup in Kenya around AI and SmartThings, turning the television into a dashboard for connected devices rather than simply an entertainment product.

The bigger opportunity is beyond households

The connected-home strategy could also give Samsung a pathway into Kenya’s commercial property market.

Samsung already markets SmartThings Pro as a business-focused IoT platform for residential developments, hotels, offices and other commercial environments. The platform allows businesses to remotely manage connected equipment, monitor energy consumption and automate building operations.

That creates a much larger addressable market than individual household appliances.

Property developers could use connected technology as an amenity in new apartments. Hotels could offer guests digitally managed rooms. Offices could automate heating, cooling and other building systems.

For Samsung, that means SmartThings can potentially become more than a consumer application. It can become infrastructure sitting behind homes, buildings and commercial spaces.

Retail promotions are part of the strategy

The Nairobi activation also combines technology education with retail incentives.

At The Junction Mall, Samsung says Azone Outlet will offer discounts of up to 60% on selected home appliances, while Carrefour will offer discounts of up to 25%. Quick Plug will offer discounts of up to 10% on selected Samsung mobile devices, alongside bundled accessories on selected products.

The commercial logic is straightforward: demonstrate the ecosystem, then reduce the friction involved in purchasing the hardware required to build it.

This is important because connected-home ecosystems face a classic adoption problem. The technology becomes more valuable as consumers own more compatible devices, but the initial cost of assembling those devices can be significant.

Retail promotions can help Samsung move consumers from curiosity to adoption.

The battle is moving from devices to relationships

Samsung’s Kenyan strategy reflects a broader change in consumer technology.

Hardware remains the foundation of the business, but the competitive advantage increasingly comes from what happens after the sale.

A smartphone that connects seamlessly to a television, refrigerator and washing machine is harder to replace with a competitor’s device if the consumer has already invested in the ecosystem.

That creates a form of customer lock-in driven not necessarily by restrictions, but by convenience.

Samsung is also not building its ecosystem entirely in isolation. SmartThings supports compatible third-party devices and industry standards such as Matter, broadening the potential range of products that can participate in connected-home environments.

The challenge will be converting the concept into meaningful mass-market adoption.

Kenyan consumers are likely to judge connected-home technology less by how futuristic it looks in a shopping mall and more by whether it saves time, reduces electricity consumption, improves convenience and justifies the additional cost.

Samsung’s three-city activation will give the company an opportunity to make that case directly.

For Samsung, however, the stakes are larger than a series of mall demonstrations. The company is betting that the next phase of consumer electronics in Kenya will not be defined by which device has the best specifications, but by which technology company can make all the devices in a consumer’s life work better together. And Samsung wants SmartThings to be at the center of that relationship.

Uber’s $966 Million GDPR Fine Puts Algorithmic Management Under Scrutiny

Uber Technologies Inc. has been hit with an €825 million ($966 million) fine by the Dutch data protection regulator over the use of automated systems to suspend and deactivate drivers, putting the growing use of algorithms to manage gig workers under renewed regulatory scrutiny.

The Dutch Data Protection Authority, known as the Autoriteit Persoonsgegevens or AP, said Uber violated the European Union’s General Data Protection Regulation by allowing automated systems to make decisions affecting drivers without adequate human intervention and by failing to properly inform them about the process.

The penalty is the second-largest fine issued under the GDPR, behind the €1.2 billion penalty imposed on Meta Platforms in 2023. The Dutch regulator said the violations occurred between 2018 and 2022.

The case goes beyond Uber. It puts a spotlight on a fundamental question facing technology companies as artificial intelligence and automated decision-making become embedded in digital businesses: How much power should companies give software to determine whether a person can earn a living?

When an Algorithm Becomes a Gatekeeper

Uber’s business depends heavily on software. Algorithms match passengers with drivers, calculate fares, detect suspected fraud and monitor activity across the platform.

That automation allows Uber to operate at enormous scale. But the Dutch regulator found that some of the company’s automated systems went further, making decisions that could directly affect drivers’ ability to work.

The investigation followed complaints from 171 drivers represented by the French human-rights organization Ligue des droits de l’Homme. Because Uber’s European headquarters are in Amsterdam, the Dutch authority handled the case under the EU’s regulatory framework for cross-border data protection enforcement.

According to the regulator, Uber’s systems were used to suspend drivers suspected of fraudulent behavior, including alleged unnecessary detours designed to increase fares or accepting rides without completing them. Drivers could also be permanently removed from the platform based on low customer ratings.

The AP said the problem was not simply that Uber used algorithms. It was that the company allowed automated processing to produce significant consequences without adequate human oversight and did not properly inform drivers about the automated decision-making involved.

That distinction is increasingly important as companies automate decisions that once required a manager, investigator or customer-service representative.

GDPR Puts Limits on Automated Decisions

The legal foundation for the case is Article 22 of the GDPR, which gives individuals protections against decisions based solely on automated processing when those decisions have legal or similarly significant effects.

For a ride-hailing driver, losing access to a platform can have an immediate economic impact. A driver who depends on Uber for income can go from receiving trips to receiving none, potentially without warning.

The Dutch regulator said Uber’s practices breached drivers’ rights because the automated decisions could have significant consequences and because drivers were not adequately informed about the process.

The case illustrates why algorithmic management is becoming a major regulatory issue.

A recommendation algorithm deciding which video a user sees is one thing. An algorithm deciding whether a worker can continue earning money is another.

Uber Disputes the Findings

Uber said it strongly disagrees with the decision and considers the fine disproportionate. The company plans to appeal.

The company argues that the Dutch regulator examined historical policies that were discontinued years ago and said its current systems include human reviews, safeguards and mechanisms through which drivers can challenge suspensions.

Uber has also disputed the regulator’s characterization of its permanent deactivations. The company said only 126 drivers in Europe were permanently deactivated because of customer ratings in 2021 and argued that permanent account closures were not carried out solely by automated systems.

The appeal could therefore become an important test of how European regulators and courts interpret the boundary between automated decision-making and meaningful human oversight.

The issue is not whether Uber can use algorithms. It is whether the company must ensure that a human being has a genuine opportunity to review a consequential decision before it takes effect.

A Bigger Fight Over Algorithmic Management

The Uber case arrives as European regulators are increasing their scrutiny of how technology companies use artificial intelligence, personal data and automated decision-making.

For years, algorithms have quietly become part of the management infrastructure of the gig economy.

Ride-hailing companies use software to determine which drivers receive requests. Delivery platforms monitor completion rates and cancellations. Marketplaces identify suspected fraud. Financial platforms use automated systems to assess customers and transactions.

The efficiency gains are substantial. A platform serving millions of users cannot manually review every transaction.

But automation creates a different problem when an algorithm makes a mistake.

A human manager can hear an explanation, reconsider evidence or recognize that an unusual event does not necessarily indicate fraud. An automated system may simply classify the behavior and trigger a predetermined response.

That is why regulators are increasingly focusing not only on whether algorithms are accurate, but also on whether people affected by those algorithms have transparency, recourse and access to meaningful human intervention.

The Africa Implications

The issue is particularly relevant to Africa, where ride-hailing and other platform businesses have become increasingly important parts of urban economies.

Uber operates across several African markets, while competitors and other digital platforms have built businesses around similar models. In cities such as Nairobi, Lagos, Johannesburg and Accra, drivers and delivery workers increasingly interact with platforms through algorithms that influence their access to customers and income.

The Dutch decision does not automatically impose European GDPR obligations on every African platform. But it provides a warning about the direction of regulation as African governments strengthen data-protection regimes and examine how technology companies use personal information.

For African startups, the lesson is not that algorithms should be avoided.

It is that algorithmic efficiency cannot come at the expense of accountability.

A platform that automatically blocks a driver, freezes an account, rejects a transaction or identifies a user as fraudulent needs to consider what happens when the system is wrong.

That becomes even more important as artificial intelligence makes automated decisions increasingly sophisticated and harder for ordinary users to understand.

The Cost of Getting Automation Wrong

The €825 million penalty is large enough to make algorithmic governance a boardroom issue.

European data-protection rules can impose fines of significant proportions of a company’s global turnover, meaning failures involving personal data and automated decision-making can become material financial risks rather than simply compliance issues.

The Dutch regulator’s action also marks the fourth significant penalty it has imposed on Uber. Its previous major enforcement action against the company included a €290 million fine in 2024 over the transfer of European drivers’ personal data to the United States without adequate protection.

Uber’s appeal means the final legal outcome could take time. But the regulatory message is already clear.

Companies can automate the management of millions of interactions, but they cannot necessarily automate responsibility.

As artificial intelligence moves deeper into hiring, lending, insurance, customer service, fraud detection and platform work, the question of who gets to challenge an algorithm’s decision will become increasingly important.

For Uber, that debate has produced a $966 million price tag.

For the broader technology industry, it could be the beginning of a much larger reckoning over who is accountable when software decides who gets to work.

Rosemary Koech-Kimwatu Built a Career at the Intersection of Law, Technology and Africa’s Digital Future

Kenya’s technology story is often told through the founders who built companies, the investors who financed them and the executives who took African businesses into new markets. Less visible are the lawyers, policy specialists and governance professionals who helped create the rules under which that digital economy could grow.

Rosemary Koech-Kimwatu was one of them. For nearly two decades, Koech-Kimwatu worked across law, fintech, telecommunications, public policy and data protection, building a career around an increasingly important question for Africa’s digital economy: how can technology scale while protecting the people and institutions that depend on it?

Her answer evolved with the technology itself.

She moved from traditional legal and regulatory work into fintech, then public policy in telecommunications, and ultimately into senior data-protection leadership at KCB Bank Group. Along the way, she became an active participant in Kenya’s internet-governance and technology-policy community, helping bring legal thinking into conversations that increasingly involved digital rights, innovation, privacy and regulation.

Koech-Kimwatu died on August 21, 2026, at her home in Ngong. She was 40. Her family has not publicly disclosed the cause of her death. Her death has prompted tributes across Kenya’s technology, legal, fintech and data-protection communities, where she was remembered not simply for the positions she held but for the bridges she built between industries.

Education That Went Beyond The Law

Koech-Kimwatu’s professional story began with law, but her education was broader than the traditional path into legal practice.

She earned a Bachelor of Laws degree from the University of Nairobi, giving her the legal foundation that would later become central to her work in technology regulation and public policy. She subsequently obtained an Advanced Diploma in Public Relations from the Chartered Institute of Public Relations, an unusual but revealing combination for someone who would eventually spend much of her career operating between business, government, technology and the public.

Her academic choices would prove valuable as technology companies increasingly found themselves operating in environments where legal compliance alone was not enough.

Technology businesses needed to understand regulators. Regulators needed to understand innovation. Companies needed to communicate complex policy questions to customers, governments and other stakeholders. And lawyers increasingly needed to understand technologies that did not exist when many of the country’s traditional legal frameworks were written.

Koech-Kimwatu built her career around that intersection. She became an Advocate of the High Court of Kenya, while developing expertise in technology law, public policy, fintech regulation and data protection. The result was a professional profile that could move comfortably between legal analysis and the commercial realities of fast-changing technology businesses. That combination became one of her defining advantages.

From Legal Practice To Fintech

Before she became widely known for data protection, Koech-Kimwatu had already spent years working in Kenya’s emerging fintech industry.

She began her professional career at Caritas Nairobi, where she served as a Legal and Administrative Officer and contributed to the establishment of Caritas Microfinance Bank. She subsequently moved into technology and fintech, serving as Senior Associate for Legal and Regulatory Affairs at Mobile Decisioning Holding Ltd. (MODE) before becoming Head of Legal and Regulatory Affairs at fintech company WayaWaya.

Those roles placed her inside an industry undergoing a profound transformation. Kenya’s financial system was increasingly moving away from the traditional model of banking through physical branches and toward mobile money, digital payments, automated decision-making and technology-enabled financial services. For lawyers working in the sector, that meant the job was changing too.

It was no longer enough to interpret established financial regulations. Technology companies were creating new products, new customer relationships and new ways of moving money, forcing regulators and businesses to constantly negotiate questions around licensing, consumer protection, data and financial inclusion.

Koech-Kimwatu became part of that emerging legal and regulatory infrastructure. Her colleagues at Oxygène Marketing Communications later described her as someone whose ability to identify the links between law and innovation strengthened the company’s public-policy work.

The Move Into Public Policy

Koech-Kimwatu later joined Oxygène Marketing Communications, where she served as a Legal and Regulatory Specialist before becoming Head of Public Policy. The move was significant because it took her work beyond advising individual companies and into the wider policy environment shaping technology markets.

Public policy sits at a difficult intersection.

Businesses want predictable rules that allow them to innovate. Governments want regulation that protects citizens and advances national interests. Consumers want convenience without surrendering their rights. Technology companies want to scale across borders even though regulations remain largely national.

Koech-Kimwatu’s career increasingly placed her in the middle of those competing interests.

Her expertise became particularly relevant as Kenya’s technology economy matured and issues such as mobile communications, fintech, digital identity, cybersecurity, privacy and data governance moved closer to the center of national policy debates.

Safaricom And The Business Of Regulation

In 2020, Koech-Kimwatu joined Safaricom as a Public Policy Manager after her time at Oxygène.

The move brought her into one of the most important technology companies in East Africa and into an industry where policy and commercial strategy are inseparable. Safaricom operates at the heart of Kenya’s digital economy. Its businesses touch telecommunications, mobile money, payments, financial services and digital platforms, meaning regulatory decisions can have consequences far beyond the company itself.

For Koech-Kimwatu, the role provided another opportunity to apply her legal background to technology policy at scale. It also placed her closer to the questions that would eventually define the final stage of her career: how businesses should collect, process, use and protect information in an increasingly digital economy.

KCB And The Rise Of Data Protection

In June 2022, Koech-Kimwatu left Safaricom for KCB Bank Group, joining the lender as Group Data Protection Officer. She was promoted to Head of Data Protection in June 2023, taking responsibility for data-protection compliance across the banking group. The timing mattered.

Kenya’s Data Protection Act, 2019 had fundamentally changed the country’s approach to personal information, establishing obligations for organisations that collect and process personal data. For banks, the implications were particularly significant. A financial institution can hold some of the most sensitive information about an individual: identification details, account information, transaction histories, income patterns, credit information and records of financial behavior.

As banking becomes increasingly digital, the amount of data generated by those relationships continues to grow. Koech-Kimwatu’s role at KCB therefore went far beyond a conventional compliance function. It placed her at the intersection of technology, banking, privacy, regulation and customer trust.

Her professional journey had effectively come full circle. The lawyer who began working on legal and administrative issues had become a senior executive responsible for helping one of East Africa’s largest financial groups navigate the increasingly complex world of personal data.

Building The Institutions Around Kenya’s Digital Economy

Her influence was not confined to corporate Kenya.

Koech-Kimwatu was deeply involved in the country’s wider technology-policy ecosystem. She served as a trustee of KICTANet, participated in Kenya’s internet-governance community and was involved with the Kenya School of Internet Governance. She also chaired multistakeholder advisory groups associated with the Kenya and East Africa Internet Governance Forums.

These platforms may not command the visibility of venture-capital announcements or technology product launches, but they play an important role in determining how Africa’s digital economy develops. Internet governance brings together governments, businesses, civil society, academics, technologists and legal professionals around questions that increasingly affect everyday life.

Who controls data? How should platforms be regulated? How should digital rights be protected? What responsibilities should technology companies have? How should governments respond to emerging technologies? And how can African countries participate meaningfully in global technology-policy discussions rather than simply importing rules developed elsewhere? Koech-Kimwatu contributed to those conversations from the perspective of someone who understood both the law and the commercial technology environment.

A Lawyer Who Became A Technology Professional

Perhaps the most interesting part of Koech-Kimwatu’s career is that she did not abandon her legal training when she entered technology.

She expanded what that training could mean. Her career illustrates how the role of a lawyer has changed as technology has become embedded in almost every major sector of the economy. The courtroom was only one possible destination. Legal expertise could be applied to fintech product development, telecommunications policy, data governance, digital rights, corporate compliance and technology regulation.

Koech-Kimwatu became part of a generation of African professionals proving exactly that. Her recognition reflected this evolution. In 2020, she was named to CIO Africa’s inaugural Most Influential Women in Digital Transformation list. She was also recognized by the International Legal Technology Association among its influential women in legal technology, while Africa’s legal-innovation community recognized her contribution to the field.

These were not simply awards for a legal career. They reflected the emergence of a new category of professional in Africa: the technology lawyer who understands that regulation itself is becoming part of the innovation ecosystem.

Her Legacy Is Bigger Than Data Protection

It would be easy to remember Koech-Kimwatu simply as KCB’s Head of Data Protection. That would undersell her career. Her more important contribution was helping Kenya navigate the difficult transition from an economy where technology was an emerging sector to one where technology has become infrastructure.

When money moves through mobile phones, when banks make decisions using algorithms, when businesses collect information from millions of customers and when governments increasingly deliver services digitally, law and technology can no longer operate as separate disciplines.

They have to work together. Koech-Kimwatu understood that early. She spent her career moving between the worlds that needed to understand one another: lawyers and technologists, companies and regulators, innovators and policymakers. That work rarely generates the headlines associated with a major funding round or a new technology product. Yet without it, digital economies cannot mature sustainably.

The Questions She Leaves Behind

Kenya’s technology sector is entering another major transition.

Artificial intelligence is changing how companies make decisions. Financial institutions are processing increasingly sophisticated datasets. Digital identity is becoming more important to commerce and public services. Cybersecurity threats are expanding. Regulators are trying to keep pace with technologies that evolve faster than legislation.

The questions Koech-Kimwatu spent her career addressing will therefore become more important in the years ahead.

How much data should companies collect? How should that information be used? What rights should consumers have? How can businesses innovate without weakening privacy? And who should be accountable when technology causes harm?

These are no longer theoretical questions for Kenya. They are business questions, policy questions and questions of public trust. Koech-Kimwatu spent much of her professional life preparing institutions to confront them. Her legacy is therefore not only the policies she helped develop or the organisations she served. It is also the professionals she influenced, the conversations she helped shape and the idea that Africa’s technology future must be built with both innovation and accountability.

For a country that has become one of the world’s most closely watched digital markets, that is a significant contribution. Rosemary Koech-Kimwatu’s career showed that sometimes the people who help shape a technology revolution are not the ones building the next app. They are the ones helping society decide what the app should be allowed to do.

TechMoran extends its condolences to her family, friends, colleagues and the wider technology, legal, fintech and digital-policy communities mourning her loss.